Connect with us
Anglostratits

Business

Thailand Approves $29 Billion Investment Wave as Data Center Demand Surges

Published

on

Thailand

TikTok leads new BOI approvals as Thailand moves to strengthen power readiness, clean energy access and fast-track strategic investment
BANGKOK, THAILAND – Media OutReach Newswire – 6 May 2026 – Thailand’s Board of Investment (BOI) has approved six major projects worth a combined 958 billion baht, or approximately USD 29 billion, led by a large-scale data infrastructure expansion by TikTok System (Thailand) Co., Ltd., underscoring the country’s growing role as a regional hub for data centers, cloud services and AI-driven digital infrastructure.

The approvals were made at a BOI Board meeting chaired by Mr. Ekniti Nitithanprapas, Deputy Prime Minister and Minister of Finance. The Board also approved a second batch of projects under the Thailand FastPass mechanism and discussed with energy agencies steps to strengthen electricity readiness and improve access to clean energy — two increasingly important factors in attracting large-scale digital and high-technology investment.

Mr. Narit Therdsteerasukdi, Secretary General of the BOI, said the latest approvals reflect growing investor confidence in Thailand at a time when global companies are racing to expand digital infrastructure across Asia.

“Amid continuing global volatility, investment in Thailand’s digital and advanced technology sectors continues to grow, reflecting investor confidence in the country’s potential as a regional technology hub,” Mr. Narit said. “For Thailand to capture this new investment cycle, we must be ready not only with investment incentives, but also with sufficient power, clean-energy options, skilled talent, deeper supply chains and a reliable facilitation system that allows projects to move quickly from approval to operation.”

Of the six approved projects, three are in data center and data hosting services, with a combined investment value of 913 billion baht, or approximately USD 27 billion.

The largest project is by TikTok System (Thailand) Co., Ltd., valued at 842 billion baht, or approximately USD 25 billion. The project will install additional servers and expand data storage and processing infrastructure across Bangkok, Samut Prakan and Chachoengsao Province, supporting rising demand for digital services and strengthening Thailand’s role in regional digital infrastructure.

Beyond its core infrastructure investment, TikTok has also committed to developing digital literacy and e-commerce curricula to help create new business opportunities for Thai entrepreneurs and strengthen the country’s digital workforce.

Another approved project is a 46 billion baht, or USD 1.4 billion, data center investment by Skyline Data Center and Cloud Services Co., Ltd., part of the UAE-based DAMAC Group. Located in Chachoengsao, the project will support an IT load of 200 megawatts.

A third data center project, by Bridge Data Centres IIO (Thailand) Co.,Ltd. from Singapore, was approved with an investment value of 24.6 billion baht, or USD 746 million. Located in Chonburi, the project will support an IT load of 134 megawatts.

The remaining approved projects cover renewable energy, circular economy and resource-based industries. PureCycle (Thailand) Co.,Ltd. will invest 8.18 billion baht, or USD 248 million, in recycled plastic pellet production in Rayong, using technology exclusively licensed from P&G, with Thailand serving as a key production base for the Asian market. Dan Khun Thot Wind One Co., Ltd. will invest 4.7 billion baht, or USD 143 million, in an 89-megawatt wind power generation project in Nakhon Ratchasima. ASEAN Potash Chaiyaphum Plc. will invest 31.4 billion baht, or USD 952 million, in potassium chloride production in Chaiyaphum, producing a key input for potash fertilizer.

To accelerate project implementation, the BOI Board also selected nine additional projects worth 52 billion baht, or USD 1.6 billion, for Thailand FastPass, following the first batch of 16 projects. The latest selection brings the FastPass portfolio to 25 projects, with a combined investment value of 223 billion baht, or USD 6.8 billion.

The FastPass mechanism is designed to streamline approval and permitting procedures, speed up coordination among relevant agencies — including the BOI, the Department of Industrial Works, the Industrial Estate Authority of Thailand, the Office of Natural Resources and Environmental Policy and Planning, the Customs Department and power-related agencies — and help strategic projects begin operations faster.

At the same meeting, the Board outlined steps to strengthen electricity readiness with the Ministry of Energy and the Energy Regulatory Commission, focusing on urgent power supply needs for incoming investment, particularly in the Eastern region. The Board also directed action on accelerating the issuance of Thailand’s Power Development Plan (PDP) to support future demand, new energy technologies and long-term power-system planning.

The Board also advanced plans for clean energy mechanisms, including Direct Renewable Power Purchase Agreements, or Direct PPA, which would allow private companies to buy and sell renewable electricity directly, with participation criteria and grid-service charges to be announced shortly. The Board also acknowledged the launch of Utility Green Tariff 2, or UGT2, a source-specific green tariff designed to give companies more options for procuring clean electricity.

The Board also tasked the BOI with coordinating with relevant agencies to consider regulatory improvements that would facilitate clean energy investment, including easing power-generation licensing conditions for foreign operators installing solar rooftops, and clarifying rules to support self-generation under Independent Power Supply, or IPS, arrangements.

Mr. Narit said the combination of large-scale digital investment, power readiness, clean energy access, skilled talent and faster investment facilitation is central to Thailand’s competitiveness in the next phase of global investment.

“Thailand is entering a new investment cycle in which speed, power readiness, clean energy access and skilled talent will be decisive,” he said. “The BOI is working with partner agencies to ensure that major projects can move from approval to operation as quickly as possible, while strengthening the infrastructure, workforce, supply chains and ecosystem needed for long-term growth in the digital economy.”

USD conversion based on an estimated exchange rate of 33 baht per USD.
Energy

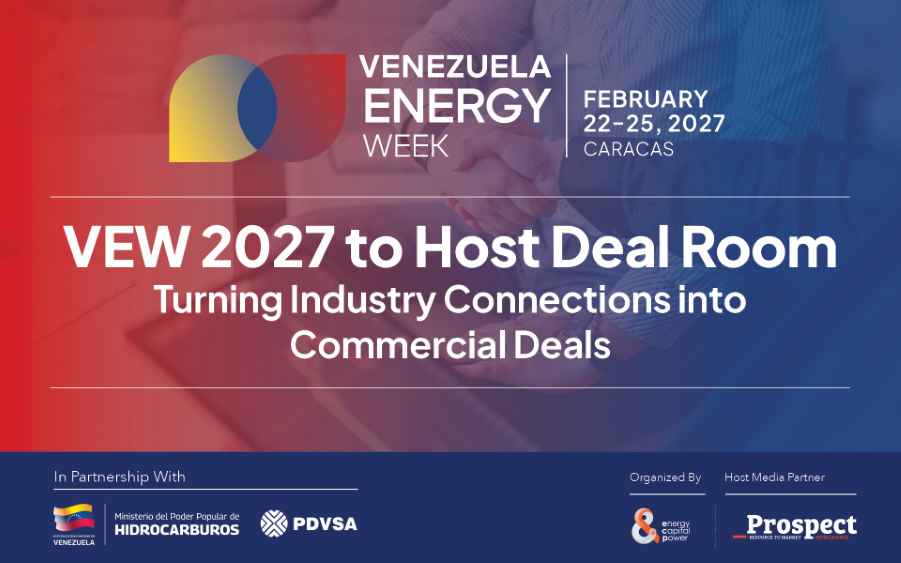
Venezuela Energy Week (VEW) 2027 Deal Room Targets Joint Ventures, Service Agreements and Offtake Partnerships

Published

on

Venezuela Energy Week

Register as a commercial partner at Venezuela Energy Week 2027 to connect with Venezuelan operators, projects and strategic energy opportunities

International operators, oilfield service companies and strategic partners are invited to register as commercial partners for the Venezuela Energy Week (VEW) 2027 Deal Room, where companies can pursue joint ventures, service agreements, technology deployments, offtake arrangements and other commercial opportunities.


Taking place February 22–25 at the Simón Bolívar Convention Center in Caracas, the Deal Room will bring international companies into direct discussions with local operators, project developers, asset owners and regional leadership. As international companies re-engage with Venezuela’s oil and gas industry, the platform aims to facilitate project-level discussions and establish commercial relationships spanning upstream development, infrastructure, technology and energy supply.

For international operators and investors, the Deal Room provides an opportunity to identify assets and local counterparties for joint development. Venezuela’s push to increase oil production to 1.3 million barrels per day (bpd) in 2026 and 1.5 million bpd in 2027 is creating potential openings for companies with the technical expertise, operational capacity and financial resources to participate in field rehabilitation, enhanced oil recovery, drilling and production expansion. Partnerships with Venezuelan operators can provide a route to developing assets and sharing project responsibilities.

Recent agreements demonstrate how partnerships have already begun to take shape. In September, Chevron secured expanded development rights in the Orinoco Belt, underpinning plans by its Venezuelan joint ventures to invest more than $7 billion over five years. Eni also signed a 25-year contract with PDVSA to assume operatorship of the Junín 5 heavy-oil field, giving the company responsibility for its technical, financial and commercial development.

Oilfield service companies and technology providers can pursue commercial agreements supporting these activities. Demand spans drilling and workover equipment, artificial lift, engineering, digital production systems, reservoir technologies, power solutions and other services required to restore production and improve the performance of existing infrastructure.

Commercial partnerships are advancing this area. In September, Halliburton signed separate agreements with Eneva and WESCA covering development opportunities, field evaluation and technical planning, while SLB signed a framework agreement with PDVSA in June spanning field development, digital technologies and workforce training.

The commercial opportunity extends beyond upstream operations. Companies can explore technology and service partnerships supporting gas processing and transportation, refinery rehabilitation, power generation, grid infrastructure and energy logistics, creating multiple routes for international suppliers and specialist firms to establish a presence in the market and for Venezuelan companies seeking to strengthen their portfolios.

Recent agreements reflect growing momentum in these areas. In September, GE Vernova signed a strategic alliance with PDVSA to rehabilitate electrical infrastructure serving Venezuela’s oil industry. More recently, Baker Hughes partnered with PDVSA, Venezuelan engineering company Lindsayca and Fulcrum LNG to pursue gas processing, transportation and commercialization projects.

Offtake and supply agreements offer another route for strategic participation. Companies can negotiate arrangements linked to specific oil, gas or refined-product assets, while international trading and downstream partners can explore supply relationships connected to Venezuela’s expanding production and processing capacity. Trading companies Vitol and Trafigura have already secured agreements to purchase and market Venezuelan oil, while international refiners are increasingly pursuing direct supply relationships with PDVSA.

The Deal Room will also provide direct access to the institutions shaping project development and commercial activity, including the Ministry of Hydrocarbons, PDVSA and its operating leadership. These relationships can help companies identify counterparties, clarify project requirements and develop commercial frameworks around specific opportunities.

As international activity accelerates across Venezuela’s energy sector, the Deal Room offers companies a focused setting to identify partners and convert market interest into concrete commercial relationships.

International operators, service companies and strategic partners can register to engage as commercial partners at the Venezuela Energy Week 2027 Deal Room. To engage as a commercial partner email info@venezuelaenergyweek.com or visit https://apo-opa.co/4z16kLV for more information.

Distributed by APO Group on behalf of Energy Capital & Power.


Continue Reading

Business

Guinea-Bissau Natural Resources Minister to Join Petroguin Delegation at Mauritania, Senegal, The Gambia, Guinea-Bissau, and Guinea-Conakry (MSGBC) 2026

Published

on

Etu Energias

The former head of the Senegal-Guinea-Bissau joint zone agency returns to Dakar as Chevron’s arrival and fresh seismic work are lifting interest in Guinea-Bissau’s deepwater

DAKAR, Senegal, October 23, 2026/APO Group/ –Júlio Mamadu Baldé, Guinea-Bissau’s Minister of Natural Resources, will attend MSGBC Oil, Gas & Power 2026 in Dakar at the invitation of Senegal’s Minister of Energy and Petroleum, Dr. El Hadji Abdourahmane Diouf. National oil company Petroguin will accompany him with a delegation of its own, giving the conference a strong Bissau-Guinean presence during the most active period for the country’s offshore in nearly two decades.


Chevron’s entry in November 2025 brought a supermajor into Guinea-Bissau’s deepwater for the first time. The company operates Blocks 5B and 6B with a 90% interest in each, while Petroguin holds the remaining 10%. In April 2026, Petroguin formed a joint venture with Tender Oil & Gas covering Blocks 5C and 6C, with plans for new seismic surveys aimed at advancing the acreage toward exploration drilling.

As a longstanding participant in this important event, it will be a great pleasure for us to attend once again

Apus Energy’s Atum-1X well, spudded on the Sinapa license in September 2024 in roughly 890 meters of water, was Guinea-Bissau’s first deepwater exploration well. The project re-opened the country’s offshore acreage and reignited global interest in Guinea-Bissau’s potential as a producer in the MSGBC region. In the two years since, Petroguin has expanded the data available to explorers. On October 15, at African Energy Week in Cape Town, the company signed an agreement with Norwegian geoscience firm TGS to reprocess more than 11,000 km² of 3D seismic data, with final products expected in the fourth quarter of 2027.

Baldé took office in April 2026 after nearly two decades as Secretary General of the Agence de Gestion et de Coopération (AGC), which oversees the maritime zone jointly administered by Senegal and Guinea-Bissau. “As a longstanding participant in this important event, it will be a great pleasure for us to attend once again,” said Minister Baldé.

In Dakar, Minister Baldé and the Petroguin delegation will join Senegal’s government leadership and the international companies now evaluating acreage across the basin. The conference will also host its inaugural Data Room, offering investors direct access to regional acreage, subsurface data and partnership opportunities, as MSGBC Oil, Gas & Power 2026 positions Guinea-Bissau’s frontier blocks for global investment.

Organized by Energy Capital & Power (ECP), MSGBC Oil, Gas & Power 2026 takes place December 1–3 at the Centre International de Conférences Abdou Diouf in Dakar, under the High Patronage of President Bassirou Diomaye Faye and in partnership with Senegal’s Ministry of Energy and Petroleum. For more information and registration, visit www.MSGBCOilGasandPower.com.

Distributed by APO Group on behalf of Energy Capital & Power.


Continue Reading

Business

Côte d’Ivoire’s Poro Power Solar Plant Earns International Awards for Pioneering Africa Finance Corporation-Led Project

Published

on

Poro Power

The facility is expected to become Côte d’Ivoire’s largest solar plant when operational in 2027

LONDON, October 23, 2026/APO Group/ –Côte d’Ivoire’s Poro Power solar project has received international recognition for a pioneering investment structure led by Africa Finance Corporation (AFC) (www.AfricaFC.org/), demonstrating how African capital can be mobilised to develop essential infrastructure and accelerate the transition to cleaner energy. The facility is expected to become Côte d’Ivoire’s largest solar plant when operational in 2027.


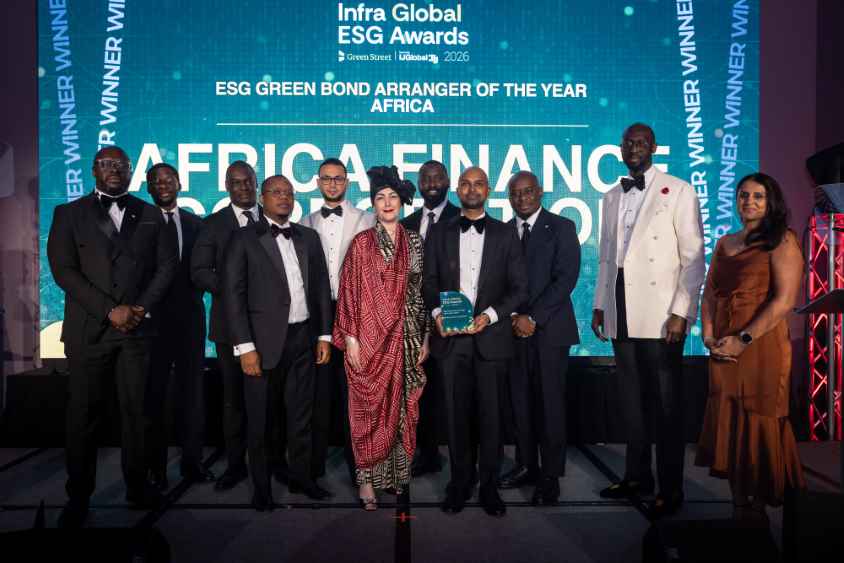
The project won ESG Green Bond Deal of the Year for Africa at the recent Infra Global ESG Awards 2026 in London, while AFC received ESG Green Bond Arranger of the Year for Africa. The double honours recognise the innovation behind the Poro Power transaction and AFC’s role in structuring and mobilising investment for sustainable infrastructure.

Developed by Ivorian entrepreneurs, the 66-megawatt solar plant is under construction in northern Côte d’Ivoire near the city of Korhogo. It is projected to generate approximately 136 gigawatt-hours (GWh) of electricity annually, meeting the needs of more than 100,000 households and benefiting an estimated half a million people.

Beyond providing homes, public services and businesses with reliable power, the project will help Côte d’Ivoire towards meeting its target of increasing renewable energy’s share of electricity generation to 45% by 2030. The Government of Côte d’Ivoire is enabling projects such as Poro Power through its initiative to encourage local private-sector participation in large-scale renewable energy projects, led by the Ministry of Mines, Petroleum and Energy under Minister Mamadou Sangafowa-Coulibaly.

“These awards are a tremendous recognition for an Ivorian project developed to meet the needs of our own communities,” said Jean-Marc Aie, Chairman and CEO of Poro Power 1 S.A. “Our ambition is not simply to generate clean electricity, but to support businesses, create opportunities and contribute to the development of Côte d’Ivoire. The Ministry’s strategy to empower local private developers to undertake large-scale renewable energy projects, together with AFC’s investment and innovative financing structure, has been instrumental in bringing Poro Power to this stage.”

Poro Power demonstrates that African financial institutions have both the capital and the expertise to finance large-scale renewable energy infrastructure through our own markets

The €65 million financing package, equivalent to approximately FCFA 42.6 billion, was raised through a green bond — an investment instrument that enables institutions to lend money to projects delivering environmental benefits. It was the first project-finance green bond in both Côte d’Ivoire and the West African Economic and Monetary Union (WAEMU), establishing a precedent for French-speaking West Africa, and was led, structured and fully funded by African institutions. The transaction allowed investors to participate in both euros and CFA francs, making it also Côte d’Ivoire’s first dual-currency green bond. Together, these features demonstrate how African financial institutions can mobilise their own capital for major infrastructure projects, using financing structures suited to African markets.

AFC invested €43 million (approximately FCFA 28.2 billion) in February 2026 and acted as anchor investor, lead underwriter and co-arranger. The equivalent of a further €22 million was raised from African investors, including local and regional banks, pension funds, insurance companies and high-net worth investors.

The bond has a 15-year term, a fixed interest rate of 8.75%, and quarterly repayments following a two-year construction grace period. The financing combines the flexibility of a bond with safeguards normally used in project finance, including first-ranking security, dedicated revenue accounts and contractual protections that separate the project’s cash flows from other activities. These measures help protect investors and align repayments with the plant’s expected revenues.

By bringing together AFC’s investment alongside capital from other African institutions through a structure that accommodates both local and international currencies, the transaction offers a potential model for financing further renewable energy and infrastructure projects across the region. Its significance extends beyond Poro Power, providing a practical example of African money financing African projects and a structure that could be replicated across the continent.

“Poro Power demonstrates that African financial institutions have both the capital and the expertise to finance large-scale renewable energy infrastructure through our own markets,” said Sameh Shenouda, Executive Board Member and Chief Investment Officer of AFC. “By combining the protections required for long-term project finance with the flexibility of capital markets, we have created a structure that can attract a broader range of African investors. This is an important model for mobilising the investment needed to expand reliable electricity supply, support industry and accelerate the energy transition across the region.”

Once operational, the plant is projected to avoid approximately 72,000 tonnes of carbon dioxide emissions annually — equivalent to taking around 15,600 petrol-powered cars off the road for a year.

The project includes a commitment to allocate €0.01 for every megawatt-hour of electricity generated towards to initiatives intended to benefit local communities.

Distributed by APO Group on behalf of Africa Finance Corporation (AFC).


Continue Reading

Trending