Connect with us
Anglostratits

Business

Trends shaping global payment processing in 2023
Published

on

payment processing

There are several exciting trends emerging that will shape the way businesses and consumers process payments worldwide

NAIROBI, Kenya, March 29, 2023/APO Group/ — 

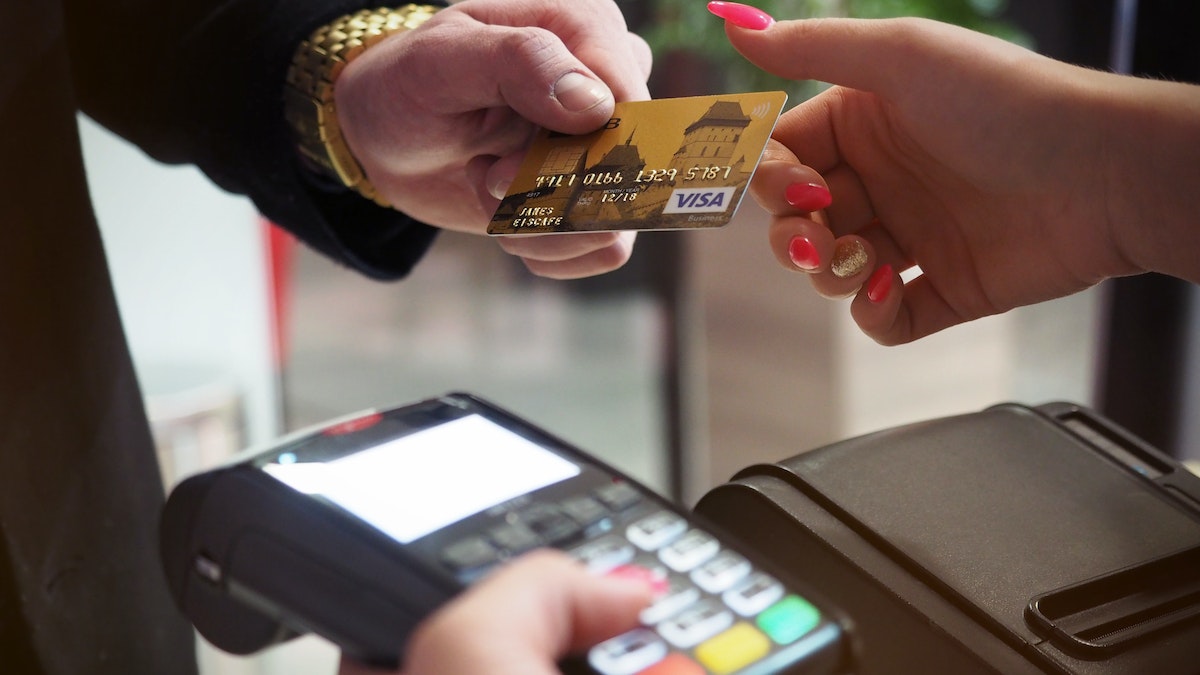
A global payment processing system is a network that enables financial institutions to process cross-border payments. It allows for currency exchange between banks and other financial institutions across borders. The system is used by businesses and individuals to make international payments, such as for goods and services purchased online.

Currently, this system is going through radical changes that are transforming how individuals and businesses send and receive money. Furthermore, there are several exciting trends emerging that will shape the way businesses and consumers process payments worldwide. From cryptocurrency and contactless transactions to artificial intelligence, these innovations are set to transform the industry as we know it.

What is a payment processor?

A payment processor is a financial institution that provides the technology and infrastructure necessary to facilitate global payment processing. Payment processors work with acquiring banks to provide merchants with the ability to accept credit card and debit card payments from customers around the world. Payment processors typically offer a suite of payment-related services, including merchant account management, payment gateway (https://apo-opa.info/42IetFv) and point-of-sale (POS) services, fraud prevention, and security solutions, and access to financing products. In addition, many payment processors offer value-added services such as loyalty programs, customer data analytics, and marketing assistance.

How big is the global payment industry?

A report by the Business Research Company suggests that the global payments market (https://apo-opa.info/3ZsekTH)  will record a growth of $612.04 billion in 2023 at a compound annual growth rate (CAGR) of 8.9%. Additionally, the report indicates that the global payments market will grow to $847.59 billion in 2027 at a (CAGR) of 8.5%. To begin with, new real-time payment platforms allow consumers and businesses to transfer money quickly, securely, and reliably across different banks and institutions. Again, there is an increased focus on security and data privacy (https://apo-opa.info/431uF4X) regarding payment processing. For instance, financial institutions are implementing more robust authentication processes to protect against fraud, as well as introducing new technologies such as biometrics and blockchain to strengthen security.

Trends reshaping payment processing in Africa

How we make and receive payments (https://apo-opa.info/3JVIxVx) is changing rapidly, and Africa is at the forefront. What’s more, new technologies and trends in global payment processing are reshaping the continent, making it easier for businesses to trade with each other and with the rest of the world. One of the most significant changes is the growth of mobile money. Equally important, more and more people in Africa are using their phones to send and receive payments, thanks to platforms like M-Pesa in Kenya and MTN Mobile Money in Ghana.

Additionally, payment gateways like Tingg (https://apo-opa.info/42IetFv) are reshaping how to send and receive money online in Africa.  This makes it easier for businesses to transact without going through a traditional bank. Another trend that’s reshaping Africa is the rise of blockchain technology. Blockchain allows for secure, fast, and cheap transactions without a middleman. This could potentially revolutionize African economies by making it easier to move money around without losing value through exchange rates or fees. These trends are just some ways that global payment processing is changing Africa. They’re making it easier for businesses to trade with each other and connect with the rest of the world.

Is cash declining?

The decline of cash has been a long time coming. For years, experts have predicted the death of cash as we know it, and while that hasn’t happened yet, the writing is on the wall. Moreover, several factors are driving this shift away from cash.

Perhaps most importantly, technological advances have made alternative payment methods more convenient and secure. At the same time, consumer behaviour is changing, with younger generations, in particular, preferring digital payments. Interestingly, a survey from McKinsey indicates that the domination of cash in Africa will be challenged soon as e-payments become increasingly popular (https://apo-opa.info/3JThrOT). Banks and nonbank organizations are trying to simplify domestic and international payments.

All of this is having a significant impact on the payments industry. Companies that process card payments are seeing rapid growth. Despite the digital revolution, adopting electronic payment methods in Africa is still not widespread. Although cash use is diminishing, it remains the primary means of transaction in African nations. This shift will likely continue in the years ahead as more consumers and businesses move away from cash.

Here are trends shaping global payment processing:

Mobile wallets

As mobile commerce continues to grow, so does the demand for mobile wallets. A mobile wallet is a digital wallet that allows users to make payments and access their funds using a mobile device. In 2023, it is estimated that there will be 1.31 billion proximity mobile payment transaction users (https://apo-opa.info/3ZpPcwV) worldwide, up from 950 million users in 2019.

The most popular type of mobile wallet is the smartphone wallet, which allows users to make payments and access their funds using their smartphone. Other mobile wallets include NFC wallets, which use Near Field Communication technology to enable contactless payments, and cloud-based wallets, which allow users to store their funds in the cloud and access them from any device. With more and more people using mobile devices to pay for goods and services, it is clear that mobile wallets are here to stay. As such, businesses must ensure they can accept payments via mobile wallets (https://apo-opa.info/3JVIxVx) to stay ahead of the competition.

Cryptocurrencies
The report indicates that the global payments market will grow to $847.59 billion in 2027 at a (CAGR) of 8.5%

Cryptocurrencies are digital or virtual tokens that use cryptography to secure their transactions and control the creation of new units. Besides that, Cryptocurrencies are often traded on decentralized exchanges and can also be used to purchase goods and services. Bitcoin remains the largest cryptocurrency by market capitalization, followed by Ethereum, Tether, Binance Coin, and Cardano.

Cryptocurrencies have seen significant growth in recent years, fueled by increased interest from retail and institutional investors. However, cryptocurrencies face scalability issues, regulatory uncertainty, and a lack of mainstream adoption. Nevertheless, the cryptocurrency industry is expected to grow in the coming years. 

As digital currencies continue to grow in popularity worldwide, Africa is emerging as a critical market for these new types of payments.

Global payment processing companies are noticing this trend and investing in African countries to tap into this growing market. Blockchain is a distributed ledger system that makes it difficult for anyone to hack or tamper with transactions. Reports indicate that In 2023, more than two dozen nations (https://apo-opa.info/3JXb7po) are expected to take a giant leap with the piloting of CBDCs. Several countries, such as Australia, Thailand, Brazil, India, South Korea, and Russia, already have plans to begin or further their pilot testing.

The growth of e-commerce

The e-commerce industry is expected to overgrow in the coming years. In 2023, the global e-commerce growth rate is expected to grow by 10.4%, bringing global e-commerce sales (https://apo-opa.info/40GSsoK) to $6.3 trillion.

Several factors will drive this growth:

1. The continued expansion of the internet and mobile devices.

2. The rise of social media and mobile commerce

3. The increasing popularity of online shopping.

In addition to this overall growth, there are a number of other trends that are shaping the global payment processing industry. These include the rise of alternative payment methods, the increasing use of mobile apps for payments (https://apo-opa.info/40JQDY8), and the growth of cross-border e-commerce. Alternative payment methods, such as digital wallets, are becoming increasingly popular as consumers seek more convenient and secure ways to pay for online purchases.

Biometric authentication

The need for secure authentication methods grows as the world becomes increasingly digitised. Biometric authentication, which uses physical or behavioural characteristics to verify identity, is one of the most promising technologies.

Several factors are driving the adoption of biometric authentication in the payments industry.

  1. Consumers are becoming more comfortable with using biometrics for authentication. This is due to the widespread use of smartphone fingerprint scanners and facial recognition technology.
  2. Biometric authentication offers higher security than traditional methods like passwords and PINs. It is much harder for criminals to steal someone’s identity or to spoof their credentials.
  3. Biometric authentication is becoming more affordable as the technology continues to mature. This is important for financial institutions that must balance security concerns with cost considerations.
  4. Some major payment processors are beginning to support biometric authentication. Some companies like Mastercard notably unveiled fingerprint and iris scanning (https://apo-opa.info/3zdzyKa) into their global network and have embraced biometric authentication.
  5. Government regulations are starting to catch up with the times. This is likely to spur even greater adoption of biometric authentication in the payments sector in the future.

Global payment processing and regulation

The impact of regulation on payment processing (https://apo-opa.info/3lS4Kvu) is far-reaching. Compliance with regulations such as the Payment Card Industry Data Security Standard (PCI DSS) is costly. In addition to the financial impact, compliance with these regulations imposes significant operational burdens on businesses. These requirements are challenging for small and medium-sized companies in particular.

Despite the challenges, businesses need to stay compliant with payment processing regulations. Non-compliance can lead to severe penalties, including fines, reputational damage, and loss of business.

Conclusion

Global payment processing will be pretty different in the future from what it is today. As technology advances, we will see more secure and efficient payment methods. Additionally, the need for transparency and faster transactions are pushing forward global payment processing trends such as blockchain and fintech. With all these changes coming our way in 2023, businesses should stay competitive (https://apo-opa.info/3KdHdxx) in an ever-changing marketplace.

Distributed by APO Group on behalf of Cellulant.
Business

PhotonPay Raises $40M Series C to Scale Its Stablecoin-Centric Financial OS
Published

on

Financial OS

Led by Blockchain Capital, the funding will accelerate the expansion of PhotonPay’s stablecoin-centric Financial OS, connecting stablecoin liquidity with global fiat networks to unlock digital assets for everyday corporate operations and cross-border settlement.
HONG KONG SAR – Media OutReach Newswire – 29 October 2026 – PhotonPay today announced the closing of a $40 million Series C funding round led by Blockchain Capital, with participation from new investor SBI Group and follow-on investments from existing investors IDG Capital, GL Ventures, and Lightspeed Faction. Blacksheep Technology acted as exclusive financial advisor to PhotonPay on the transaction.


The new capital will support the expansion of PhotonPay’s stablecoin-centric Financial Operating System (Financial OS), with investment focused on enhancing multi-asset wallet capabilities, expanding global card issuing, strengthening local clearing infrastructure in key markets, and developing an agent-ready financial execution layer.

As of August 2026, PhotonPay’s annualized transaction volume reached US$65 billion. The company has secured 34 payment and financial licenses and regulatory authorizations across the Americas, Europe and Asia, and serves over 200,000 business customers across more than 200 countries and territories.

As stablecoins move beyond crypto-native use cases into corporate treasury, settlement and commercial spending, PhotonPay sees the next phase of global finance not as a choice between stablecoins and fiat currencies, but as the convergence of both. Its Financial OS connects on-chain liquidity with the banking, clearing and card networks businesses rely on for everyday operations.

“Moving money across borders in seconds means little if it still takes days to put that capital to work,” said Lewison Chen, Founder and CEO of PhotonPay. “Stablecoins are accelerating global money movement, while local clearing and global card issuing connect that liquidity to local settlement and everyday business spending. Our Financial OS brings these capabilities together, making the underlying infrastructure far less visible to businesses, even as it becomes more essential than ever.”

“At the same time, business software is becoming increasingly autonomous,” Chen added. “AI is shifting financial workflows from people manually operating fragmented tools toward systems that understand business intent and coordinate execution across assets, accounts and financial rails. That creates the foundation for agentic commerce. Stablecoins change how money moves. AI changes how it gets put to work. But commerce is still what money is for.”

Moving Money Across Assets and Markets

PhotonPay’s Financial OS brings together multi-asset wallets, global money movement, foreign exchange, local clearing, and global card issuing through an integrated API-first architecture. This unified system gives businesses access to the financial capabilities they need to manage and deploy funds across markets.

Stablecoins sit at the core of this architecture. PhotonPay’s multi-asset wallet connects stablecoin liquidity with fiat balances, integrating asset conversion, foreign exchange, and local clearing into a single connected workflow. This enables businesses to move funds across supported on-chain and traditional financial networks, turning digital asset liquidity into purchasing power for local payments and everyday corporate spending.

Supporting this dual-rail infrastructure is PhotonPay’s established global financial network. Businesses can open local collection accounts in 17 key markets and receive funds in more than 60 currencies. On the payout side, the network supports over 100 payment routes across local clearing systems, bank transfers, and digital wallets, including payouts to 74 major local e-wallets. Approximately 97% of payout transactions reach recipients within hours or on the same day, with 68% arriving in real time.

Global card issuing extends these capabilities into programmable business spending. Through PhotonPay’s APIs, businesses and platforms can issue virtual and physical cards, configure granular spending controls, and embed card payments directly into their software and automated workflows. Over the past 12 months, PhotonPay issued 4.4 million cards, up 275% YoY.

Beyond its first-party payment solutions, PhotonPay makes its infrastructure available through embedded finance, enabling technology platforms to natively integrate global accounts, payments, and card issuing into their own products. The company now serves more than 100 enterprise and platform partners, extending the reach of its Financial OS into industry-specific workflows.

From Financial Intent to Agentic Commerce

As AI agents assume active operational roles, financial infrastructure must evolve beyond API access to enable programmable, policy-governed execution. It requires systems capable of translating high-level instructions into coordinated financial actions, with deterministic controls governing how those actions are executed.

In May 2026, PhotonPay and Mastercard completed a live agentic payment demonstration using a tokenized PhotonPay card, validating AI-initiated transactions across existing global card networks.

Building on this milestone, PhotonPay is developing standardized financial interfaces designed for developers and AI agents. With planned support for the Model Context Protocol (MCP), PhotonPay aims to make account information, balances, card functions, and payments accessible as composable financial primitives, allowing AI agents to securely retrieve context and initiate financial workflows within defined authorization boundaries.

To govern this agent-ready layer, PhotonPay is developing a policy-based execution framework designed to enforce programmable authorization rules, spending limits, and transaction-level controls. The framework is intended to enable AI agents to coordinate financial tasks across supported accounts and assets, while ensuring that execution remains subject to explicit, enforceable policies set by businesses.

PhotonPay is also advancing its AI-assisted risk review capabilities, designed to identify complex cases for human assessment. Together, these initiatives reflect a foundational principle of autonomous finance: AI may interpret intent and coordinate tasks, but financial execution must remain governed by verifiable authorization, deterministic controls, and auditable records.

“Connecting financial networks is only the beginning. The real breakthrough is abstracting that complexity behind a unified, programmable financial layer, so businesses and AI agents can move from intent to execution within clearly defined boundaries,” said Chen.

Simple on the Surface, Deep by Design

The promise of a Financial OS is simplicity: enabling businesses to manage assets, route money, and execute payments through a unified financial operating layer. Yet delivering that simplicity requires deep financial infrastructure beneath the surface.

While stablecoins accelerate borderless value transfer, turning that liquidity into local settlement, supplier payments, and corporate spending still depends on established banking relationships, domestic clearing rails, foreign exchange infrastructure, and global card networks. Each market brings its own regulatory and operational requirements.

For PhotonPay, building a Financial OS means abstracting these fragmented global networks into a programmable, interconnected financial system. The objective is not to eliminate financial complexity, but to manage it within the underlying infrastructure, so businesses can operate without having to navigate these systems themselves.

“AI can simplify how businesses interact with financial services, but it cannot replace the infrastructure required to deliver them,” said JP Pi, Chief Compliance Officer at PhotonPay. “Establishing local financial capabilities takes years of investment, institutional partnerships, and regulatory engagement. Software or AI models alone cannot replicate that depth. The simplicity businesses experience is the result of that heavy lifting, not a substitute for it.”

PhotonPay has engineered a financial foundation spanning both stablecoin and fiat rails, connecting multi-asset conversion with local clearing networks. Institutional partnerships with J.P. Morgan, Standard Chartered, and DBS, alongside connections to domestic payment systems such as Brazil’s Pix and Mexico’s SPEI, form the backbone of this network.

The new capital will enable PhotonPay to strengthen its local clearing and compliance infrastructure in existing markets while expanding into new jurisdictions, scaling the reach of its Financial OS across corporate spending, embedded finance, and agentic commerce.

“Businesses want one provider that can handle their payments across currencies and markets, whether they’re using bank transfers, stablecoins or cards. Lewison and his team have spent a decade building the banking relationships, licenses and local payment infrastructure to deliver that. We believe PhotonPay’s ability to bring these capabilities together gives it a strong advantage as businesses adopt stablecoins for everyday payments.” – BCAP,Yuanhan Li,Partner

“As stablecoins become increasingly integrated into global payment systems, bridging digital assets with traditional financial infrastructure will be essential to unlocking their real-world potential. PhotonPay’s established global payment network and its vision for a stablecoin-centric Financial OS align closely with SBI Group’s strategy to advance digital financial infrastructure and expand the practical adoption of digital assets. We look forward to supporting PhotonPay’s continued growth and exploring opportunities for strategic collaboration across the SBI Group ecosystem.” – Eiichiro So, CEO & Managing Director of SBI Ven Capital


Continue Reading

Business

Hainan economic, trade delegation visits Hong Kong for investment promotion, 2 cooperation memoranda signed
Published

on

Hong Kong

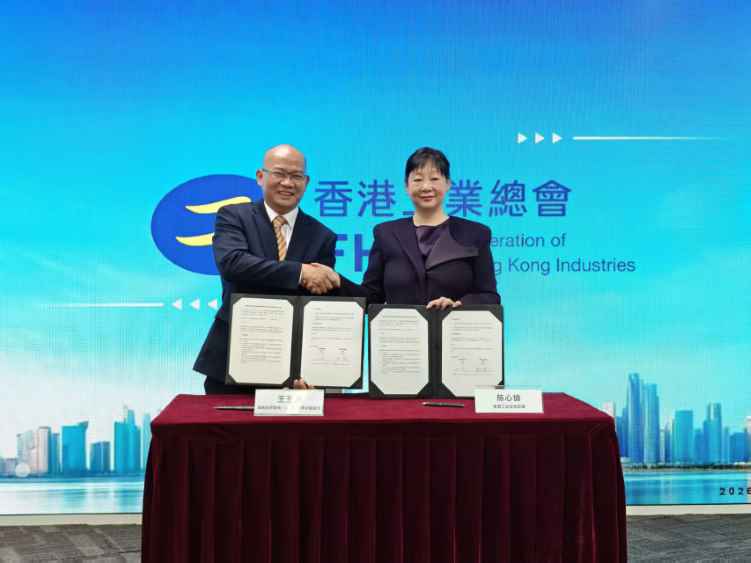
HONG KONG SAR – Media OutReach Newswire – 29 October 2026 – From October 19 to 20, an economic and trade delegation from Hainan Province paid a visit to Hong Kong. The delegation signed memoranda of cooperation respectively withThe Chinese Manufacturers’ Association of Hong Kong (CMA)and the Federation of Hong Kong Industries (FHKI) to advance pragmatic cross-border collaboration between Hainan and Hong Kong in trade and investment, manufacturing industrial chains and professional services.


During its stay in Hong Kong, the delegation visited the CCPIT Representative Office in Hong Kong. It held discussions with CMA and co-hosted the Hainan Free Trade Port (Hong Kong) Economic and Trade Cooperation Exchange Meeting with FHKI. The event showcased the policies, key industrial layout and investment opportunities of the Hainan Free Trade Port (FTP), and arranged one-on-one business matchmaking between Hainan and Hong Kong enterprises.

Wang Yuyuan, Vice President of the China Council for the Promotion of International Trade Hainan Sub-council (CCPIT Hainan) and China Chamber of International Commerce Hainan Chamber of Commerce, noted that since the official launch of island-wide special customs operations at the Hainan FTP on December 18, 2025, 174,000 new enterprises have been registered, representing a year-on-year surge of 95.9 percent. Newly established foreign-invested enterprises rose by 35.8 percent year on year. In the first half of this year, inbound and outbound tourist arrivals exceeded 70 million, up 28 percent year on year, with the number of visa-free entry countries expanding to 88. From January to August, the province’s total goods import and export volume hit 250 billion yuan, growing by 61.5 percent year on year. Hainan is rapidly emerging as a critical gateway connecting China with the rest of the world and a prime channel for two-way investment.

According to CCPIT Hainan, Hong Kong ranks as a major source of foreign investment for Hainan. In the first half of this year, Hainan registered 1,303 new foreign-invested enterprises, an increase of 38.62 percent year on year, with Hong Kong-funded enterprises accounting for the lion’s share. Hainan has issued offshore RMB local government bonds in Hong Kong for four consecutive years, with a cumulative issuance volume reaching 18 billion yuan.

CMA is one of Hong Kong’s most representative non-profit industrial and commercial bodies, with around 3,000 member enterprises. It has long provided members with business services including exhibitions, brand promotion, testing and certification. FHKI, one of Hong Kong’s four major chambers of commerce, has approximately 2,000 corporate members. It focuses on boosting the sustained development of Hong Kong industry and manufacturing through policy advocacy, business matchmaking, certification services and youth talent cultivation.

The two memoranda explicitly stipulate that the two sides will establish a regular liaison mechanism, build a long-term cooperation platform covering information sharing, business matchmaking, exhibition collaboration and professional services, and provide solid support for pragmatic business cooperation between Hainan and Hong Kong enterprises.

Source: China Council for the Promotion of International Trade Hainan Provincial Committee (CCPIT Hainan)


Continue Reading

Business

Africa gains governance momentum in the 2026 Chandler Good Government Index, but sustaining progress is the real test
Published

on

Africa

Across Africa, average scores improved in six of the seven CGGI pillars over the past year, with the strongest gains in Helping People Rise and Financial Stewardship

This signals that stronger government capabilities are beginning to translate into tangible improvements in people’s lives

KIGALI, Rwanda, October 29, 2026/APO Group/ –Africa was the second best-performing region for governance progress in the 2026 Chandler Good Government Index (CGGI), with 71% of the African countries assessed in both 2025 and 2026 achieving higher overall scores. However, the continent remains the lowest-scoring region overall, highlighting the challenge of translating improvement in government capabilities into better outcomes for citizens.


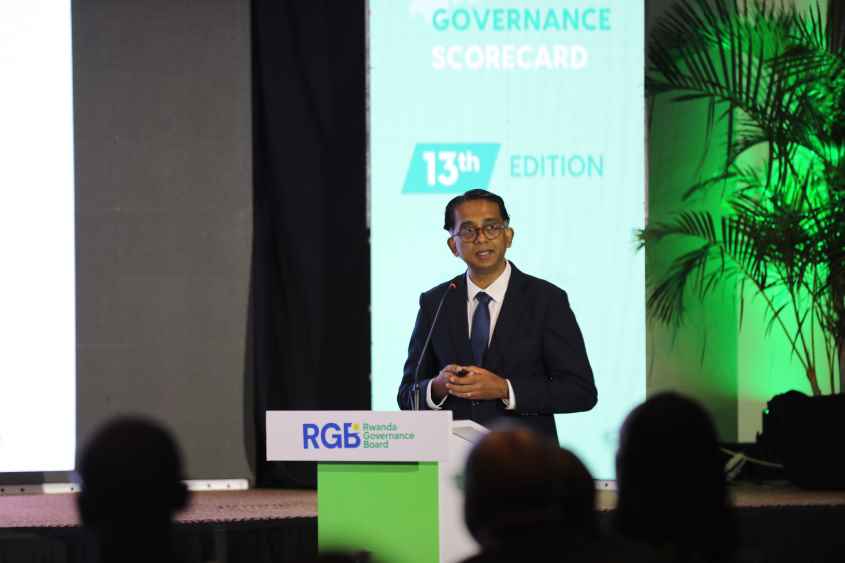
These findings were highlighted by the Chandler Governance Group (CGG) at a joint session with the Rwanda Governance Board (RGB) to launch the 13th edition of the Rwanda Governance Scorecard at the Kigali Serena Hotel on Thursday, 22 October 2026.

“This year, Africa’s strongest gains came in Financial Stewardship, followed by Helping People Rise, the CGGI’s outcomes pillar. This signals that stronger government capabilities are beginning to translate into tangible improvements in people’s lives, from access to quality education and healthcare to the public finances that fund them. The task now is to sustain that progress over the coming years,” says Dinesh Naidu, Director (Knowledge) at CGG.

Now in its sixth edition, the CGGI assesses government capabilities and effectiveness across 133 countries representing 94% of the world’s population, up from 120 countries in 2025. It measures 35 equally weighted indicators across seven pillars, providing governments with a framework to benchmark performance, identify gaps and learn from the experience of other countries.

Globally, the findings point to improving governance performance. Of the 120 countries assessed in both 2025 and 2026, 61% recorded higher scores, representing the highest annual share of countries improving since the Index launched in 2021. However, longer-term progress has been less consistent, with only 43% of the 104 countries tracked since 2021 recording an overall improvement.

Africa’s leading governments

Mauritius remains Africa’s highest-ranked country, placing 55th globally, followed by Rwanda (62nd), Botswana (70th), Morocco (79th) and Tanzania (80th). South Africa ranks sixth on the continent, in 85th place globally.

Rwanda features prominently in the discussion, ranking 11th globally for Leadership & Foresight and emerging as the highest-ranked low-income country in the Index. It ranks 61 places above where its income alone would predict. Across the Index, government capabilities track citizen outcomes more closely than national wealth does, suggesting that strengthening government capabilities matter in delivering better outcomes for citizens.

The joint session brings together the CGGI’s international benchmarks and the Rwanda Governance Scorecard’s assessment of governance in the Rwandan context, creating an opportunity to consider both global perspectives and country-specific priorities.

Progress across key governance pillars

Across Africa, average scores improved in six of the seven CGGI pillars over the past year, with the strongest gains in Helping People Rise and Financial Stewardship. These improvements point to progress in areas associated with public services, including healthcare and education, as well as the management of public finances.

Longer-term trends also highlight areas of progress. Between 2021 and 2026, nearly every African country assessed across the period improved its Data Capability score, with Morocco recording the largest gains. Ghana’s overall score improved in 2026, supported by stronger Financial Stewardship, while South Africa continues to show relative strength in Robust Laws & Policies, ranking 44th globally, and Attractive Marketplace, ranking 48th.

Despite these gains, the scale of the challenge remains clear. Africa’s regional average is still below its 2021 level, 23 of the 35 African countries in the 2026 Index rank outside the global top 100, and none is in the top 50. Seven African countries joined the Index this year: Chad, the Democratic Republic of Congo, Gambia, Guinea, Lesotho, Liberia and Togo.

“Rankings provide a useful starting point, but the broader value of the CGGI lies in helping governments understand where they are making progress and where further work is needed. Sustained improvements depend on the ability to strengthen institutions, manage resources responsibly and turn policy into meaningful outcomes for citizens,” says Naidu.

A tool for learning and improvement

The CGGI is designed as a practical diagnostic tool, helping governments identify gaps, track progress over time, and learn from peers facing similar constraints. The collaboration with the RGB brings international benchmarking together with locally grounded assessment.

“Every country faces its own governance challenges and is driven by varying priorities. Governments that are willing to take stock of the evidence and learn from peers to strengthen their institutions are well placed to achieve real improvements,” concludes Naidu.

Distributed by APO Group on behalf of Chandler Governance Group.


Continue Reading

Trending