Connect with us
Anglostratits

Business

The vital necessity of stopping oil production decline in Equatorial Guinea (by Leoncio Amada NZE NLANG)

Published

on

Equatorial Guinea

The country’s economy had previously been based on agriculture (largely coffee and cocoa) and the export of wood, until the dawn of the oil era

CAPE TOWN, South Africa, June 5, 2024/APO Group/ — 

By Leoncio Amada NZE NLANG, Executive President of the African Energy Chamber at CEMAC (http://www.EnergyChamber.org) and President of Apex Industries SA.

The discovery of oil in Equatorial Guinea in the mid-1990s constituted an undoubted turning point in the country’s history. The country’s economy had previously been based on agriculture (largely coffee and cocoa) and the export of wood, until the dawn of the oil era.

The influx of multinationals (oil majors) in Equatorial Guinea’s energy sector was due to the attractiveness of the fiscal terms and the prospectivity that the country offered for foreign direct investment (FDI) compared to other countries in the region; so much so that the nation occupied the third place among Sub-Saharan African oil-producing countries in for many years, behind Nigeria and Angola.

In effect, the discovery of oil put an end to the economic primacy of the agricultural sector and promoted the activities of the oil industry, which very soon began to attract foreign investment, allowing the enrichment and financial autonomy of the country. Oil activities led to the implementation of other related industries, thus allowing the development of other economic sectors.

This was made possible through the country’s infrastructure investments and social projects, which in turn had a new, reliable source of finance. Prior to that, traditional products like coffee, cocoa, and wood made the Equatoguinean economy largely dependent on the economic aid it received from the great powers and international financial institutions (including the World Bank, International Monetary Fund, etc.). But the discovery and exploitation of national oil deposits allowed the country to free itself from foreign economic influence. As such, Equatorial Guinea was able to undertake a huge public infrastructure investment program that covered the entire national territory and oversaw the construction of roads, bridges, ports, airports, public housing, power plants, urban districts, hospitals, university campuses, and new cities, as well as the creation of new ministry buildings and town halls. At the same time, oil wealth led to a growth in public savings and investment, reaching the record figure of 3,784 million euros in 2009.

To delve into the details, 534 million euros were invested in social infrastructure, 1,322 million euros in civil infrastructure, 997 million euros in productive investment, and 930 million euros in investment for public administration. Social investment grew by 116% in 2009, compared to an overall growth of 78%.

At the same time, the country’s oil boom has generated other complementary industries, including the construction of a liquefied natural gas (LNG) plant, a methanol plant, a liquid petroleum gas (LPG) plant, among others. These developments have given Equatorial Guinea business opportunities across the economy and have played an important role in the diversification of economic activities, promoting investment in diverse sectors of society and giving the state control over the country’s affairs.

The current situation:

After years of frenetic activity in the energy sector, the country today faces a sharp drop in oil production, which has put it at the bottom of the production rankings of OPEC countries, as can be seen in the following chart:

The reasons for this decrease in production are manifold, but foremost among them is a lack of new discoveries. The last discovery made was in 2007 at the Aseng site. If constant exploratory activity is not maintained, new deposits will not be discovered, and production levels will become volatile.

Natural gas has performed relatively better, despite being a more mature industry than oil. The gas era began with the discovery of the Alba field in 1984, with production coming online in 1991, ahead of oil production. The field still accounts for approximately 45% of the country’s daily production and is a large supplier of feed gas for its LNG (EG LNG) plant, which has been operational since 2007.

The aging of the Alba field has reduced the country’s total production, which peaked in 2013. But the decline has been gentler compared to the precipitous decline in oil production. However, growing domestic demand for gas is further reducing the country’s export capacity.

Equatorial Guinea is in a transitional phase of formulating projects and transformative strategies aimed at diversifying its economy

Hoping to safeguard Equatorial Guinea’s gas exports and attract international interest, the government has set out a vision of establishing the country as a regional gas liquefaction hub, receiving gas from domestic fields, as well as from neighboring Cameroon and Nigeria, to process it and export it to international markets. Such a plan would extend the lifespan of our EG LNG facility, which has been in difficulty since gas supplies from the Alba field began to decline. The project is progressing at a slow pace due to obstacles like negotiations with neighboring countries on developing cross-border oil and gas fields, securing potential supplies, and building connecting pipelines.

In 2019, the country launched a licensing round to auction 27 oil and gas blocks. In the end, three blocks were awarded to small players. In 2023, the government adopted an “open door” policy, whereby any company could express interest and enter into direct negotiations with the government. In 2023, a block was awarded to Panoro Energy as a result of these negotiations.

An open-door strategy is generally adopted when the success of a bidding round is in doubt. Indeed, bidding rounds are the superior and most widely used strategy for allocating oil and gas licenses. However, their success depends on several factors, some of which go beyond a country’s borders, such as prevailing oil and gas prices, while others are related to the country’s potential. When prices are high and the country’s oil and gas sector has promising prospects, competition among bidders tends to be strong, resulting in a windfall for the government. A failed bidding round that does not attract enough interest can damage a government’s negotiating position. To avoid such an outcome, governments use direct negotiations.

With aging assets, technically challenging small fields, and high exploitation costs, Equatorial Guinea is among the producers that are particularly exposed to the pressures of the energy transition. The government’s priority should be to extend the lifespan of its hydrocarbon sector, which represents around 85% of its GDP and just over 75% of its tax revenue, by remaining open to offers from smaller players. Governments usually prefer to work with large industry players that have a presence on their home soil, given that smaller players lack adequate financial and technical resources. It also makes it easier to negotiate new agreements. However, a change in the structure of the industry is expected as producing oil fields become more mature. The government should adopt measures that will help it adapt to this new phase.

To improve the attractiveness of investing in the country, the government announced several tax incentives, effective from early 2024, including reducing the corporate income tax rate from 35% to 25%. These measures could help but are not enough to offset the limited potential needed to generate the kind of rewards big players typically require. In fact, we believe that the measures adopted are too timid and that more forceful actions should be implemented in the short term to save and reactivate the sector that constitutes the backbone of the country’s economy.

There are no miracles in the oil industry, the only alternative is to apply the “Drill baby Drill” theory, which means drilling and drilling more exploratory wells to maintain or increase production levels. For this, certain incentive actions are necessary:

  1. Resolve the problem of the New BEAC Change Regulation. This highly bureaucratic and suffocating process has become the biggest obstacle and brake on foreign direct investment in Equatorial Guinea’s oil sector.
  2. Tax incentives.
  1. Exemption from payment of tax on assignments and transfers of assets in the oil sector for companies in the exploration and development phases. This measure would revive the appetite of independent companies to invest in the Equatoguinean oil sector and would revive exploratory activity in the country, motivating agile companies dedicated to exploration, thus favoring the farm-in and farm-out processes.
  2. Tax holidays on the payment of corporation tax (IS) for a negotiable period for new deepwater gas field contracts.
  3. Tax holidays on the payment of corporation tax (IS) for a negotiable period for new contracts for gas fields in shallow waters.
  4. Tax holidays on the payment of corporation tax (IS) for a negotiable period for deepwater crude oil field contracts.
  5. Tax holidays on the payment of corporation tax (IS) for a negotiable period for crude oil field contracts in shallow waters.
  6. Tax credits for operating companies that train Guineans and whose management positions are occupied by nationals for contracted companies as follows:
  7. Exemption from the payment of customs and parafiscal duties on the import of equipment and machinery intended for oil operations in favor of local companies operating in the sector.
  8. Tax credits for operating companies that partner with local companies for the establishment of research and development (R&D) centers in Equatorial Guinea.
  9. Although the issue of transfers abroad is not a tax issue, we appeal to the Ministry of Finance and Budgets to take action on the matter because this issue has become one of the greatest obstacles to foreign investment into Equatorial Guinea.
  1. Regulatory and legal stability. Investors seek stability in the regulations and laws that govern the oil sector. Constant changes in regulations can increase uncertainty and deter investment.
  2. Ease of acquiring permits and regulations. Simplify the processes of obtaining permits and licenses, streamline bureaucratic procedures, and reduce the regulatory burden for companies in the oil sector.
  3. Training and education. Promote training and specialized training programs in the oil sector to guarantee the availability of qualified labor.
  4. Legal security. Ensure a stable and predictable legal environment to attract long-term investments in the oil sector.
  5. Incentives for innovation and technology. Stimulate the adoption of innovative technologies in the oil industry through financial incentives or R&D support programs.
  6. Promotion of sustainability. Promote sustainable practices in oil extraction and production.

The role of Gepetrol.

With the transfer of MEGI’s assets to Gepetrol SA, the company has the opportunity and potential to become one of the most vibrant national oil companies (NOCs) in Sub-Saharan Africa. Its association with PETROFAC as a technical partner for the operation of the ZAFIRO field will not only allow the company to acquire the experience and technical and operational capacity necessary to effectively and efficiently manage Block B, but also to be an active partner in the operation of other oil fields to represent the interests of the state.

Equatorial Guinea is in a transitional phase of formulating projects and transformative strategies aimed at diversifying its economy, the results of which have yet to be felt, but which will considerably reduce its high dependence on the oil sector.

The fact remains that more than 80% of the country’s GDP comes from the hydrocarbon sector and this scenario is not expected to change in the medium term. It is for this reason that we invite all actors in the sector to adopt whatever measures are necessary to save “the goose that lays the golden eggs.”

Distributed by APO Group on behalf of African Energy Chamber
Business

Africa and Caribbean trade potential could reach $1.65 billion annually by 2030: International Trade Centre (ITC)-Afreximbank report

Published

on

Afreximbank

The report finds that around 80% of Africa’s annual goods export potential to the Caribbean remains untapped

ST. JOHN’S, Antigua and Barbuda, November 3, 2026/APO Group/ –Annual trade in goods and services between Africa and the Caribbean could reach up to $1.65 billion by 2030, excluding mineral fuels, according to a new report launched today by the International Trade Centre (ITC) and African Export-Import Bank (Afreximbank) (www.Afreximbank.com) on the sidelines of the Commonwealth Heads of Government Meeting in Antigua and Barbuda.


The report, Reshaping Africa-Caribbean Trade: Opportunities for Economic Transformation, (https://apo-opa.co/4eiz62u) finds that while Africa and the Caribbean share deep historical and cultural links, trade between the two regions continues to represent only a small share of each region’s overall trade, despite complementarities across sectors ranging from agribusiness and manufacturing to services and the creative economy.

A look at the numbers

The report finds that around 80% of Africa’s annual goods export potential to the Caribbean remains untapped, with are significant opportunities for export growth if trade and investment is actively promoted and facilitated.

Africa and the Caribbean must transform a shared history into shared prosperity

Caribbean export potential lies in the services sector, reaching $481 million. The report identifies business opportunities across several priority sectors, including processed food and animal feed, chemicals, minerals and metals, apparel and textiles, leather and footwear, tourism, transport services and creative industries.

These findings – and more – are based on trade and export potential analysis, detailed sector assessments and a survey of 1,175 businesses and business support organizations across Africa and the Caribbean.

Tapping into priority sectors

ITC Executive Director Pamela Coke-Hamilton (https://apo-opa.co/3WHHZMU), in launching the report, said: ‘At a time of major shifts in global trade, countries need to strengthen regional ties and invest in value addition, to build resilience. We know the major trade opportunities between Africa and the Caribbean – and now we can focus on helping businesses take advantage of those opportunities through better market intelligence, improved logistics and greater access to finance.’

Commenting on the report, Denys Denya, Senior Executive Vice President at Afreximbank, said: ‘Africa and the Caribbean must transform a shared history into shared prosperity. With our CARICOM office in Barbados, about $1 billion in approved transactions and a $5 billion regional financing commitment, Afreximbank is advancing this vision through financing, deposit mobilization under CENDEP, business links through the annual Afri-Caribbean Trade and Investment Forum, local-currency payments through CAPSS and creative-industry collaboration through CANEX. This report offers a practical roadmap to turn untapped potential into bankable opportunities across agribusiness, manufacturing, tourism and the creative economy. Through targeted financing, stronger transport and logistics links and strategic partnerships, we can build a Global Africa connected by heritage, trade, investment and shared opportunity.’

The report finds that businesses continue to face significant challenges, including high transport costs, limited direct shipping links, regulatory barriers, limited access to finance and difficulties in identifying trusted commercial partners. It highlights that future economic cooperation should extend beyond traditional trade in goods, including through joint investment ventures, digital services, creative industries and tourism. It also calls for targeted action to improve market intelligence and business matchmaking; expand access to trade finance and payment solutions; strengthen transport and logistics connectivity; support sector-specific value chain development; improve regulatory cooperation and market access; and foster stronger partnerships among business support organizations.

Read the full report HERE (https://apo-opa.co/4exHBH9)

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Business

MSGBC Oil, Gas & Power 2026 Investment Track to Spotlight New Capital Opportunities

Published

on

Etu Energias

A high-level ministerial roundtable, a project development clinic and matchmaking sessions are set to drive partnerships across the MSGBC region

DAKAR, Senegal, November 3, 2026/APO Group/ –The MSGBC Oil, Gas & Power 2026 conference and exhibition, taking place from December 1–3 in Dakar, will introduce a dedicated Investment Track designed to deepen capital engagement across West Africa’s energy landscape. Building on the region’s expanding upstream activity, infrastructure development and cross-border integration, the track will serve as a platform where governments, investors and project developers can align on investment pathways across the MSGBC basin.


At the core of the Investment Track will be the Ministerial Leadership & Global Capital Roundtable, where energy ministers will convene to examine how enhanced regional cooperation, regulatory alignment and coordinated infrastructure development can accelerate capital flows into the sector. The session is expected to focus on the policy and financing frameworks required to unlock large-scale projects, including investment codes such as Mauritania’s 2025 reform, as well as strengthening fiscal incentives and improving regulatory clarity to attract capital into the energy sector.

The Investment Track is designed to move beyond dialogue and into deal facilitation, bringing together decision-makers who can directly shape the next phase of energy investment

For the first time at the MSGBC Oil, Gas & Power event, the Project Development Clinic will introduce a more technical format. In this small-group advisory setting, project developers, government representatives and investors will engage directly on project challenges. The clinic aims to improve project structuring, address financing bottlenecks and identify practical solutions to accelerate development timelines and move projects closer to final investment decisions.

The Investment Track will also feature structured Business-to-Business Matchmaking sessions designed to connect stakeholders across the energy value chain. These targeted engagements will facilitate discussions between investors, operators, service companies and public-sector institutions, enabling participants to explore partnerships and co-investment opportunities.

Together, these sessions reflect the MSGBC region’s broader shift toward investment-led growth. In Senegal, this momentum is already visible through the partnership between state-owned agencies APIX and COS-PETROGAZ to improve the business environment for energy projects and streamline investment processes. With PETROSEN advancing development work on the Yakaar-Teranga gas project and targeting a final investment decision in December 2026, alongside new exploration opportunities emerging onshore, the Investment Track will provide a platform to connect the region’s resource potential with investors and project developers.

“The Investment Track is designed to move beyond dialogue and into deal facilitation, bringing together decision-makers who can directly shape the next phase of energy investment across the region. By creating a space for investors, project developers and public-sector stakeholders to engage directly, the track will help turn investment priorities into concrete partnerships and project opportunities,” states Sandra Jeque, Events and Project Director, Energy Capital & Power.

Explore opportunities, foster partnerships and stay at the forefront of the MSGBC region’s oil, gas and power sector. Visit www.MSGBCOilGasAndPower.com to secure your participation at the MSGBC Oil, Gas & Power 2026 conference. To sponsor or participate as a delegate, please contact sales@energycapitalpower.com.

Distributed by APO Group on behalf of Energy Capital & Power.


Continue Reading

Business

Afreximbank and partners bring together investors and industrialists in Benin to Accelerate local processing and investment in Special Economic Zones

Published

on

Afreximbank

Held under the theme “Investing in Local Processing and Industrialisation”, the forum brought together international investors, industrialists, buyers and development finance institutions to explore the vast opportunities for local processing and strategic partnerships offered by the GDIZ

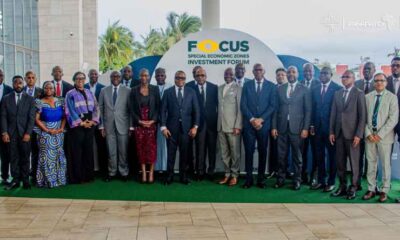
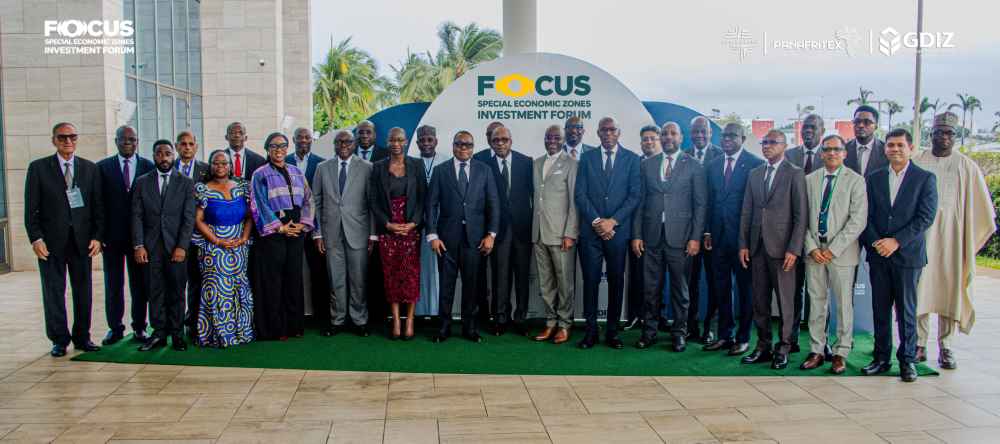
COTONOU, Benin, November 3, 2026/APO Group/ –African Export-Import Bank (Afreximbank) (www.Afreximbank.com), in partnership with the Société d’Investissement et de Promotion de l’Industrie (SIPI-BENIN S.A), the entity responsible for developing the Glo-Djigbé Industrial Zone (GDIZ), and Panafritex, hosted the Special Economic Zones Investment Forum (FocusSEZ 2026) on 21 and 22 October 2026 at the Sofitel Cotonou Marina Hotel and the GDIZ.


Held under the theme “Investing in Local Processing and Industrialisation”, the forum brought together international investors, industrialists, buyers and development finance institutions to explore the vast opportunities for local processing and strategic partnerships offered by the GDIZ.

Local processing at the heart of discussions

In his address, Mr Jean Arsene Yemina, Regional Director of Operations for Francophone West Africa at Afreximbank, speaking on behalf of Ms Kanayo Awani, Executive Vice President, Intra-African Trade and Export Development, Afreximbank, highlighted the role of financing and industrial partnerships in transforming Africa’s raw materials into finished products:

“Here in Benin, textiles have become the driving force behind this transformation. The Glo-Djigbé Industrial Zone was established through a partnership between the Government of Benin and ARISE IIP, with Afreximbank proud to have contributed to financing its development.

“Here in Benin, the textile industry has become the driving force behind this transformation. The Glo-Djigbé Industrial Zone was created through a partnership between the Government of Benin and ARISE IIP, and Afreximbank is proud to have helped finance its establishment. Today, the zone is home to West Africa’s first fully integrated cotton-to-garment manufacturing platform, operated by Benin Textile (BTEX). The entire value chain, from ginning and spinning to weaving and finished garments, is carried out on African soil by African hands. Before the creation of the GDIZ, less than 1% of Benin’s cotton was processed locally. In just three years, the zone has come to process approximately 40,000 metric tons of cotton—nearly 12% of national production—and to produce millions of “Made in Benin” garments for major international brands such as US Polo, Kiabi, and H&M.”

He also highlighted similar efforts underway at the GDIZ to develop local processing in the cashew, soybean and shea value chains.

Mr Létondji Beheton, Director General of SIPI-BENIN S.A., emphasised the need to strengthen value addition across the continent:

“Our ambition can no longer be limited to producing and exporting raw materials. We must go further by processing more of these resources on our continent, developing competitive industries, strengthening our value chains and retaining a greater share of the wealth generated from our natural resources.”

He added: “It is against this backdrop that the Glo-Djigbé Industrial Zone (GDIZ) was established, as the outcome of a public-private partnership between the Republic of Benin and ARISE Integrated Industrial Platforms (ARISE IIP). This integrated industrial platform embodies a shared commitment to making local processing a driver of economic growth, job creation and industrial development.

“By attracting manufacturing facilities and developing integrated value chains, the GDIZ is helping transform raw materials into higher-value-added products, strengthen Benin’s industrial capacity and enhance its competitiveness in regional and international markets. In doing so, it is contributing to the development of a more diversified economy that generates wealth and creates sustainable opportunities for the country.”

Africa has significant potential to strengthen its position in the global textile industry

Mr Arvind Mathur, CEO of PANAFRITEX, highlighted the role of ARISE IIP’s textile platform in developing an integrated textile industry in Africa, capable of transforming the continent’s cotton into finished, high-value-added products.

“Africa has significant potential to strengthen its position in the global textile industry. Realising this ambition will require the development of integrated industrial capacities that can transform cotton grown on the continent into higher-value-added finished products, while enhancing the competitiveness of the sector and expanding its access to international markets.

“At PANAFRITEX, we are contributing to this momentum by developing a model that brings together industrial processing, business development and the promotion of finished products. Our own brands, Obalé and SúSú, are part of this approach, connecting Africa’s manufacturing capabilities with consumer markets.

“The commissioning of our first industrial facilities at the GDIZ in Benin marks a major milestone in the rollout of this model. At the same time, the development of new facilities in Cameroon, Kenya, Nigeria, Ghana and Tanzania reflects our ambition to progressively expand our industrial footprint across the continent.

“Through this expansion, we aim to contribute to strengthening Africa’s textile value chains, creating skilled jobs and ensuring that a greater share of the value generated is retained locally.”

Financing, Market Access and Business Networking

Discussions focused on the development of a new generation of African industrial hubs, the cotton value chain, financing for the textile industry, as well as logistics and integrated supply chains. The programme also featured business-to-business (B2B) and business-to-government (B2G) meetings with targeted public-sector institutions, aimed at identifying investment opportunities, financing solutions and potential business partnerships.

Afreximbank presented the range of financial instruments and support facilities it offers investors and businesses to facilitate the establishment and expansion of their industrial operations. These include long-term financing and equipment financing, trade finance and working capital facilities, guarantees and risk-sharing mechanisms, as well as project preparation support and equity investment through the Fund for Export Development in Africa (FEDA).

The Bank also highlighted its Africa Buyers Programme, which connects African buyers with manufacturers operating in industrial zones across the continent. The initiative aims to complement access to finance with market opportunities for products manufactured in Africa.

A full day was dedicated to a visit to the GDIZ, during which participants toured its infrastructure and industrial facilities and took part in business matchmaking sessions bringing together investors, manufacturers and buyers. These activities were designed to facilitate the establishment of new manufacturing facilities and expand sourcing opportunities for “Made in Benin” products, particularly in agribusiness, textiles, plastics, packaging and industrial equipment.

Across sectors ranging from agro-processing and textiles to plastics, packaging and industrial equipment, the overarching objective is to accelerate the establishment of new production facilities and strengthen the supply of quality-certified “Made in Benin” products.

An Integrated Model for Advancing Industrial Sovereignty

Covering 1,640 hectares, the Glo-Djigbé Industrial Zone (GDIZ) is the result of a strategic partnership between the Republic of Benin and ARISE Integrated Industrial Platforms. Designed as a comprehensive, integrated ecosystem, it supports investors across the entire value chain, from securing supplies of locally sourced agricultural and mineral raw materials to industrial processing and the export of finished products, leveraging its direct connectivity to the country’s logistics infrastructure and the Port of Cotonou.

By hosting this international forum, Benin is once again demonstrating its ability to offer an attractive business environment, an enabling regulatory framework and world-class infrastructure to help build the future of African industry.

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Trending