Connect with us
Anglostratits

Energy

South Africa’s Cheaper Petrol Masks a Looming Gas Gap – and a Critical Investment Opportunity

Published

on

African Energy Chamber

A stronger rand and softer global fuel prices have pushed South African petrol to a four-year low – but without domestic gas development and LNG infrastructure, the country remains exposed to imports, currency swings and a fast-approaching supply shortfall

CAPE TOWN, South Africa, February 10, 2026/APO Group/ –South Africans are once again seeing relief at the pump, with the latest fuel price cuts delivering the cheapest petrol in roughly four years. The reductions – around 65 cents per liter for petrol and more than 50 cents for diesel – continue a downward trend that began earlier in 2026, when falling crude prices and currency strength combined to lower pump prices nationwide.

While the immediate benefits are tangible – cheaper transport, easing inflationary pressure and support for businesses – the underlying drivers reveal a more fragile reality. South Africa’s fuel costs remain shaped primarily by global oil markets and exchange-rate movements rather than domestic energy resilience.

Currency dynamics are particularly influential. The rand strengthened sharply through 2025, gaining nearly 13% against the U.S. dollar – its best annual performance in more than a decade – supported by improved fiscal sentiment and rising commodity prices. This momentum has continued into 2026 with periodic surges in precious-metal prices and global risk appetite. These shifts can lower refined-fuel import costs, but they also highlight South Africa’s continued dependence on external forces.

Structural weaknesses across the country’s fuel supply chain reinforce this reliance. Refining capacity has declined significantly, leaving only a handful of operational crude refineries and forcing South Africa to import roughly three-quarters of its liquid fuel needs. Strategic reserves remain limited to less than a month of supply. In this context, price relief at the pump reflects favorable global conditions rather than meaningful progress toward energy self-sufficiency.

Natural gas – affordable, reliable and abundant across Africa – can transform economies by powering industry, creating jobs and delivering the energy security our people deserve

The longer-term risk becomes clearer when viewed alongside South Africa’s evolving gas outlook. Without new domestic production or import capacity, South Africa is projected to face a ‘gas cliff’ as early as 2026. Existing Mozambican pipeline gas is depleting, while interim extensions from Sasol serve only as a temporary bridge to future LNG imports. Without new domestic production, import terminals or pipeline expansion, the country could confront tightening supply just as demand for flexible, lower-carbon power grows.

“Natural gas – affordable, reliable and abundant across Africa – can transform economies by powering industry, creating jobs and delivering the energy security our people deserve,” states NJ Ayuk, Executive Chairman of the African Energy Chamber. “But this transformation requires urgent investment in domestic production, LNG infrastructure and regional partnerships. South Africa has the resources and the market demand; what matters now is turning opportunity into action.”

Recognizing this urgency, the government is fast-tracking LNG import infrastructure, including a floating storage and regasification unit in Mozambique expected by mid-2026 and a planned LNG terminal at Richards Bay targeted for 2027, alongside efforts to unlock offshore gas in the Orange Basin. Today, roughly 90% of South Africa’s natural gas is still imported via a single pipeline from Mozambique – an exposure that underscores the need for diversification and domestic development.

The regional context reinforces the opportunity. Major LNG projects such as Mozambique’s $20 billion development – now moving forward again with production targeted before the end of the decade – signal growing momentum for African gas as a pillar of energy security and industrial growth. For South Africa, connecting to this wave through infrastructure, investment and regulatory clarity could reduce currency risk, stabilize fuel costs and support a more resilient transition pathway.

African Energy Week (AEW) 2026 in Cape Town is expected to spotlight precisely this: energy security, infrastructure investment and pragmatic transition pathways that balance hydrocarbons with emerging low-carbon systems. The event serves as a continental platform for LNG financing, infrastructure partnerships and upstream gas development capable of closing supply gaps and accelerating practical energy transitions.

Fuel price volatility now exposes South Africa’s structural energy weaknesses, underscoring why short-term relief cannot substitute for long-term strategy. Cheaper petrol may ease pressure today, but without decisive progress on domestic gas production and LNG infrastructure, the country risks repeating the same cycle – relief when currencies strengthen, strain when they weaken and continued vulnerability in between.

Distributed by APO Group on behalf of African Energy Chamber.

Business

Ghana Targets End to Liquid Fuel Purchases for Power as Gas Supply Expands

Published

on

GECF

Ghana, Senegal and the GECF outlined how African producers can grow domestic gas use alongside exports at the GECF-AEC Strategic Forum

CAPE TOWN, South Africa, October 14, 2026/APO Group/ –Ghana expects to stop procuring liquid fuels for power generation next year, John Jinapor, Minister for Energy and Green Transition, said during a Gas Exporting Countries Forum (GECF)-hosted strategic session at African Energy Week (AEW) 2026 in Cape Town. Ghana has already cut its liquid fuel purchases for electricity from eight cargoes to two, he said, as domestic gas and imports from Nigeria replace diesel and heavy fuel oil in thermal plants.


Ghana’s gas policy prioritizes domestic processing, with gas directed first to power generation and then to industry, Jinapor said. The switch from liquid fuels saved Ghana about $500 million in a single year through import substitution, at a time when electricity demand is growing about 10% annually. Nigeria supplies Ghana through the West African Gas Pipeline, and he said Ghana expects to double those volumes under its current agreements. Ghana is also building a 278 km pipeline to link its main power centers, and is using a levy on pump fuel to fund LPG adoption, targeting 50% penetration within three years.

We are a gas continent before an oil continent

Senegal, which began exporting LNG in 2025, is working to balance exports with supply to its own economy. El Hadji Abdourahmane Diouf, Minister of Energy and Petroleum, said companies often prioritize export markets, leaving governments to secure domestic supply. Senegal is targeting domestic gas supply of around 150 million standard cubic feet per day by 2030, delivered through a national gas network to power plants across the country. Diouf said the network’s pipeline, which has faced delays, is expected within nine months.

Philip Mshelbila, Secretary General of the Gas Exporting Countries Forum (GECF), called the choice between exports and domestic use “a false choice.” In his address, he said: “Exports mobilize capital, revenue and investment confidence. Domestic utilization is the development multiplier.” The GECF’s Global Gas Outlook projects African gas demand will more than double, from 175 billion cubic meters in 2024 to about 374 billion cubic meters by 2055.

Panel moderator Oliver Onyekweli, Partner at McKinsey & Company, noted that only around 3% of gas commercialized in Africa is traded within the continent. Mshelbila said regional cooperation, gas storage and cross-border infrastructure will determine how resilient African markets are to future supply disruptions. He cited the Senegal-Mauritania Greater Tortue Ahmeyim project as a model.

NJ Ayuk, Executive Chairman of the African Energy Chamber, described gas as a “Swiss knife” for African development, with uses spanning power generation, petrochemicals and fertilizers. “We are a gas continent before an oil continent,” he asserted.

Ghana’s gas master plan, currently under review, sets a 15-year blueprint for the country’s gas infrastructure and budgeting.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Business

Africa Energy Bank to Begin Financing Gas Projects in Early 2027, African Petroleum Producers Organization (APPO) Says

Published

on

African Energy Chamber

APPO’s new bank will prioritize regional corridors as GECF forum panelists flag a gap in domestic gas financing

CAPE TOWN, South Africa, October 14, 2026/APO Group/ –The Africa Energy Bank (AEB) will become operational within weeks and begin financing projects at the start of 2027, Farid Ghezali, Secretary General of the African Petroleum Producers Organization (APPO), said during the technical panel of the GECF-AEC Strategic Forum at African Energy Week (AEW) 2026 in Cape Town. The bank, launched by APPO and Afreximbank, will use a corridor approach, prioritizing projects that deliver regional economic development across four pillars: export infrastructure, domestic infrastructure, clean cooking and power.


Ghezali said exports and domestic supply should not compete. “I come from a country where you cannot export any drop of gas if the domestic demand is not satisfied,” he said. APPO and the Gas Exporting Countries Forum (GECF) signed an agreement earlier this year to work jointly on gas corridors, and plan to harmonize transit tariffs and gas contracts across member states.

I come from a country where you cannot export any drop of gas if the domestic demand is not satisfied

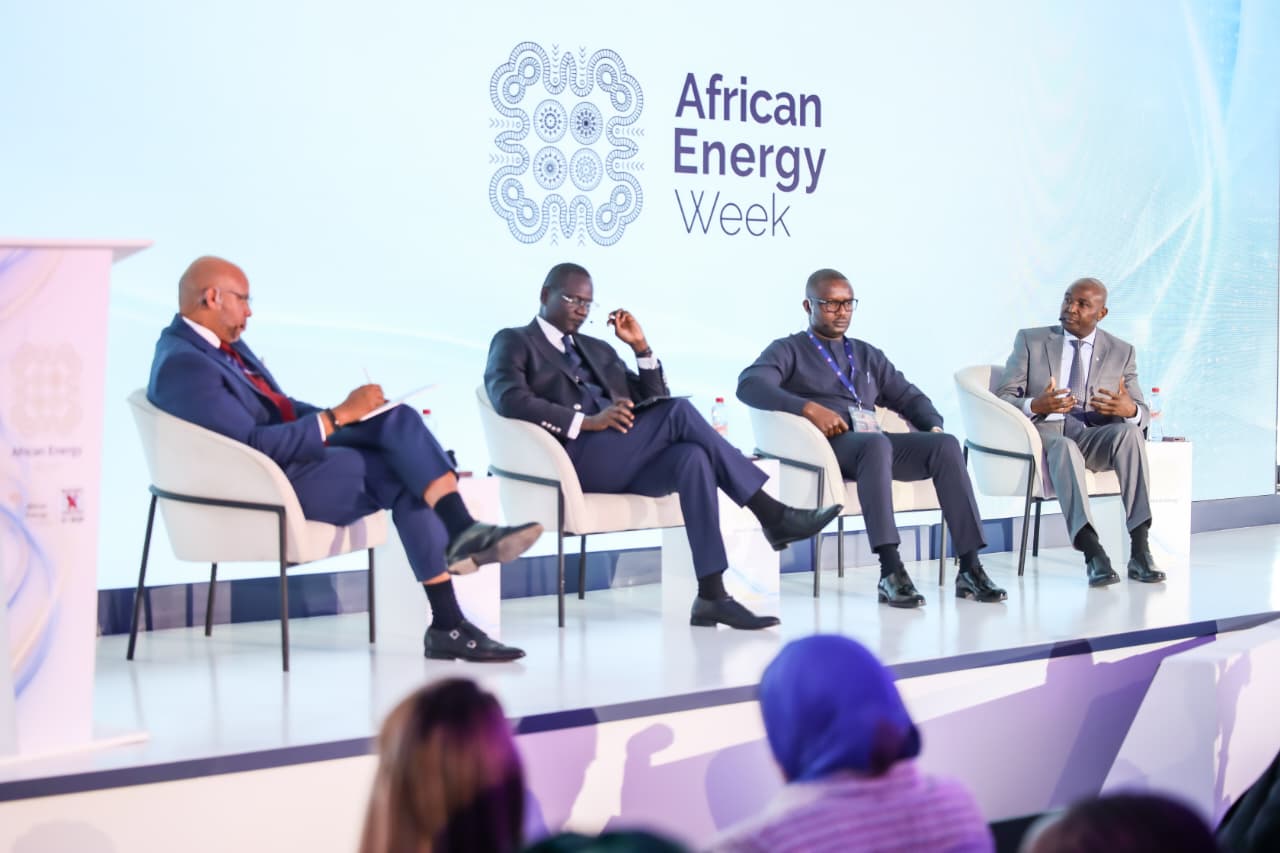
The panel focused on why domestic gas markets remain underdeveloped. Rashid Ali Abdallah, Executive Director of the African Energy Commission (AFREC), said recent investment has gone largely into export terminals while regional pipelines struggle to attract funding. He called for regional financing frameworks for cross-border infrastructure, and for joint planning of gas pipelines and power transmission.

In South Africa, industrial consumers face the loss of natural gas supply within about 18 months, with only a short-term coal supply bridge beyond that, said Jaco Human, Executive Officer of the Industrial Gas Users Association of Southern Africa (IGUA-SA). The gas aggregation company was formed to pool demand, share risk and underwrite new infrastructure across the region. Human said a proposed pipeline linking the Orange Basin to Western Cape and inland markets would need around 200 petajoules of annual demand. “We have much more demand than that, so the problem is not an economic one,” he said. “Rather, it is a coordination problem.”

Abubakar Abbas, Senior Energy Forecast Analyst at the GECF, said Africa will require at least $1 trillion over the next 30 years to develop its gas resources. Per capita energy consumption on the continent is about 25 gigajoules a year, well below the global average. Abderrezak Benyoucef, Head of Energy Studies at OPEC, said OPEC expects gas to rise from 17% to 23% of Africa’s energy mix by 2050. Electricity generation is projected to grow from under 1,000 TWh to about 2,700 TWh, with half of it from gas.

The AEB is headquartered in Abuja, where Nigeria handed over the bank’s offices to APPO and Afreximbank in February.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Energy

Nigeria Mining Week puts investment, bankable projects and local value creation in focus

Published

on

Nigeria Mining Week enters its final day after two days of frank discussion about what it will take to turn Nigeria’s mineral wealth into viable projects, stronger local industries and long-term investment

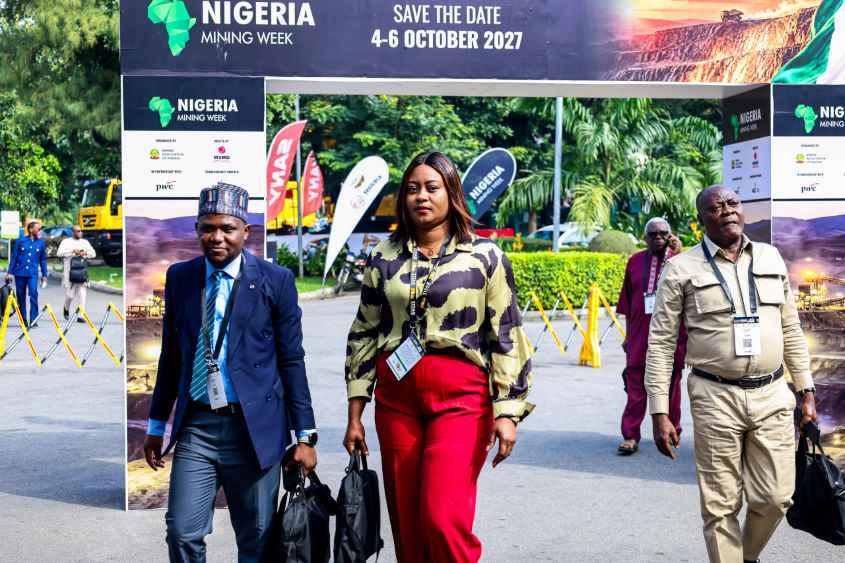
ABUJA, Nigeria, October 14, 2026/APO Group/ –Nigeria Mining Week (https://NigeriaMiningWeek.com) enters its final day today after two days of frank discussion about what it will take to turn Nigeria’s mineral wealth into viable mining projects, stronger local industries and long-term investment.

Taking place from 12 to 14 October at the Abuja Continental Hotel under the theme “Unlocking Investment and Growth through Partnerships,” this year’s event has brought government, mining companies, investors, financiers and industry bodies together around some of the sector’s most pressing issues.


The message coming through strongly is that mineral potential alone is not enough. Investors need reliable geological data, clear and consistent regulation, secure operating environments, access to finance and infrastructure that can support projects from exploration through to production.

At Tuesday’s official opening, Cyril Azobu, Partner and Mining Industry Leader at PwC Nigeria, spoke about the need to develop projects that can attract serious investment and create more value within Nigeria, rather than relying on the export of unprocessed minerals.

That point was reinforced by Austin Menegbo, Country Manager of Segilola Resources Operating Limited, who brought the perspective of an operating mine to the discussion. Segilola reported production of 91,910 ounces of gold in 2025, with Nigerians making up 99% of its workforce.

Menegbo also highlighted some of the practical challenges facing mining companies, including overlapping approvals, infrastructure constraints, security and access to finance.

Oba Ayandele Ayanleke, National President of the Miners Association of Nigeria, called for greater regulatory certainty and closer cooperation between government and industry.

Data was another recurring theme. Professor Olusegun Ige, Director-General of the Nigerian Geological Survey Agency, stressed the importance of strengthening the geological information available to investors and improving the flow of exploration data into Nigeria’s national geological knowledge base.

International cooperation also featured prominently.

Anna Westerholm, Sweden’s Ambassador to Nigeria, highlighted opportunities for cooperation in technology, expertise and business partnerships. She also pointed to the growing importance of traceability and responsible production as international buyers pay closer attention to where minerals come from and how they are produced.

These conversations built on Monday’s pre-conference program, where smaller roundtable discussions tackled four practical areas: geological data and exploration, financing for junior miners, compliance and enforcement, and power and infrastructure.

The Women in Extractive Industries Forum added another important dimension, looking at how more women can move into technical, operational and leadership positions, as well as the role women can play in strengthening ESG, community engagement and responsible mining.

One day left, and some of the biggest conversations are still to come

Today’s program turns attention to the value chains and infrastructure that could shape the next phase of Nigeria’s mining industry.

The morning begins with Nigeria’s gemstone value chain, looking at how the country can build stronger links between miners, cutters, polishers, jewelry manufacturers and international buyers.

That is followed by a discussion on policy, regulation and governance, including the practical steps needed to create a clearer and more competitive environment for mining investment.

Community relationships will also come into focus during From Consent to Social Licence, with the conversation moving beyond compliance to the question of how mining companies build trust and create lasting value in host communities.

In the afternoon, Power to Mines and Logistics for Industrialization will tackle one of the industry’s biggest practical questions: how to provide the power, transport and logistics needed to turn mineral discoveries into commercially viable operations.

Then, from 15:00, attention shifts to two important Nigerian mineral value chains.

GOLD FORUM The Gold Forum will look at how production can connect more effectively with refining, responsible sourcing, formal trading, finance and international markets.


STEEL FORUM At the same time, the Steel Forum will examine iron ore supply, beneficiation, power, logistics and the future of Ajaokuta Steel Mill, with a wider discussion about the role mining can play in Nigeria’s industrial and manufacturing ambitions.


After two days of discussion about what needs to change, the final day gets closer to the question that matters most: how does Nigeria turn its mineral resources into functioning industries, investable projects and jobs?

For investors, operators, policymakers and businesses looking for a place in that story, there is still one day left to join the conversation at Nigeria Mining Week.

Distributed by APO Group on behalf of Nigeria Mining Week.


Continue Reading

Trending