Connect with us
Anglostratits

Energy

Natural Gas and Liquefied Natural Gas (LNG): Building a Bridge to African Energy Security and Prosperity (By NJ Ayuk)

Published

on

African Energy Chamber

By expanding LNG and domestic uses, nations can drive growth, cut emissions, and assert their energy independence

JOHANNESBURG, South Africa, December 23, 2025/APO Group/ —By NJ Ayuk, Executive Chairman, African Energy Chamber (https://EnergyChamber.org).

Africa is awakening to the power of its natural gas reserves, recognizing that among its many resources, natural gas offers a reliable and expedient track to economic growth and energy independence.

In our “State of African Energy: 2026 Outlook Report,” the African Energy Chamber (AEC) details how the energy matrices of several gas-producing nations are pivoting from holding gas back as mainly an export product to building gas-centric domestic markets.

We regard this crossover not as some hopeful economic gamble, but as an essential step that all gas-producing nations on the continent must take if Africa is to benefit fully from its fossil fuel reserves and build up true self-reliance — without apology — just as the developed nations of the world did when it was their time.

As our report makes clear, domestic gas demand in Africa is ready to surge in the coming years, driven primarily by rising power needs. At this pivotal juncture, several African nations serve as prime case studies on how forward-looking investments in gas production can power whole industries, create new jobs, and stabilize grids in places where such improvements are desperately needed. Additionally, their stories exemplify how, amid a global energy transition, natural gas will serve as a bridge fuel that will power Africa into its own sustainable future.

Angola’s Gas Renaissance: From Exports to Domestic Growth

In Angola, the oil and gas sector has seen its economic footprint shrink over the last decade amid declining output. Regardless, Angolan policymakers are well aware of the vast untapped value in the country’s gas reserves, and recent industry moves reflect a commitment to realizing their potential.

Angola’s journey into the global gas arena began with the construction of the Angola LNG liquefied natural gas (LNG) facility in 2008. This transformed associated gas (gas found in wells alongside crude oil), which was previously flared or reinjected, into exportable LNG — slashing upstream emissions in the process.

The raw natural gas (or feedstock) that is processed and liquefied to produce LNG initially came from key offshore blocks operated by ExxonMobil, Total, and Eni/BP, and was augmented later with gas from other blocks operated by Eni/BP and Chevron. Though half of the associated gas produced in Angola today is still reinjected into wells to maintain pressure and enhance oil recovery, recent progress — like the December 2024 achievement of first gas from the Sanha Lean Gas project — aims to boost supply volumes to the Angola LNG plant.

Angola has also begun to pivot toward non-associated gas fields in areas like the Lower Congo basin. The New Gas Consortium, a joint venture headed up by Azule Energy, is targeting numerous developments on multiple blocks that are expected to ramp up LNG capacity by 2026.

Post 2010 exploration in the southern Kwanza Basin offshore led to giant non-associated gas discoveries. While exciting, we at AEC are frustrated that those finds remain stranded due to a lack of gas export infrastructure in the area and the high cost and difficulty of deepwater drilling where they’re located.

The Kaminho project, which targets condensate-rich pre-salt discoveries in the Cameia and Golfinho fields, is the first operation under development in block 20 of the Kwanza basin. Condensate/light oil recovery is the current priority at the site, and the extent of development will depend on the completion of the Kaminho floating production, storage, and offloading (FPSO) unit expected in 2028. As our report speculates, the possibility of a network between Kaminho and the appraisal programs at the Lontra, Zalophus, and Bicuar fields in the same region could encourage development of gas transport infrastructure leading to Angola LNG at Soyo or central Angola.

The Angolan government seeks to expand its pipeline network, which may involve gas evacuation from Cameia-Golfinho to the coastal point of Caboledo and an onshore pipeline to Luanda and Soyo to satisfy local demand, but project costs and the necessary transportation tariffs are holding up investment. Funding for such developments could potentially come from upstream firms or international banks with added tax breaks to make them viable.

In the long term, gas blowdown operations at maturing oil fields in the Congo Fan could also supply Angola LNG, leveraging existing midstream infrastructure for extended production into the 2030s.

Domestically, Angola is allocating more gas to power generation, with supplies feeding the 750-megawatt (MW) Soyo combined-cycle gas turbine (CCGT) plant that has been balancing hydropower fluctuations since its start in 2018. But ambitions extend further: the Angola Gas Master Plan calls for fertilizer (ammonia) and methanol facilities by 2030, which would spur a massive increase in gas demand. The proposed ammonia plant, set for construction in 2025 and operations by 2027, could demand up to 80 million cubic feet per day (MMcf/d) by 2035. Power expansions and conversions from oil will also drive demand, while opportunities in petrochemicals, direct gas exports, or mining electrification could diversify use.

Africa deserves to thrive on the wealth of its own resources, and the developments outlined in our latest report prove that outcome is possible

By integrating LNG exports with local needs, Angola exemplifies how Africa can benefit from its resources while encouraging economic diversification and reducing dependence on imports.

Emerging LNG Exporters: Mauritania and Senegal’s Shared Success

Shifting north, Mauritania and Senegal have stepped into the LNG scene. They became exporters in 2025 with the Greater Tortue Ahmeyim (GTA) project, a shared deepwater startup. This cross-border venture, featuring subsea infrastructure, an FPSO, and a floating LNG (FLNG) unit, has already generated approximately 3,000 local jobs and engaged roughly 300 domestic companies.

In 2015, developers overcame unitization hurdles through discussion, arriving at equitable terms, including domestic gas obligations. The project reached a final investment decision (FID) and agreed to a FLNG model, inspired by proven tanker conversions that have kept costs competitive on previous projects despite deepwater challenges.

Future expansions could double output through low-cost vessel upgrades; however, our report cautions that market oversupply risks and pledges from Senegal’s new nationalist government to audit contracts may introduce additional risks.

Domestically, each country claims about 35 million standard cubic feet per day (MMscf/d) from the project — with delivery of Senegal’s portion going to the Saint-Louis CCGT for power generation expected in 2026. Infrastructure initiatives, like gas networks and a proposed 366 MW power plant in Cap de Biches, aim to electrify close to 500,000 homes. Beyond power, other uses in petrochemicals and fertilizers could broaden the economic impacts, demonstrating how LNG can facilitate other industries.

Country-level initiatives like these align with the broader continental trends also outlined in our 2026 Outlook report.

Harnessing Regional Power Pools for Continental Integration

As of 2025, Africa’s gross natural gas production is set to hit 331 billion cubic meters (bcm), led by the major producers: Algeria, Nigeria, and Egypt. Natural gas already powers 40% of the continent’s electricity, with North Africa’s 32% share doing most of the heavy lifting.

By 2050, gas-fired capacity could swell by more than 77 GW, yet its share of the total energy mix should stay around 40%. This demonstrates how gas can fill in as a transitional fuel during the expected growth in renewables, as well as its flexibility in supporting solar and wind during downtime.

Numerous nations are phasing out coal and oil — implementing gas-to-power in their national strategies while looking toward LNG imports or domestic sources. For instance, Nigeria has made gas-to-power a centerpiece of its master plan. South Africa’s plans emphasize converting gas to electricity during its coal retirement. Senegal aims to have 3 GW of gas-to-power in place by 2050, and Ghana and Tanzania have similar gas-powered ambitions.

Though challenges like infrastructure gaps, import vulnerabilities, and environmental concerns will surely arise, we at the AEC are confident that targeted investments can overcome them.

These efforts are amplified by regional power pools — collaborations that allow neighboring countries to connect to each other’s power grids. Five pools cover the continent:

  1. Southern African Power Pool (SAPP) leads as the most mature and serves as a model for strong interconnections and competitive trading.
  2. West African Power Pool (WAPP) has advanced cross-border links but grapples with regulatory and financial issues.
  3. Eastern Africa Power Pool (EAPP) is also making progress on interconnections despite political hurdles.
  4. Central African Power Pool (CAPP) is the furthest behind due to instability, limited infrastructure, and a lack of investment.
  5. North African Power Pool (NAPP) has arguably the most advanced infrastructure but limited trade as it has more of a focus on integration with European markets.


The African Single Electricity Market, an effort to combine these five pools into a single continental power market, has sights on full integration by 2040. Although barriers like physical distances and technological and political compatibility issues are expected, finding ways around these barriers could further unlock the potential of gas by linking exporters to importers and boosting access and cooperation.

“The State of African Energy” spells it out: Natural gas is a catalyst for African prosperity, not merely a commodity on the market. By expanding LNG and domestic uses, nations can drive growth, cut emissions, and assert their energy independence. As a transitional fuel, it offers a comfortable route to an eventual conversion to renewables and can ensure that no African is left in the dark during the process.

Africa deserves to thrive on the wealth of its own resources, and the developments outlined in our latest report prove that outcome is possible.

“The State of African Energy: 2026 Outlook Report” is available for download. Visit https://apo-opa.co/3YH75ct to request your copy.
Distributed by APO Group on behalf of African Energy Chamber.

Business

SLB commissions new fluids systems plant in Pemba to support Mozambique’s offshore energy development

Published

on

Mozambique

New facility expands in-country drilling and completion fluids capability, advancing the next phase of SLB’s growth in Mozambique

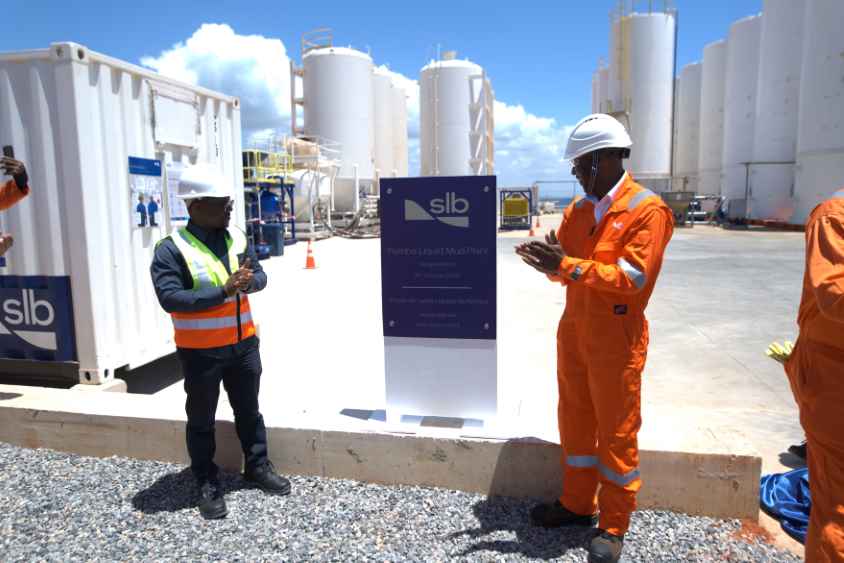
PEMBA, Mozambique, October 9, 2026/APO Group/ –SLB (NYSE: SLB) (www.SLB.com) announced the opening of a new fluids systems plant in Pemba, Mozambique. The new facility strengthens in-country capacity to prepare, store and deliver drilling and completion fluids for offshore operations, reinforcing the infrastructure needed as Mozambique’s offshore activity grows and its role as a strategic energy hub for East Africa continues to expand.

The commissioning of the plant, also known as a liquid mud plant, coincides with SLB marking 70 years of operations in Mozambique. It reflects the company’s long-term commitment to investing in people, infrastructure and capability that support the country’s long-term offshore energy development plans.


With an initial storage capacity of 21,000 barrels, the liquid mud plant provides a scalable platform for future growth, supporting multiple customers and rising offshore activity while improving logistics and enhancing operational flexibility.

As SLB marks 70 years in Mozambique, this investment reflects our confidence in the country’s future and our commitment to supporting its energy ambitions

“As SLB marks 70 years in Mozambique, this investment reflects our confidence in the country’s future and our commitment to supporting its energy ambitions,” said Miguel Baptista, Central, East and Southern Africa, Managing Director, SLB. The new liquid mud plant strengthens local energy infrastructure, expands opportunities for local content development, and enhances our ability to support customers as they deliver some of Africa’s most significant offshore energy resources.”

The liquid mud plant project was delivered with strong local participation and that momentum is expected to continue into operations. During project delivery, more than 100 jobs were created in Pemba with nationals representing 80% of the workforce, reflecting a focus on building local capability.

The project was delivered with a strong focus on safety, operational integrity, and quality, achieving more than 67,000 hours worked without a recordable safety incident.

This key infrastructure strengthens SLB’s ability to support consistent service quality and enhance supply chain readiness for increasing offshore activity across Mozambique, supporting customers execute safely and efficiently while developing local skills and expertise.

Key Points:

  • SLB has commissioned a new fluids system plant in Pemba, expanding in-country drilling and completion fluids capability for offshore operations.
  • With an initial storage capacity of 21,000 barrels, the facility provides a scalable platform to support growing offshore activity in Mozambique.
  • The investment marks the next phase of SLB’s growth in Mozambique, strengthening local capability and supporting long-term offshore energy development.

Distributed by APO Group on behalf of SLB.


Continue Reading

Business

South African Energy Storage Association (SAESA) welcomes 4,600 MW battery storage prioritisation and calls for integrated energy planning

Published

on

Battery energy storage systems (BESS) are becoming critical system infrastructure, supporting flexibility, reducing avoidable curtailment, shifting energy into periods of demand and strengthening security of supply

JOHANNESBURG, South Africa, October 9, 2026/APO Group/ –The South African Energy Storage Association (SAESA) (www.SAESA.org.za) welcomes the prioritisation of 4,600 MW of battery energy storage under the first Integrated Resource Plan (IRP) 2025 Section 34 determination.


The timing is significant. Recent Integrated Energy Plan (IEP) modelling and assumptions discussions highlighted a fundamental shift that South Africa’s energy planning now needs to capture: we cannot plan the future power system by counting megawatts of generation alone.

We must plan for when energy is available, where it is available, how it moves through a constrained grid and how it is stored and dispatched when the system needs it most.

The announcement reinforces that shift. Battery energy storage systems (BESS) are becoming critical system infrastructure, supporting flexibility, reducing avoidable curtailment, shifting energy into periods of demand and strengthening security of supply.

For SAESA, the message for the IEP is clear: storage, flexibility and system services must be modelled as integral components of South Africa’s future electricity architecture, with their contribution considered from the outset of generation planning.

“The IEP must plan the power system we are becoming, not simply model the power system we have inherited,” says SAESA.

The IEP must plan the power system we are becoming, not simply model the power system we have inherited

Partnership with C&I Energy + Storage Summit

SAESA is an association partner of the C&I Energy + Storage Summit, created by VUKA Group, taking place on 28–29 October 2026 at The Maslow Hotel, Sandton, Johannesburg.

The summit brings together commercial and industrial energy users, project developers, financiers, regulators and solution providers to explore practical approaches to energy security, procurement and storage deployment.

For businesses assessing how storage can support their operations, the event offers an opportunity to meet SAESA and engage with the wider energy community on the decisions shaping South Africa’s evolving electricity system.

Commercial and industrial energy decision-makers are invited to apply to attend as hosted buyers. Qualifying buyers receive complimentary summit access and curated opportunities to engage with industry partners.


Meet SAESA at C&I Energy + Storage Summit: Join the Hosted Buyer Programme

The Hosted Buyer Programme connects commercial and industrial energy decision-makers with solution providers shaping South Africa’s evolving private energy market.

Qualified energy buyers receive complimentary access to the summit and curated engagement with industry partners exploring energy procurement, storage deployment and project development.

Apply for the Hosted Buyer Programme (https://apo-opa.co/4ehLijJ)

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Energy

Nigeria Mining Week 2026 sets the agenda for the sector’s next decade

Published

on

Nigeria Mining Week

International Lithium Association and Mercuria Energy Trading NG join Nigeria Mining Week 2026 ahead of its opening in Abuja on 12 October

Nigeria has the mineral endowment to play a growing role in global supply chains, including critical minerals

CAPE TOWN, South Africa, October 8, 2026/APO Group/ —Programme and delegate passes: www.NigeriaMiningWeek.com

With less than a week to go, Nigeria Mining Week 2026 has added a global commodity trader and the world’s lithium trade association to its programme. Mercuria Energy Trading NG has signed as a Gold Sponsor, and the International Lithium Association (ILiA) has joined as a Supporting Association.


They join Nigeria’s mining leaders, investors and operators in Abuja from 12 to 14 October for three days on the questions that will define the sector’s next decade: who finances Nigerian projects, who buys their output, and how much of it is processed in Nigeria.

Now in its 11th edition, the event takes place at the Abuja Continental Hotel under the theme “Unlocking Investment and Growth through Partnerships”. More than 3,080 attendees and more than 90 sponsors and exhibitors are expected across seven strategic forums.

The decisions made on processing, financing and market access over the next few years will shape Nigerian mining for the decade ahead. Nigeria Mining Week puts the people making those decisions in the same room.

On the agenda

The programme follows six content pillars: exploration and geological data; financing and investment; industrialisation and processing; infrastructure and power; ESG, transparency and community development; and international and regional collaboration.

  • 12 October: pre-conference and roundtables on geological data, financing for junior miners, compliance and enforcement, and power and infrastructure.

Available to conference attendees only.

  • 13 October: conference and exhibition opening, the new Critical Minerals Forum, the Women in Extractive Industries Forum and technical workshops
  • 14 October: Gold Day, sessions on steel and industrial minerals, the Deal Room and further technical workshops

The Deal Room is a curated space for one-on-one meetings between mining projects and financiers, off-takers and strategic partners. Projects seeking offtake or financing can apply to take part.

International Lithium Association joins as Supporting Association

ILiA, the global trade association for the lithium industry, will take part in the Critical Minerals Forum on 13 October. Astrid Karamira, EMEA Representative Director at ILiA, joins the panel “Building Reliable Pathways from Nigeria to Global Battery, Magnet & EV Markets”.

The session looks at what Nigerian projects must do to reach international battery markets: technical and quality standards, traceability and responsible sourcing, export readiness, and the step from exploration success to commercial operation.

“Global buyers are asking more of their suppliers on quality, traceability and responsible sourcing than ever before. Nigeria Mining Week is an opportunity to discuss openly what those expectations mean in practice, and how Nigerian projects can meet them.”

Mercuria Energy Trading NG signs as Gold Sponsor

Mercuria Energy Trading NG is the Nigerian subsidiary of Mercuria, one of the world’s leading independent energy and commodity groups. It brings a buyer and offtaker perspective to the programme.

For many Nigerian projects, a credible buyer is the gap between a promising deposit and a financed mine. Mercuria will contribute to discussions on commodity trading and offtake partnerships, critical minerals supply chains, and infrastructure and logistics.

“Nigeria has the mineral endowment to play a growing role in global supply chains, including critical minerals. We look forward to sharing how trading, offtake and logistics partnerships can help Nigerian projects reach global markets.”

Event details

The programme is subject to change.

Distributed by APO Group on behalf of Nigeria Mining Week.


Continue Reading

Trending