Connect with us
Anglostratits

Business

Hotel development booms in Africa, boosted by Egypt and Marriott

Published

on

Hotel Development

Development activity has been growing impressively in North Africa, which saw a 23% year-on-year increase, compared to a 6% increase in sub-Saharan Africa

WINDHOEK, Namibia, April 8, 2025/APO Group/ –This year’s Hotel Development Pipeline Report, the definitive study of international hospitality development projects in Africa, reveals record activity. There are 577 hotels and resorts, with 104,444 rooms, in the development pipeline, up by 13.3% on 2024, way ahead of the single digit pipeline growth reported globally by the leading international chains.

The report, compiled by Lagos-based W Hospitality Group, with data from 50 international and regional hotel chains, shows that development activity has been growing impressively in North Africa, which saw a 23% year-on-year increase, compared to a 6% increase in sub-Saharan Africa. Over the past five years, the hotel development pipeline has grown at an annualised rate of 4% in sub-Saharan Africa, 12% in North Africa and 7% overall.

Egypt continues to lead the way in terms of development, with 143 hotels and 33,926 rooms in the pipeline there. This is almost four times the number of rooms in second-placed Morocco, which has 8,579 rooms in 58 hotels. The following eight countries, ranked by number of rooms, comprise Nigeria, 7,320; Ethiopia, 5,648; Cape Verde, 5,565; Kenya, 4,344; Tunisia, 4,336; South Africa, 4,076; Tanzania, 3,432; and Ghana, 3,125. International hotel chains have deals signed in 42 of Africa’s 54 countries.

Despite its clear leadership in the absolute pipeline numbers, Egypt has fewer than 50% of rooms under construction, a significantly lower proportion than second-placed Morocco, with over 72%. Of the top 10 countries, Ethiopia has the highest ratio of rooms “on site”, followed by Morocco and Ghana. Cape Verde, Nigeria and Tanzania have some of the lowest percentages. However, “under construction” does not necessarily mean that there is activity and progress towards completion and opening – many of the sites in Nigeria and Ghana, for example, have been closed for several years, with hardly a hard hat in sight.

A more granular analysis, looking at the location of planned properties, reveals an extraordinary boom in Cairo, with 17,757 new rooms projected in over 70 hotels. The contrast with the second-placed location, Sharm El Sheikh, is dramatic, where 4,231 rooms are planned in fewer than 10 properties. The cities and resorts with the next largest pipelines by number of rooms are Lagos, 3,709; Boa Vista, 3,650; Addis Ababa, 3,369; Casablanca, 2,939; Accra, 2,652; Abuja, 2,570; Zanzibar, 2,523; and Dakar, 2,334.

The growth is being driven strongly by the major international hotel chains, with Marriott International leading the way, 165 hotels with 29,639 rooms. It is followed by Hilton, 93 hotels with 17,040 rooms; Accor, 73 hotels with 15,013 rooms; IHG, 40 hotels with 7,951 rooms; Radisson Hotel Group, 32 hotels with 6,346 rooms; TUI Hotels & Resorts, 11 hotels with 2,954 rooms; Barceló Hotels & Resorts, 7 hotels with 2,193 rooms; The Ascott, 15 hotels with 1,897 rooms; Kerten Hospitality, 13 hotels with 1,881 rooms and Wyndham Hotels & Resorts, 7 hotels with 1,706 rooms.

In the race for dominance, Hilton added slightly more rooms to its African pipeline last year than Marriott International and achieved a higher percentage growth. Barceló Hotels & Resorts recorded the largest percentage growth, more than doubling its pipeline to 2,193 rooms, with three large resort signings in North Africa.

The fact that hotel chains signed 125 new deals last year, with 21,000 rooms, is evidence that opportunities for further development abound

Below the headline numbers, there are three notable trends. First, the actualisation rate (actual openings vs. expected openings), which has nearly doubled from 21% in 2023 to 38% in 2024. While it’s substantially less than the 75% actualisation rate achieved in 2019, it shows a continuing recovery from the economic devastation of COVID-19. Of the total 104,444 rooms in the pipeline, over 50,000 rooms (nearly 50%) in 304 hotels are expected to open in 2025 and 2026.

Second, resort projects are increasing much faster than city or airport hotels, both in percentage terms and in absolute numbers, driven by the number of signings and by the larger average size of the developments, 210 keys vs. 170.  Also, almost half of the rooms that opened last year were in resorts.

Third, there is a definite movement by the chains towards the franchise model, with 108 projects representing almost 19% of the total, compared to less than 10% in 2020. A major factor is the emergence of quality, international, white-label operators such as Aleph Hospitality and Valor Hospitality, and some indigenous operators in Nigeria, Kenya and elsewhere, that are increasing confidence that brand standards will be met.

The full report will be discussed at FHS Africa (formerly AHIF) 17-19 June in Cape Town. It is the leading hospitality investment conference in the region, which brings together senior decision-makers to shape the future of the industry. Matthew Weihs, Managing Director of the Bench, which organises FHS Africa, said: “The growth in hotel development across Africa is a testament to the continent’s economic and tourism potential. Furthermore, the commitment from the international hotel chains makes it clear that global players see Africa as a strategic opportunity.”

Trevor Ward, Managing Director of W Hospitality Group, concluded: “Despite the various trials that the continent faces, the fact that hotel chains signed 125 new deals last year, with 21,000 rooms, is evidence that opportunities for further development abound. According to the Global Cities Institute, by the year 2100, 10 of the world’s 16 largest cities will be in Africa, with all but one of them (Cairo) in sub-Saharan Africa. So, one might say that development activity in Africa has barely scratched the surface.”
Distributed by APO Group on behalf of The Bench

Business

Africa gains governance momentum in the 2026 Chandler Good Government Index, but sustaining progress is the real test

Published

on

Africa

Across Africa, average scores improved in six of the seven CGGI pillars over the past year, with the strongest gains in Helping People Rise and Financial Stewardship

This signals that stronger government capabilities are beginning to translate into tangible improvements in people’s lives

KIGALI, Rwanda, October 29, 2026/APO Group/ –Africa was the second best-performing region for governance progress in the 2026 Chandler Good Government Index (CGGI), with 71% of the African countries assessed in both 2025 and 2026 achieving higher overall scores. However, the continent remains the lowest-scoring region overall, highlighting the challenge of translating improvement in government capabilities into better outcomes for citizens.


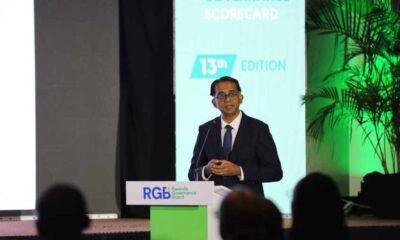
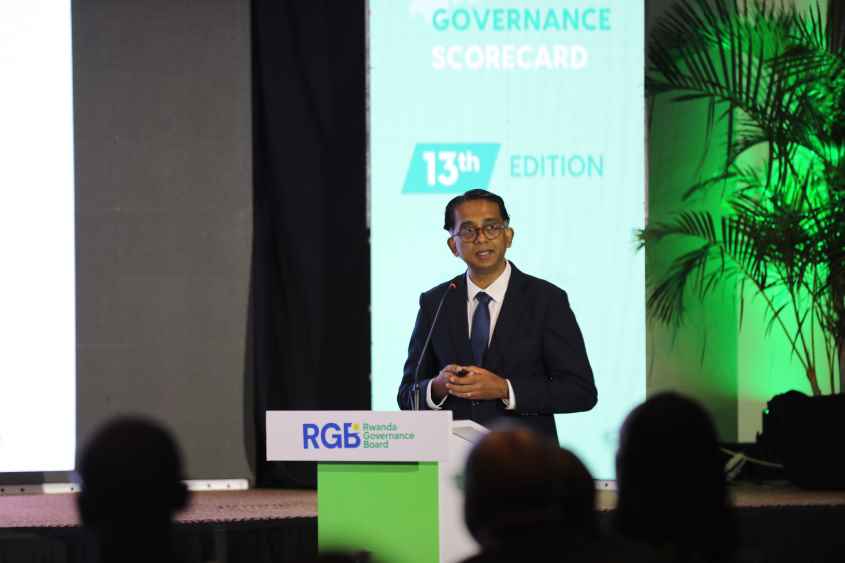
These findings were highlighted by the Chandler Governance Group (CGG) at a joint session with the Rwanda Governance Board (RGB) to launch the 13th edition of the Rwanda Governance Scorecard at the Kigali Serena Hotel on Thursday, 22 October 2026.

“This year, Africa’s strongest gains came in Financial Stewardship, followed by Helping People Rise, the CGGI’s outcomes pillar. This signals that stronger government capabilities are beginning to translate into tangible improvements in people’s lives, from access to quality education and healthcare to the public finances that fund them. The task now is to sustain that progress over the coming years,” says Dinesh Naidu, Director (Knowledge) at CGG.

Now in its sixth edition, the CGGI assesses government capabilities and effectiveness across 133 countries representing 94% of the world’s population, up from 120 countries in 2025. It measures 35 equally weighted indicators across seven pillars, providing governments with a framework to benchmark performance, identify gaps and learn from the experience of other countries.

Globally, the findings point to improving governance performance. Of the 120 countries assessed in both 2025 and 2026, 61% recorded higher scores, representing the highest annual share of countries improving since the Index launched in 2021. However, longer-term progress has been less consistent, with only 43% of the 104 countries tracked since 2021 recording an overall improvement.

Africa’s leading governments

Mauritius remains Africa’s highest-ranked country, placing 55th globally, followed by Rwanda (62nd), Botswana (70th), Morocco (79th) and Tanzania (80th). South Africa ranks sixth on the continent, in 85th place globally.

Rwanda features prominently in the discussion, ranking 11th globally for Leadership & Foresight and emerging as the highest-ranked low-income country in the Index. It ranks 61 places above where its income alone would predict. Across the Index, government capabilities track citizen outcomes more closely than national wealth does, suggesting that strengthening government capabilities matter in delivering better outcomes for citizens.

The joint session brings together the CGGI’s international benchmarks and the Rwanda Governance Scorecard’s assessment of governance in the Rwandan context, creating an opportunity to consider both global perspectives and country-specific priorities.

Progress across key governance pillars

Across Africa, average scores improved in six of the seven CGGI pillars over the past year, with the strongest gains in Helping People Rise and Financial Stewardship. These improvements point to progress in areas associated with public services, including healthcare and education, as well as the management of public finances.

Longer-term trends also highlight areas of progress. Between 2021 and 2026, nearly every African country assessed across the period improved its Data Capability score, with Morocco recording the largest gains. Ghana’s overall score improved in 2026, supported by stronger Financial Stewardship, while South Africa continues to show relative strength in Robust Laws & Policies, ranking 44th globally, and Attractive Marketplace, ranking 48th.

Despite these gains, the scale of the challenge remains clear. Africa’s regional average is still below its 2021 level, 23 of the 35 African countries in the 2026 Index rank outside the global top 100, and none is in the top 50. Seven African countries joined the Index this year: Chad, the Democratic Republic of Congo, Gambia, Guinea, Lesotho, Liberia and Togo.

“Rankings provide a useful starting point, but the broader value of the CGGI lies in helping governments understand where they are making progress and where further work is needed. Sustained improvements depend on the ability to strengthen institutions, manage resources responsibly and turn policy into meaningful outcomes for citizens,” says Naidu.

A tool for learning and improvement

The CGGI is designed as a practical diagnostic tool, helping governments identify gaps, track progress over time, and learn from peers facing similar constraints. The collaboration with the RGB brings international benchmarking together with locally grounded assessment.

“Every country faces its own governance challenges and is driven by varying priorities. Governments that are willing to take stock of the evidence and learn from peers to strengthen their institutions are well placed to achieve real improvements,” concludes Naidu.

Distributed by APO Group on behalf of Chandler Governance Group.


Continue Reading

Business

Spiro brings electric motorcycles and battery-swapping technology to Ghana, expanding its pan-African footprint

Published

on

Spiro

The integrated offering aims to reduce daily operating costs and minimise downtime, with battery swaps completed in just two minutes and potential savings of up to USD 2 per day compared with petrol-powered motorcycles

ACCRA, Ghana, October 29, 2026/APO Group/ —

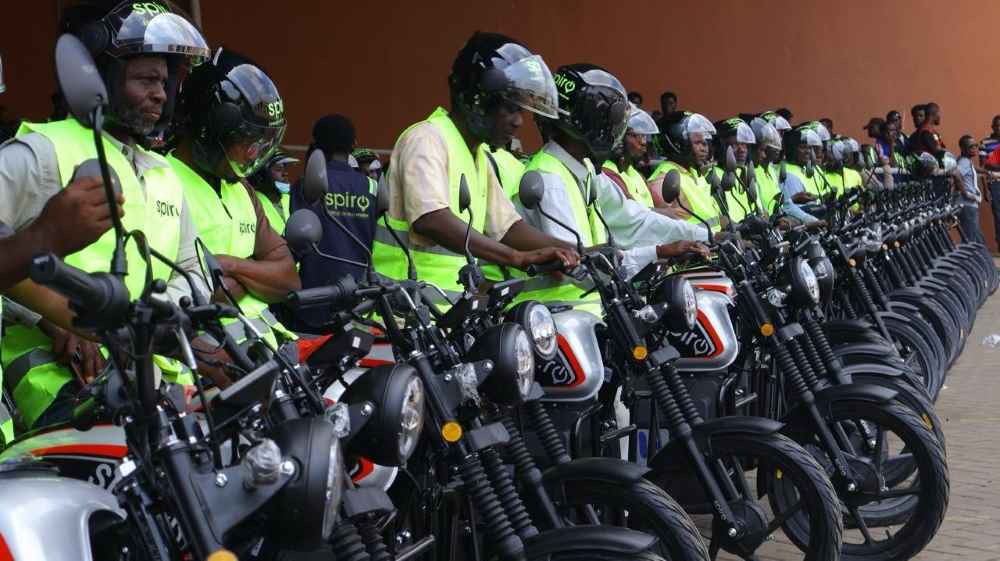
  • Spiro’s entry into Ghana introduces the Ekon 450 M1 V3 electric motorcycle and its battery-swapping solution, bringing a new mobility option to commercial riders and delivery fleets.
  • The integrated offering aims to reduce daily operating costs and minimise downtime, with battery swaps completed in just two minutes and potential savings of up to USD 2 per day compared with petrol-powered motorcycles.
  • Test rides and product demonstrations across Greater Accra will support the rollout and help riders experience the benefits of electric mobility.


Spiro (www.Spironet.com), Africa’s largest electric mobility company, is expanding its footprint in Ghana with the introduction of the Ekon 450 M1 V3 electric motorcycle and its battery-swapping solution. Combining electric two-wheelers with access to charged batteries, Spiro aims to make everyday transport more affordable and practical for riders while supporting Ghana’s transition towards sustainable mobility.

For commercial riders and delivery fleets, fuel expenses and time spent off the road directly affect daily earnings. Spiro’s integrated offering addresses both challenges: riders can exchange a depleted battery for a charged one at a Spiro battery-swapping station in just two minutes, while potentially saving up to USD 2 per day in operating costs compared with conventional petrol-powered motorcycles.

Ghana represents a major opportunity for electric mobility, with a rapidly growing two-wheeler market and increasing demand from commercial riders and delivery fleets

Designed to meet the everyday mobility needs of African riders, the Ekon 450 M1 V3 offers an alternative to petrol-powered motorcycles. Supported by Spiro’s battery-swapping technology, it allows riders to get back on the road without waiting for their motorcycle to recharge.

Auroasish Choudhuri Managing Director Central and West Africa, commented: “Our entry into Ghana is an important step in strengthening Spiro’s presence in West Africa. Our focus is on building a local ecosystem that riders can rely on, combining electric motorcycles with convenient access to battery swapping. By working closely with local partners and listening to riders’ needs, we aim to support the long-term adoption of electric mobility in Ghana.”

Kaushik Burman, CEO Mobility of Spiro said: “Ghana represents a major opportunity for electric mobility, with a rapidly growing two-wheeler market and increasing demand from commercial riders and delivery fleets. By bringing the Ekon 450 M1 V3 together with our battery-swapping solution, we are addressing two key barriers to adoption: operating costs and access to charging infrastructure. Our ambition is to build a strong foundation for electric mobility to scale across Ghana.”

To support its rollout, Spiro is engaging with prospective customers through test rides, product demonstrations and live demonstrations of its battery-swapping technology across Greater Accra. These activities give riders the opportunity to experience the Ekon 450 M1 V3 and understand how battery swapping can fit into their daily routines.

Mr Maxwell Dodd, Managing Director of Spiro Ghana, said: “For riders in Ghana, the value of electric mobility lies in what it can deliver every day: lower operating costs, less downtime and more time on the road. Through the Ekon 450 M1 V3 and our battery-swapping solution, we want to make those benefits accessible and support riders as they make the transition to electric motorcycles.”

Ghana forms part of Spiro’s wider expansion across Africa. Building on its recent USD 270 million equity funding round and an additional USD 18 million in debt financing from the Africa Go Green Fund, the company is scaling its electric mobility ecosystem with the ambition of establishing a presence in 20 African markets. Spiro is also preparing to enter new countries, including Ethiopia, Malawi, Mali and the Democratic Republic of Congo.

Distributed by APO Group on behalf of Spiro.


Continue Reading

Business

Huawei Wireless Unveils Innovation Breakthroughs to Pioneer New Communications Networks

Published

on

Huawei

The innovation breakthroughs for pioneering new communications networks include RetinaMIMO, new materials, and OSCAR solution among other root technologies. By tackling coverage, energy consumption, and capacity challenges, the breakthroughs drive ubiquitous experience, simplified and green networks, and superior spectral efficiency. The breakthroughs have unlocked a wealth of new capabilities, including the world’s first commercial U6 GHz device VitaAAU, GigaGreen Plus series, and UBBPi series.
Huawei promotes A2A-T standards and drives commercial open-source OpenAN through extensive partnerships to build an open telecom agent ecosystem.


SHANGHAI, CHINA – Media OutReach Newswire – 29 October 2026 – At Huawei Decoding China 2026, Fang Xiang, Corporate Vice President and President of Wireless Network Solution of Huawei, unveiled a series of innovation breakthroughs to pioneer new communications networks. The innovation breakthroughs mark major leaps in root technologies focused on ubiquitous experience, simplified and green networks, and superior spectral efficiency. With the breakthroughs, Huawei has launched the world’s first commercial U6 GHz device VitaAAU, GigaGreen Plus series, and UBBPi series. Additionally featuring the new progress in open ecosystem for telecom agents, the breakthroughs will lay a solid foundation for new communications networks.

With booming intelligent devices and services, new devices, traffic, and applications are taking shape in the mobile industry. The new devices are expanding network connectivity from people to things and agents, increasing the number of connections by 100 times. Device-cloud synergy for intelligent services calls for stronger uplink capabilities to support training and inference, shifting network focus from downlink dominance to both uplink and downlink. With new applications, come a diversity of new interaction modes, calling for higher standards in experience and driving networks to support ubiquitous steady ultra-low latency with a high reliability.

As the world steps into an intelligent era, the value of connectivity is not only about quantity—it’s more about quality. This has been inspiring Huawei to convert cutting-edge breakthroughs into the commercial practices of new communications networks by focusing on root technologies for ubiquitous experience, simplified and green networks, and superior spectral efficiency.

Pioneering ubiquitous experience

RetinaMIMO is a new pioneering technology designed to solve the challenge of concurrent ultra-high bandwidth and ubiquitous coverage. It features the industry’s first Retina scanning system that allows RF link topologies to be reconstructed to eliminate coverage collapse in the vertical direction. It also adopts a reconstructed antenna array architecture to address the diminishing marginal gains as array elements (AEs) increase.

Based on RetinaMIMO, Huawei has launched the world’s first commercial U6 GHz device VitaAAU. Compared with similar products with 1024 AEs, VitaAAU widens coverage by about 30%, enabling U6 GHz to match C-band in both horizontal and vertical directions. This enables operators to deliver U6 GHz coverage for new communications networks on their C-band sites, minimizing overall TCO. To date, VitaAAU has seen commercial adoption in the UAE and other markets, with peak downlink speeds exceeding 10 Gbps, making ubiquitous premium experience a reality.

Pioneering simplified, green networks

Huawei’s pioneering EP power amplifier (PA) architecture capitalizes on new materials and technologies to solve the problem of energy efficiency decline on higher frequency bands, maximizing energy conversion efficiency. The industry’s first-ever multimode dielectric filters allow antennas to have small dimensions and low power consumption on multi-channel networks with high frequency bands. Powered by new materials, technologies, and architectures, VitaAAU antenna is reduced to 1.5 m in diameter while supporting “0 Bit 0 Watt 0 Loss”, delivering superior energy saving efficiency. These innovations enable Huawei’s GigaGreen Plus series products to achieve significant reductions in dimensions, weight, and power consumption, better positioned to power simplified and green networks.

Pioneering superior spectral efficiency

Multi-band, multi-cell, and multi-user interference is a major restrictive factor of capacity. The time scaling of the Tau (τ) law is introduced to base stations for the first time to realize optimal dynamic resource scheduling across all domains based on the OSCAR solution. With low-latency bus and high-speed interconnect technology, a high-speed architecture is built to enable the real-time exchange of massive data. Thanks to software and hardware synergy, new UBBPi series products improve average user experience by 1.3 times while reducing power consumption by approximately 40%, further improving spectral and energy efficiency.

Pioneering open-source autonomous networks

Autonomous networks have emerged as an inevitable choice to deal with the growing AI services and increasing network complexity. RANSpirit is another industry first from Huawei, implementing single-domain network autonomy based on the telecom foundation model and digital twins. To date, RANSpirit is serving more than 1.2 million cells across 25 networks around the world, providing assistance to more than 2,000 engineers.

Extensive agent collaboration relies on an open, win-win ecosystem. This galvanizes Huawei to join industry partners to develop ecosystem standards, communities, and industry alliances. In terms of standards, Huawei adapts to the TM Forum, building a cross-agent foundation on the A2A-T standard and framework agreed upon by the industry. In terms of communities, Huawei jointly promotes neutral open-source communities and donates open-source agent components to the Linux Foundation, driving global collaboration and innovation. With regard to industry alliances, Huawei has taken the initiative to pool ecosystem strengths to accelerate business implementation based on the GSMA industry platform.

Fang concluded with the reiteration of Huawei’s unswerving pursuit of dual-drive innovation to promote new breakthroughs in mobile networks and work with partners from around the world to deepen the OpenAN ecosystem, advancing new communications networks through technological innovation and open collaboration.

FAQs

Q1: Why is it challenging to balance ultra-high bandwidth and ubiquitous coverage?

Ultra-high bandwidth depends on higher frequency bands. As we know, a higher frequency leads to a greater propagation loss of electromagnetic waves and a weaker ability for them to penetrate obstacles, because high-frequency signals attenuate fast and have short coverage distances, while ubiquitous coverage requires signals to travel a long distance in complex environments. Inherently, the two priorities pull in sharply opposite directions.


Continue Reading

Trending