Connect with us
Anglostratits

Business

Global advertising spend to top $1trn for first time this year

Published

on

WARC forecast

Projected 10.5% rise in global spend this year represents a 2.3 percentage point (pp) upgrade to WARC forecast, reflecting the uptake of AI-enabled media tools

North America to grow 8.6% this year to $348bn, APAC market worth $272bn but growth cools to just 2.0%, Europe forecast to rise 5.0% to $165bn, Latin America +6.2% to $32.1bn, Middle East largely unaffected by looming threat of regional conflict +4.2% to $12.6bn

US political spend set to reach $15.8bn this year; $3.6bn spent across social platforms with growth rapidly increasing since change of Democratic candidate

WARC Global Ad Spend Outlook 2024/25 – A Decade of Consolidation

22 August 2024 – A new study from WARC, the experts in marketing effectiveness, has found that global advertising spend is on course to grow 10.5% this year to a total of $1.07trn – the best performance in six years if the post-Covid recovery of 2021 (+27.9% year-on-year) is disregarded.

Ad spend growth is also anticipated next year (+7.2%) and in 2026 (+7.0%), culminating in a global ad market worth $1.23trn. Global ad investment has more than doubled over the last decade, and has grown 2.8x faster than global economic output since 2014. Just three companies – Meta, Amazon and Alphabet – account for more than 70% of this incremental spend. This trifecta is expected to attract 43.6% of all advertising spend this year, rising to a share over 46% by 2026.

WARC’s latest global projections are based on data aggregated from 100 markets. New for this edition, WARC is now leveraging an advanced neural network machine learning model which projects advertising investment patterns based on over two million data points spanning macroeconomic data, media owner revenue, marketing expenses from the world’s largest advertisers, media consumption trends and media cost inflation. It is believed to be one of the most comprehensive advertising market models available to the industry today.

The new projections show that ‘pureplay’ (i.e. online only) internet companies are set to record a 14.0% rise in advertising revenue this year, reaching a total of $735.7bn. In total, almost nine in every ten (88.5%) incremental dollars spent on advertising this year will go to online-only businesses, with half (52.9%) being paid to Alphabet, Amazon and Meta. Taken together, pureplay platforms are set to account for over 70% of all advertising spend worldwide next year.

Retail media (+21.3%), social media (+14.2%) and search (+12.1%) are set to lead digital growth in 2024, with these three sectors alone accounting for over 85% of online spend and almost three in every five (58.7%) incremental dollars spent on advertising worldwide this year. All are benefiting from the increased adoption of AI-driven ad services and growing appreciation of first party data.

James McDonald, Director of Data, Intelligence and Forecasting, WARC, and author of the research says: “The global ad market has doubled in size over the last decade, with advertising investment growing almost three times faster than economic output since 2014. Three companies – Alphabet, Amazon and Meta – have been the largest beneficiaries from this period of expansion, attracting seven in ten incremental ad dollars over the last ten years.

“With retail media expected to lead ad spend growth over the coming years, and with new, diverse players emerging in ad selling – from Uber to Chase – we are once again seeing the value of first party data in targeting the right person with the right message at the right time. Such data, combined with new AI enhancements, will constitute the fabric of the advertising industry for the next decade and beyond.”

Key findings outlined in WARC’s Global Ad Spend Outlook 2024/25 are:

MEDIA TRENDS: Global ad spend is forecast to rise 10.5% this year to a total of $1.07trn, and then 7.2% in 2025 and 7.0% in 2026; social, retail media and CTV to lead growth

At $241.8bn in 2024, social media is the largest single advertising channel measured in WARC’s study, having overtaken search (excl. retail media) for the first time last year. It accounts for 22.6% of all global ad spend this year and is forecast to rise to a share of 23.6% by the end of 2026.

Within social, Meta is the largest individual player, commanding 62.6% of the market this year. Its share is being eroded however, most notably by Douyin and TikTok owner Bytedance, which now draws a fifth (20.1%) of all social spend, up from a share of just 9.3% five years ago. TikTok is on course to account for over half of its parent-company’s advertising revenue for the first time next year with estimated ad billings over $28bn, though uncertainty remains around the platform’s future in the US – its largest market by far with 170m monthly active users.

The main social platforms have reported a fillip from new, AI-enabled services during the first half of 2024, a trend that is set to underpin the advertising industry at large over the coming years. Over half of all AI-enabled spend – defined as involving some form of recommendation algorithm, natural language processing or search optimisation – ​today occurs in the social media sector.

Search advertising (excluding retail media) accounts for 21.8% of global advertising spend, at a forecast total of $223.8bn this year. Its share has consistently grown since WARC began monitoring the sector in 2013, though it is set to plateau in 2026 as more purchase journeys begin in retail media environments and social commerce begins to realise its potential outside of Asia. Another potential headwind may be the rise of AI-driven search, and uncertainty around what the ad experience will look like for consumers more familiar with text-based search experiences.

Google accounts for more than four-fifths (84.0%) of the global search market, with its paid search revenue set to top $200bn for the first time next year. Google’s share rises to over 90% if China is excluded, a position of dominance which this month led a US judge to rule the company in breach of antitrust laws.

Retail media is expected to account for 14.3% of global ad spend this year – a total of $152.6bn – which is double the share recorded in 2019 before the pandemic contributed to an exceptional growth spurt. Indeed, retail media is expected to be the fastest-growing channel over at least the next three years.

Amazon is the dominant global player, with anticipated ad revenue (excluding Twitch and Prime Video) of $55.9bn equivalent to more than a third (36.6%) of all retail media spend and over two-thirds excluding China this year. While competition is heating up, such billings eclipse the near $4bn Walmart is due to net in 2024 and the $1bn ad business Uber is building, while Amazon is also due to have surpassed Alibaba by ad revenue for the first time this year.

CTV is on course to be worth $35.3bn to advertisers this year, roughly a quarter of the size of the linear TV market. Growth is rapid; CTV spend is expected to rise 19.6% and is set to account for two-thirds of all growth in the video (linear + CTV) market this year, and all growth in 2025. By 2026, CTV is projected to account for almost a quarter (23.9%) of all video ad spend, at $46.3bn.

Netflix is the largest streaming provider globally, with 277.6m subscribers worldwide in Q2 2024. However, its global advertising business is unlikely to grow too far beyond $1bn this year. YouTube’s ad income – which we do not yet classify as CTV – is expected to rise 14.3% to $36.0bn this year. Further, YouTube’s ad revenue is set to top $45bn globally by 2026, almost as much as the entirety of the global CTV industry at that time.

Legacy media, encompassing print publishing, broadcast radio, linear TV, cinema and out of home (OOH), now collectively account for a quarter (25.3%) of total advertising spend, having recorded a dip in share in each of the last 15 years.

Advertising spend on legacy media is expected to total $270.5bn this year, representing a 1.5% rise from 2023. Much of this growth can be attributed to US political spending; with this removed legacy media are, collectively, set to record a 0.5% decline in advertiser investment in 2024.

Linear TV spend is expected to grow by 1.9% this year, its best performance since 2014 if the post-Covid recovery year of 2021 (+12.7%) were excluded. The market is flat (+0.1%), however, excluding US political spend. Out of home (+7.2%) and cinema (+6.1%) will see some growth this year, though radio (-2.3%) is expected to record its third consecutive year of decline. Newsbrands (-3.3%) and magazine brands (-3.4%) are also due to see losses across print and online editions.

PRODUCT SECTOR TRENDS: Technology & Electronics (+13.2%), Alcoholic Drinks (+12.2%) and Clothing & Accessories (+11.1%) the fastest-growing consumer sectors next year. US political spend is expected to reach $15.8bn this year; over a fifth spent on social.

Advertising spend during the 2024 US presidential election is on course to top $15bn for the first time, with an expected total of $15.8bn up by over 40% on the previous cycle in 2020. Spend had been lagging the 2020 total earlier this year, but the surprise decision to change the Democratic candidate has led to an influx in spending in order to reposition the new ticket of Kamala Harris and Tim Walz. This shift is perhaps most pronounced online: political spending on social media is tracking 27.4% higher in Q3 2024 versus Q2 2024, with social spending by both main parties on course to reach $3.6bn this year.

Retail – the largest of the 19 categories monitored by WARC – is anticipated to record a 2.5% dip in global spend this year. Our definition of this sector is broad however, ranging from quick service retail (QSR) to grocery to department stores to online retailers, such as Temu. The latter is expected to continue investing heavily in advertising, particularly in Europe this year, but it is an exception – the longer tail of retailers are facing business pressures from soft consumer demand.

Technology & Electronics – the third-largest product sector monitored by WARC – is expected to post the fastest growth this year, with incremental spend of $17.0bn worldwide. The sector had recorded declines in advertising spend in both 2022 and 2023, as central banks raised interest rates sharply in an attempt to stymie inflation, exposing over-leveraged tech startups in particular.

Technology & Electronics (+13.2%), Alcoholic Drinks (+12.2%) and Clothing & Accessories (+11.1%) are forecast to lead ad spend growth among consumer-facing products in 2025, though Business & Industrial, the second-largest category, is expected to be the fastest-growing category overall next year (+18.2%), as budgets unlock during a period of comparatively favourable economic and trading conditions.

The Nicotine category is also growing rapidly, albeit from a low base; it is the smallest of the 19 product categories monitored by WARC at $13.0bn in 2024. Spend is set to grow 56% over the three years to 2026 – reaching a total of $17.2bn – driven almost entirely by vape products which skew heavily towards online advertising.

REGIONAL TRENDS: North America to grow 8.6% this year to $348bn, APAC growth cools to just 2.0% owing to stronger dollar, Europe is forecast to rise 5.0% to $164.9bn, while Middle East ad markets are largely unaffected by looming threat of regional conflict

North America is on track to be the fastest-growing region this year – inflated by the US presidential elections – with ad spend rising 8.6% to a total of $347.5bn. US ad spend is expected to grow 8.9% this year (+4.0% excluding political spend, more than double the 1.4% growth rate recorded in 2023) to a total of $330.8bn. A further rise, of 3.6%, is forecast next year, by when the US ad market should be worth over $342bn. The Canadian ad market is due to grow 7.5% to CAD23.3bn ($16.8bn) this year.

Latin America (+6.2% to $32.1bn in 2024) then follows, with its largest market, Brazil, forecast to record local currency growth of 9.6% this year to a total of BRL85.7bn ($14.8bn) – an acceleration from the 7.5% rise recorded last year. Our forecasts suggest that online advertising will account for over half (50.4%) of the Brazilian ad market for the first time this year.

APAC’s (+2.0% to $272.0bn this year) largest market – China – is projected to see ad market growth of 6.4% this year to RMB1.32trn ($181.2bn), an easing from the 9.3% rise recorded in 2023 as consumer demand remains soft and economic expansion lags stubbornly behind the target. Pureplay internet will account for over 86% of the Chinese ad market in 2024, though social media (+10.5%) and retail media (+8.2%) will expand at a slower rate this year than last.

When measured in local currency – so as to exclude the distorting effect of exchange rate fluctuations – we see that India will be the fastest growing key market this year, with advertiser spend rising 11.9% to INR1.08trn ($12.8bn).

Japan – the fourth-largest ad market in the world – is forecast to grow by 5.2% this year to JPY5.83trn ($36.9bn), though this equates to a 6.3% decline when measured in US dollars due to the Yen falling to a decade-long low. Australia’s ad market is expanding by 2.0%, a modest but welcome change of fortunes following flat (+0.3%) growth in 2023, while Indonesia is expected to achieve 7.8% growth this year.

Advertising spend across Europe is forecast to rise 5.0% this year to $164.9bn. The UK, the largest European market by spend, is expected to post an 8.0% rise to £38.5bn ($47.5bn) in 2024 per market data from the AA/WARC Expenditure Report. On the European mainland, France (+8.0%), Italy (+5.4%) and Germany (+4.0%) are all expected to see healthy gains this year, with the former in particular benefiting from increased advertising activity around the Paris Olympics and Paralympics in the third quarter.

Brand spend in the Middle East and Africa is currently on course to rise by 4.2% to $12.6bn this year, though fortunes are mixed. African spend is expected to be flat (+0.2%), following a 15.7% decline in 2023 and 1.4% dip in 2022. South Africa, the region’s largest market, is expected to see its ad market grow 6.0% this year but this translates to a 1.1% increase when measured in dollars owing to a weak Rand by historical measures. Ad spend in the Middle East is set to rise 8.1% this year but that is subject to change should conflict spread beyond Gaza to the wider region.

A complimentary article by WARC’s James McDonald, author of the report, is available to read here. WARC subscribers can read the article and access additional data here.
Business

Cassava Technologies and Mauritius Telecom sign Memorandum of Understanding (MoU) on Artificial Intelligence (AI) services and education in Africa

Published

on

Africa

The partnership combines this computing scale, Cassava’s AI platforms and regional reach with MT’s own AI products, local language capabilities and operating experience

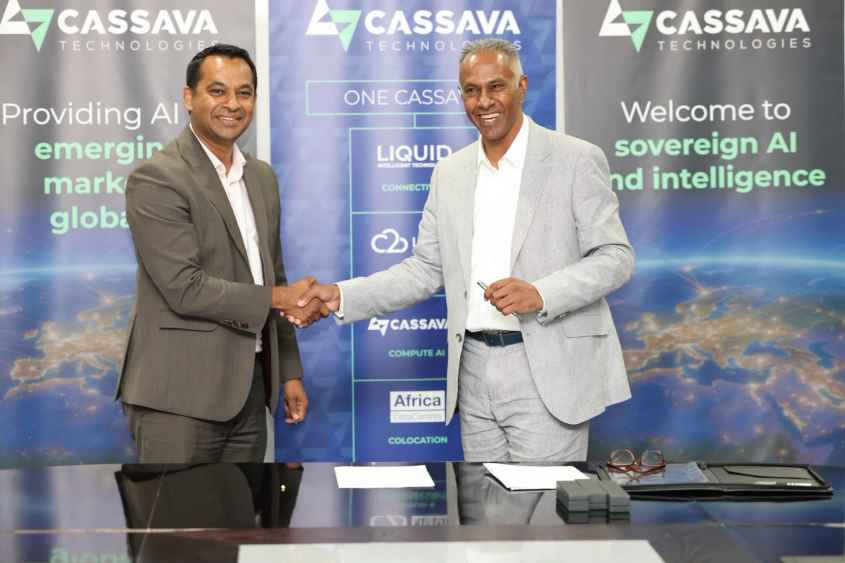
CAPE TOWN, South Africa, November 18, 2026/APO Group/ –Cassava Technologies (https://www.CassavaTechnologies.com/), a global technology company of African heritage, and Mauritius Telecom (MT) have signed a memorandum of understanding (MoU) at Africa Tech Festival to develop a strategic partnership focused on strengthening compute and model access for MT’s AI services and exploring opportunities for myt Learn, MT’s AI-powered education platform, in South Africa and other African markets.


Cassava’s NVIDIA-powered AI Factory in Cape Town is Africa’s most powerful supercomputer. The partnership combines this computing scale, Cassava’s AI platforms and regional reach with MT’s own AI products, local language capabilities and operating experience.

This partnership brings together products we have developed and Cassava’s infrastructure and reach to take that work further

“Realising AI’s promise in Africa requires more than potential; it takes infrastructure, technology, and proven expertise. By pairing Mauritius Telecom’s AI products and operating experience with Cassava’s AI infrastructure and reach, we aim to bring locally relevant AI services and education solutions to more African markets,” said Ziaad Suleman, SVP Cassava Technologies for South Africa and Botswana.

“We are building AI capability in Mauritius that can also serve other African markets. With myt Learn, we are already putting that capability to work in our schools, supporting both students and teachers. This partnership brings together products we have developed and Cassava’s infrastructure and reach to take that work further. Our ambition is to make trusted AI useful and accessible, while ensuring that those responsible for its use retain meaningful control,” said Veemal Gungadin, CEO of Mauritius Telecom.

The companies will explore access to Cassava’s AI Factory as an additional source of on-demand computing capacity for MT’s AI offerings, alongside access to AI models through CAIMEx, Cassava’s AI platform. Cassava capacity and model access would be used only for workloads where customers permit it. These options would complement MT’s existing myt AI Cloud platform and infrastructure in Mauritius, and could support its expansion into other African markets.

In education, the partners will jointly assess opportunities for myt Learn, starting with South Africa’s public and private education sectors, with potential expansion into other Cassava markets. Created by MT and rolling out in Mauritian schools for selected grades, myt Learn provides curriculum-aligned guided lessons, a multilingual AI tutor and personalised revision. Teachers have access to performance insights and AI tools for marking, test creation and lesson preparation. The platform can be adapted to local curricula and teaching needs.

Together, the companies aim to show how telecommunications operators can bring locally relevant AI services to customers and take African-developed products into new markets.

Distributed by APO Group on behalf of Cassava Technologies.


Continue Reading

Business

Afreximbank puts trade finance and compliance at the heart of Africa’s industrial transformation

Published

on

afreximbank

The forums will also explore how digitalisation, artificial intelligence and innovative financial instruments can improve trade efficiency, reduce costs and strengthen risk management

GABORONE, Botswana, November 17, 2026/APO Group/ –Afreximbank (www.Afreximbank.com) has called for increased financing of intra-African trade, stronger regulatory compliance frameworks and greater investment in value-added production to accelerate the continent’s economic integration and industrial transformation.


Speaking at the opening ceremony of the inaugural jointly held Afreximbank Trade Finance Seminar and Compliance Forum in Gaborone, Mr Lesego Moseki, Governor of the Bank of Botswana, emphasised that compliance should be recognised as a strategic asset that strengthens resilience, builds trust and enhances competitiveness. He called for greater collaboration among regulators, financial institutions and development finance institutions to foster a more harmonised and efficient trading environment across Africa.

In his opening remarks at the 2026 Afreximbank Trade Finance Seminar (ATFS) and Afreximbank Compliance Forum (ACF), Mr Haytham El Maayergi, Executive Vice President, Global Trade Bank, Afreximbank, highlighted the need for trade finance and compliance frameworks to work hand in hand to unlock the full potential of the African Continental Free Trade Area (AfCFTA) and accelerate intra-African trade.

“To build an integrated African market we to finace  connects us, and we cannot expand that trade sustainably without the trust, transparency and compliance systems that underpin it.”

El Maayergi said the changing global landscape made this imperative even more urgent, with geopolitical tensions and disrupted supply chains exposing the risks of overreliance on distant markets.

“As global markets look to diversify production beyond China, Africa must position itself as a natural partner of choice. The continent has the resources, vast land and, most importantly, its people. By 2050, one in four people globally will be African. Whether this demographic advantage becomes an asset or a liability will depend on the decisions we make today.

“To seize this opportunity, Africa must trade more with itself, and that trade must be adequately financed and underpinned by trust.”

He noted that although intra-African trade grew by 5.5 per cent in 2025, it still represents only around 14 per cent of Africa’s total trade. With 50 countries having ratified the AfCFTA but only 12 actively trading under its framework, he stressed that the priority must now be translating the agreement into tangible economic opportunities.

“We have opened the market. Our task now is to make that market work.

“It is about moving from exporting raw materials to processing, manufacturing, and creating greater value here in Africa. In other words, how can we get African resources to feed African industries and African businesses to serve African markets, while creating jobs for our people and retaining value that will support the growth and prosperity of African economies?”

As global markets look to diversify production beyond China, Africa must position itself as a natural partner of choice

Botswana’s industrial transformation presents opportunities for African trade

Highlighting Botswana’s role in advancing continental integration, Mr El Maayergi cited the country’s success in developing greater domestic participation in the diamond value chain, including the relocation of De Beers Group’s global rough-diamond sales activities from London to Gaborone.

He also highlighted the Botswana Stock Exchange’s collaboration with the Nigerian Exchange Group and other African exchanges to broaden cross-border investor access to the Dangote Petroleum Refinery IPO share offer.

Acting CEO of the Botswana Investment and Trade Centre (BITC), Mr Anthony Sefako, said Botswana’s economic transformation agenda presents significant opportunities for trade finance, investment and regional value-chain development.

“Botswana is currently pursuing a bold productive transformation, shifting from reliance on diamond mining towards a digitally enabled, export-led and diversified high-income economy.

“Botswana is targeting an increase in manufacturing exports to reach 23 per cent by 2036. From battery metal refining, pharmaceutical biomanufacturing and industrial steel to renewable energy hubs and agricultural value chains.

“The country is actively commercialising bankable industrial projects that require the very trade finance and supply chain liquidity tools being discussed during this gathering.”

Financing, innovation and compliance to unlock Africa’s potential

El Maayergi outlined four priorities to advance Africa’s trade and industrialisation agenda: integration, value creation, conviction in African enterprise, and trust.

He further highlighted Afreximbank’s role for regional integration through the Pan-African Payment and Settlement System (PAPSS), which enables cross-border payments in local currencies across more than 30 African countries. He also pointed to the Bank’s financing for mineral processing, its Strategic Minerals Development Programme and support for major African enterprises, including the Dangote Group.

He also mentioned XTRA, Afreximbank’s trading platform for African trade confirmations, which has facilitated more than US$1.5 billion in transactions and help develop a more liquid market for African risk.

On compliance, he emphasised the importance of effective regulatory and due diligence frameworks that facilitate rather than constrain trade. Such frameworks are essential to enabling African banks to maintain correspondent banking relationships, attract capital and participate confidently in global financial markets.

The forums will also explore how digitalisation, artificial intelligence and innovative financial instruments can improve trade efficiency, reduce costs and strengthen risk management. Afreximbank’s Africa Trade Gateway, which brings together TRADAR for trade information, MANSA for due diligence and verification, ATEX for market access and PAPSS for payments, was highlighted as an important part of this effort.

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Business

Tüyap highlights Middle East and North Africa (MENA) sourcing opportunities at the carpet expo in Istanbul

Published

on

Tüyap

Organised by Tüyap in Istanbul, ICFE 2027 expects more than 500 exhibitors and 35,000 industry professionals, offering Middle East and North Africa buyers opportunities to meet international carpet and flooring suppliers

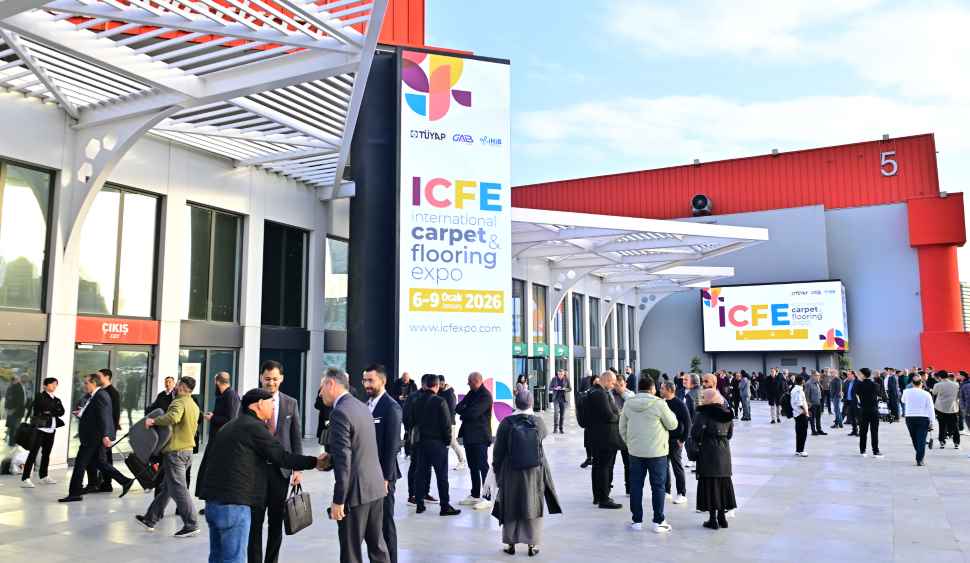
ISTANBUL, Türkiye, November 17, 2026/APO Group/ –Türkiye, a major global carpet manufacturing and exporting centre, will host the fourth International Carpet and Flooring Expo (ICFE 2027) (https://www.ICFExpo.com/en) in Istanbul from 6 to 9 January 2027. Organised by Tüyap (www.Tuyap.com.tr) Fairs and Exhibitions Organization Inc. in cooperation with the Southeastern Anatolia Carpet Exporters’ Association (GAHİB) and the Istanbul Carpet Exporters’ Association (İHİB), the event will bring international manufacturers and buyers together at the Istanbul Expo Center. Organisers expect more than 500 exhibitors and approximately 35,000 industry professionals from over 150 countries, including professional buyers from the Middle East and North Africa.


“Businesses across the Middle East and North Africa are looking for opportunities to compare products, meet manufacturers and develop supplier relationships across international markets,” said İlhan Ersözlü, General Manager at Tüyap Fairs Production Inc. “Bringing these connections together in Istanbul gives buyers and exhibitors a practical setting to explore new partnerships and understand where future trade opportunities may emerge.”

International participation expected to expand in 2027

ICFE enters its fourth edition following an event that attracted 445 exhibitors and 31,410 visitors from 127 countries in 2026. The 2027 targets point to a wider international gathering.

Manufacturers and exporters will showcase products to importers, distributors, wholesalers, retailers, architects and interior designers. The exhibition will cover handmade and machine-made carpets, rugs, textile materials, laminate and wood flooring, artificial grass and other floor coverings.

For international buyers, the event provides an opportunity to examine products from different suppliers, compare manufacturing capabilities and discuss potential commercial relationships in person.

Buyers from MENA among target markets

Professional buyers from the United Arab Emirates, Saudi Arabia and Morocco are among the international audiences expected at ICFE 2027, alongside visitors from Europe, Asia and the Americas.

For carpet and flooring businesses operating in these markets, the exhibition offers access to manufacturers and suppliers across multiple product categories. Importers and distributors can explore potential sourcing arrangements, while retailers, architects and interior designers can assess new collections, materials and design developments.

Businesses across the Middle East and North Africa are looking for opportunities to compare products

Istanbul’s location between Europe and Asia also supports the exhibition’s international business focus. Its extensive direct flight connections provide access for professionals travelling from the Gulf, North Africa and other major trading regions.

Organisers are conducting promotional activities in more than 80 countries across 6 continents. Targeted international campaigns, digital marketing and B2B matchmaking initiatives are intended to attract professional buyers and facilitate meetings with exhibitors.

Exhibition-specific customs arrangement aims to support foreign exhibitors

An exhibition-specific customs measure is also expected to support international participation at ICFE 2027.

Türkiye’s Ministry of Trade, Directorate General of Customs, has reduced the rate applied to the FOB (Free on Board) value of products brought to the exhibition by foreign exhibitors from 100% to 10% under the relevant temporary customs arrangement.

The measure applies specifically to ICFE 2027 and is intended to reduce the financial burden associated with bringing exhibition products into Türkiye.

For overseas exhibitors considering the event, the arrangement represents an additional factor in assessing the costs of participation and presenting products to potential international buyers.

Design and Industry Events Complementing Business Meetings

Alongside its commercial programme, ICFE 2027 will host industry discussions and design-focused activities.

Carpet Talks will bring industry professionals together to discuss developments in design, production, branding and the evolving carpet industry. Carpet Workshop will bring designers from different countries together to collaborate on creative projects.

These activities will complement the exhibition’s business meetings, providing manufacturers, designers and buyers with an opportunity to explore emerging approaches to carpet production and product development.

The four-day exhibition will take place at the Istanbul Expo Center in Yeşilköy from 6 to 9 January 2027. Further information is available at https://www.ICFExpo.com/en.

Distributed by APO Group on behalf of TÜYAP.


Continue Reading

Trending