Connect with us
Anglostratits

Business

Global ad market prospects downgraded by $20bn in the face of widespread disruption from trade tariffs

Published

on

WARC

Growth forecasts for advertising spend have been downgraded this year (-0.9pp to +6.7%) and next (-0.7pp to +6.3%), equivalent to a $19.8bn cut.

The risk of prolonged stagflation – and outright recession – has grown in key economies, exacerbated by new trade tariffs set to bite from H2 2025. Automakers, retailers and tech brands are most exposed.

Regulation is another headwind, with the EU tightening its stance on both Google and Apple. Outstanding US antitrust rulings against Google and TikTok also add to a climate of uncertainty for media strategists.

The global ad market is expected to be worth $1.15trn this year, an absolute rise of $72.9bn (+6.7%) from a strong 2024. Alternative modelling based on a pessimistic OECD scenario further cuts ad market growth, to +6.4% this year.

WARC Global Ad Spend Outlook 2025/26 – Q1 2025 update

27 March 2025 – A new study from WARC, the experts in marketing effectiveness, has found that global advertising spend is now on course to grow 6.7% this year to $1.15trn, a downgrade of almost one percentage point (pp) from WARC’s November forecast due to growing market volatility. A further cut of 0.7pp has been applied to 2026, downrating growth to 6.3%.

The underlying factors for these downward revisions are wide ranging, but core among them is the rising risk of stagflation – or outright recession – across major economies, compounded by heightened costs being levied on trade by the US. Tightening regulation in the European Union, squeezed margins and low business and consumer confidence are also contributing factors.

James McDonald, Director of Data, Intelligence & Forecasting, WARC, and author of the report, says: “The global ad market faces mounting uncertainty as trade tariffs, economic stagnation, and tightening regulation disrupt key sectors – leading us to cut growth prospects by $20bn over the next two years. Automakers, retailers, and tech brands in particular are now reigning in ad spend amid rising manufacturing costs and mounting supply chain pressures.

“Despite the growing volatility, digital advertising remains strong, led by three companies – Alphabet, Amazon and Meta – on course to control over half of the market in 2029. Regulatory scrutiny and uncertainty around TikTok’s future in the US further compound risks to growth, however, advertisers must be nimble in order to seize initiative in this shifting landscape.”

Three scenarios for an uncertain future

WARC’s latest global projections are based on data aggregated from 100 markets worldwide, and leverage a proprietary neural network which projects advertising investment patterns based on over two million data points. These include macroeconomic data, media owner revenue, marketing expenses from the world’s largest advertisers, media consumption trends and media cost inflation. It is believed to be one of the most comprehensive advertising market models available to the industry today.

This capability has allowed WARC to model three scenarios for this report based on differing severities of deterioration in underlying market conditions. These are as follows:

WARC’s baseline forecast, drawing from current indicators
The Organization for Economic Cooperation and Development (OECD) scenario, which assumes 10% universal trade tariffs and cuts 0.5pp from GDP in key economies over three years, as well as adding 0.4 points to inflation
A more severe case, which removes a full point from global growth aside 0.4 points to inflation over the next three year

Applying the OECD scenario to the advertising market cuts a further 0.3pp and $4bn from global growth compared to WARC’s baseline of 6.3% growth and total of $1.15trn. The Trump administration still intends to introduce new reciprocal tariffs with all trading partners on April 2nd, aside a blanket 20% hike already imposed on China and similar punitive measures pending for Canada and Mexico. This plays into a more severe scenario which, when modelled, equates to a 0.8pp downgrade in advertising growth compared to our baseline, at an extra cost of $9.5bn.

WARC believes the impacts of trade fragmentation will begin to be felt in the advertising market from the second half of this year, before becoming more pronounced during the first half of 2026.

Automotive, retail and tech sectors set to bear brunt of tariff impacts

Automotive ad spend down 7.4% this year as manufacturing stalls and key players pare back on brand building
Retailers set to lower ad spend by 5.3% as margins tighten; US retailers are vulnerable to disruption among Chinese suppliers
Ad growth set to halve among tech & electronic brands as barriers to trade impair access to components

The automotive industry contributes significantly to the revenues of leading ad agencies, spending $54.8bn last year of which more than one in five (22.5%) dollars went to premium video formats – predominantly spots. Budgets are shifting away from linear TV and towards digital platforms, however, with more than half (51.1%) of automotive spend worldwide now going to search and social media.

Major US automakers, including General Motors and Ford, have reduced their advertising budgets in recent years despite revenue growth. GM reinvests 1.8% of its sales revenue into marketing activity, down from 3.5% in 2013, while for Ford the share is just 1.2%.

Data from the European Automobile Manufacturers Association (EAMA), published this month, shows impending tariffs on Mexican, Canadian and Chinese production pose a risk to two fifths (40.7%) of the automotive industry. WARC expects a decline in ad spend among automotive brands to be close to 7.4% this year, with video formats more likely to incur larger losses.

Retail is the largest sector WARC monitors, with projected ad spend of $162.7bn this year equivalent to 14.1% of the global ad market. This total represents a fall of 5.3% from 2024 levels of spend, however, mostly reflective of the looming impacts of tariffs on supply chains. Both the OECD scenario (-5.7%) and severe case (-6.1%) paint gloomier prospects for ad spend among retailers this year.

The retail sector recorded dramatic growth last year – up 13.6% or $18.9bn – buoyed by aggressive strategies from new entrants to western markets like Temu and Shien. Our working assumption is that these companies will significantly ease advertising activity this year as trade barriers disrupt direct routes to western consumers, stymying headline growth in the retail sector.

The tech and electronics sector spent $84.3bn on advertising last year, a bounceback of 25.0% following two years of decline (due to rising interest rates affecting tech startups) which was propelled by increased demand for microchips from AI and more fluid supply chains.

WARC forecasts a 6.2% ad spend growth in this sector to $89.5bn, a downgrade from the +13.9% forecast in November in large part reflective of new tariffs targeted at semiconductors. Both the OECD (+5.8%) and severe (+4.9%) scenarios point to a further cooling in growth.

Online platforms shrug off regulatory pressures

Search to account for more than a fifth (21.7%) of the ad market, with spend rising 8.0% to $250.0bn this year despite regulatory threats
Social media – the largest single advertising medium globally – is poised to account for a quarter of all ad spend this year
Retail media set to be joint-fastest growing advertising medium this year, though trade disruption threatens ad receipts from consumer packaged goods (CPG) brands

Last week, the European Union found Apple and Google to be in breach of its Digital Markets Act (DMA), potentially costing the pair billions of dollars in fines. The EU is also pushing back on personalisation via the Digital Fairness Act, while a recent UK court ruling could allow UK consumers to opt out of personalised advertising. These developments stand to significantly impact retail, social media and the future of paid search advertising.

These developments, coupled with the US antitrust ruling against Google late last year, show a significant souring among legislative bodies against major tech firms. Ongoing uncertainty on the practicalities and likely appeals from Google and Apple, means our growth projections for the sector remain positive.

WARC projects a rise of 8.0% for paid search this year, though this is down a point from our last forecast and 1.3pp ahead of the companion OECD scenario modelled for this release. Within this, Google is expected to record an 8.5% rise in paid search revenue, while Apple’s search business, estimated to be worth $5.1bn last year per Omdia Advertising Intelligence, should grow by a similar order.

Taken together, social media companies are expected to net $286.2bn in advertising revenue this year, up 12.1% from last year and equivalent to a quarter (24.8%) of global advertising spend. Within this, TikTok (+23.6%), Instagram (+17.0%) and Facebook (+8.6%) are expected to see healthy gains, as a long tail of advertisers leverage new generative AI tools to target consumers.

Major US retailers Walmart and Costco have reportedly requested their Chinese suppliers – who make up between one third and one half of their supply chains – cut prices to ease the pressures from new tariffs on their goods. Chinese producers also account for a ‘significant’ proportion of supply chains for global pure players like Amazon, while Chinese properties targeting western shoppers – including Temu and Shien – are particularly exposed.

Money continues to flow into the retail media market, and new commerce media entrants, from the air travel and banking sectors, are boosting the sector. WARC believes that retail media will be the joint-fastest growing medium this year, at +15.4%.

This rate is ahead of the wider pure play internet market (+10.1%) and more than double the total global growth rate, resulting in retail media’s share of global spend rising to 15.5% this year – equivalent to $178.7bn. Disruption to this ecosystem could broadly dampen ad spend within the consumer packaged goods (CPG) sector, though.

Economic outlook cut across key advertising markets

US ad market expected to post a solid rise this year (+5.7%), though growth is less than half that recorded in 2024 (+13.1%)
The Chinese ad market continues to struggle with weak domestic demand; growth is set to slow to 5.3% this year and just 3.5% in 2026.
The UK, German and Japanese economies are all stalling and present a severe risk of stagflation over the forecast period

We believe the US ad market will grow 5.7% this year to $451.9bn, though this is less than half the growth rate recorded in 2024 (+13.1%). Contrary to OECD expectations for the US economy, ad market growth should accelerate in 2026, with spend rising 6.5% (+4.4% in real terms) as activity increases around the FIFA World Cup (hosted across North America) and US midterms.

China too is expected to record a slowdown in both advertising and economic growth this year when compared to 2024. Its ad market has cooled on the back of weak domestic demand, and spend is set to rise by 5.3% to $205.5bn this year compared to growth of 7.1% recorded in 2024. This year’s growth rate equates to a 3.5% rise in real terms, which lags the OECD’s expectation of 4.8% real growth in the Chinese economy (a 0.1pp upgrade on its last forecast).

Our preliminary estimate for ad market growth in the UK last year stands at +10.2%, though this is due to be confirmed next month as part of the AA/WARC Expenditure Report. The UK’s ad market is highly digital, with online ads accounting for four in five (82.6%) ad dollars. We believe the UK’s ad market will grow by 7.1% to a value of $52.6bn this year, though this is tempered to a 5.0% rise after accounting for inflation.

The outlook is tougher for Japan, where advertising spend is expected to dip by 2.0% to $40.0bn this year (-3.9% in real terms). The market is set to grow 3.3% this year when measured in local currency, demonstrating the current strength of the greenback against the yen. The OECD has downgraded its growth expectations for the Japanese economy by 0.4pp both this year and next, with economic stagnation a likelihood in 2026.

Germany’s economy is also in the doldrums, with real growth of just 0.4% expected by the OECD this year following a cut of 0.3pp from its last outlook. This sluggish growth underpins our expectations of a 2.1% fall in German advertising spend to $27.1bn this year, equivalent to a 4.1% dip in real terms after accounting for inflation.
Business

Afreximbank supports Veenocks’ US$145 million project for industrial expansion and regional growth

Published

on

Afreximbank

PPF-funded studies enabled Veenocks to broaden its medium-term regional growth plans, while a US$81.9 million senior loan supports an expansion expected to triple annual production capacity

CAIRO, Egypt, November 2, 2026/APO Group/ –African Export-Import Bank (Afreximbank) (www.Afreximbank.com) has supported the development and expansion of Veenocks Limited’s porcelain tile manufacturing plant in Sagamu, Ogun State, Nigeria, through its Project Preparation Facility (PPF) and a US$81.9 million senior term loan. The project has a total estimated cost of US$145 million.


Afreximbank and Veenocks signed a US$2 million project preparation facility agreement in August 2024 to finance technical, commercial, financial, legal, environmental and social studies needed to establish the project’s bankability.

The studies financed through the PPF, complemented by Afreximbank’s pan-African experience, enabled Veenocks to broaden its growth ambitions beyond its primary focus on the Nigerian market. This support informed the company’s plans to pursue regional opportunities over the medium term, with target markets including Togo, Benin, Burkina Faso, Niger, Cameroon, Ghana, Mauritania and Senegal.

The Bank’s US$81.9 million senior term loan supports implementation of the plant’s expansion, providing financing for investment in additional manufacturing capacity. The expansion is expected to increase the plant’s total annual production capacity from 3.3 million to 9.9 million square metres, creating a stronger production base to meet domestic demand and pursue regional opportunities.

Veenocks demonstrates how project preparation, commercial expertise and senior debt financing can support African industrial investment

The existing plant employs more than 200 people directly. The expansion is expected to create an additional 300 direct jobs, alongside indirect employment across raw material supply, logistics and distribution.

The preparation financing has been fully repaid from senior debt, completing the PPF’s funding cycle for Veenocks and replenishing capital to support further projects.

Mrs. Kanayo Awani, Executive Vice President, Intra-African Trade and Export Development, Afreximbank, said:

“Veenocks demonstrates how project preparation, commercial expertise and senior debt financing can support African industrial investment. The studies financed through Afreximbank’s Project Preparation Facility have helped strengthen the project’s bankability and broaden the company’s regional growth ambitions. Our senior debt financing supports the plant expansion needed to convert those ambitions into increased productive capacity, and stronger foundations for intra-African trade.”

Mrs. Awani added: “Full repayment of the preparation financing ensures capital is available to support more indigenous African investors and projects. This is the PPF’s revolving model in practice: the funds that have been repaid are used to support initiatives that add value to local resources and expand manufacturing.”

Mr. Adebisi Abidemi Adebutu, Group President of R28 Holdings, the parent company of Veenocks Limited, said:

“This investment represents an important step towards our ambition of building a globally competitive manufacturing business in Nigeria, producing world-class tiles to European quality standards and reducing Nigeria’s dependence on imported tiles. The PPF was instrumental in broadening our growth plans and positioning us to penetrate regional markets over the medium term. With Afreximbank’s financing, we can now deliver the expansion phase of this project. The facility will allow us to add value to Nigeria’s raw materials, create quality jobs and increase the supply of our porcelain tiles, manufactured here in Nigeria, to customers at home and across the region. Our vision is to set the global benchmark for quality in tile manufacturing and to become Africa’s first choice for porcelain tiles.”

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Energy

Energy costs, storage value and industrial competitiveness led Day 2 of C&I Energy + Storage Summit

Published

on

Energy

Energy security, industrial competitiveness and infrastructure readiness emerged as closely connected priorities, with discussions highlighting what businesses need to turn investment plans into operational gains

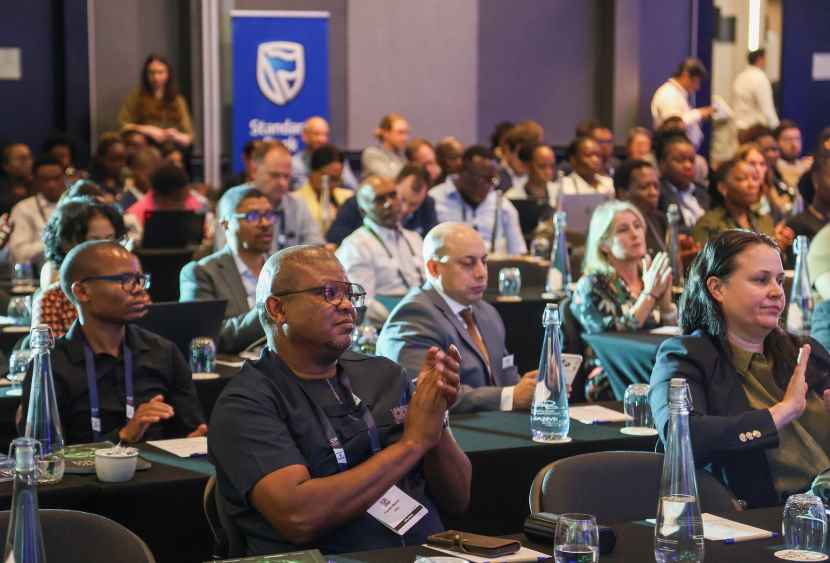
JOHANNESBURG, South Africa, November 2, 2026/APO Group/ –How can South African businesses turn energy investment into lower operating costs, stronger resilience and long-term competitiveness? This question drove the second day of VUKA Group’s (https://WeAreVUKA.com/) C&I Energy + Storage Summit in Johannesburg, with discussions examining the commercial value of storage, industrial energy strategies and the infrastructure needed to support Africa’s growing digital economy.


The programme brought together business leaders, energy specialists, financiers and public-sector representatives to address practical decisions facing commercial and industrial users, alongside the EIUG Conference, Water Security Africa and Data Centre Summit.

Energy security, industrial competitiveness and infrastructure readiness emerged as closely connected priorities, with discussions highlighting what businesses need to turn investment plans into operational gains.

Energy storage featured prominently, with panellists examining how tariff optimisation, peak shaving and renewable energy integration can strengthen its value beyond backup power. The investment case, however, needs to account for battery degradation, warranties and operational risk.

Addressing the attendees, Junaid Munshi, Group Executive: Distribution for Eskom told the audience: “For an industrial business, solar and storage can improve the energy cost position. But the opportunity extends beyond the customer’s electricity bill. Where network capacity is constrained, coordinated battery use may relieve pressure on the infrastructure serving that business and, where proven technically dependable, could defer or reduce grid investment. The asset behind your meter can therefore also become a resource beyond it.”

The asset behind your meter can therefore also become a resource beyond it

The EIUG session “Industrialisation under threat?” put changing electricity consumption under scrutiny, asking whether lower demand reflected efficiency gains or weakening industrial output. Tariffs, investment conditions and industrial growth remained central to the discussion, highlighting the need to assess energy trends against the health of the wider economy.

At the Data Centre Summit, Africa’s AI ambitions brought power availability and infrastructure readiness into focus. Discussions on grid access, wheeling and network investment highlighted the importance of planning digital growth alongside the electricity infrastructure needed to sustain it.

For businesses developing energy projects, public-private engagement sessions explored infrastructure co-investment, municipal coordination and workable wheeling agreements.

Water Security Africa reinforced the wider resource-security challenge through industrial resilience case studies, digital water technologies and lessons from case studies.

Across the discussions, the practical message was consistent: competitive businesses need more than access to technology and capital. They also need reliable infrastructure, workable commercial arrangements and coordinated delivery.

The afternoon programme translated these themes into business decisions. “The C&I energy playbook” drew together insights from across the summit, while the closing “decision clinic” addressed real project challenges, from choosing between onsite solar and wheeled power to sizing batteries and preparing projects for financing. Experts from DBSA, Standard Bank, SustainableDNA and the City of Tshwane contributed practical guidance.

Download the programme to review the full Day 2 agenda and participating speakers: https://apo-opa.co/4eEKq9a

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Business

Smarter power systems bring new demands for integration, security and infrastructure

Published

on

Digitalisation

CAPE TOWN, South Africa, November 2, 2026/APO Group/ —

Digital technologies are changing how power systems are monitored and developed, but their value depends on how effectively they can be integrated into existing infrastructure.

Utilities and energy organisations are working with a growing range of connected technologies, including smart meters, Internet of Things (IoT) devices and artificial intelligence (AI). These tools create opportunities to improve access to system data and support more informed operational decisions.


Introducing them into established power environments, however, raises questions around legacy integration, system security and the infrastructure required to support greater connectivity. Organisations must consider how new digital capabilities will interact with existing assets, processes and technology platforms.

The expansion of data centres adds another dimension to this discussion. As AI and digital services develop, the energy and infrastructure requirements associated with processing and storing data are becoming part of the wider conversation about Africa’s digital ambitions.

These interconnected issues are explored in the Industry Insights Smart Solutions Volume, published by ESI Africa as created by VUKA Group. The volume examines the opportunities and challenges associated with digitalisation, IoT, AI and smart metering in power and energy systems, alongside the industry implications of data centre growth.

Download the Industry Insights Smart Solutions Volume (https://apo-opa.co/4eePfWx)

Connecting established infrastructure with smart technology

For many utilities and infrastructure operators, digital transformation must take place alongside systems and assets already in operation. The challenge is to introduce smarter capabilities without overlooking the security, compatibility and operational considerations associated with established infrastructure.

The ESI Africa on-demand webinar Securing the bridge between legacy and smart extends this discussion by considering the relationship between legacy environments and emerging smart systems.

Watch Securing the bridge between legacy and smart on-demand (https://apo-opa.co/4ktnFsn)

Digital infrastructure also influences the extent to which African organisations can develop and deploy artificial intelligence. Data centres form part of the physical foundation required to support that ambition, connecting questions about technology development with those concerning power and infrastructure.

The webinar The digital infrastructure Gold Rush: What Africa needs to turn its AI ambition into reality considers what the continent requires to develop the infrastructure supporting its AI ambitions.

Watch The digital infrastructure Gold Rush on-demand (https://apo-opa.co/4eePbWN)

Digitalisation becomes part of the wider energy agenda

The practical impact of smart technologies reaches beyond individual devices or software platforms. Digitalisation influences how infrastructure is planned, financed, operated and secured, making it part of the broader conversation about the future of African power systems.

That conversation will continue at Enlit Africa 2027, taking place at the CTICC, Cape Town from 11 to 13 May 2027. The event provides a platform for stakeholders across the energy sector to engage with the technologies, infrastructure priorities and investment considerations affecting the industry.

Pre-register for Enlit Africa 2027 (https://apo-opa.co/4sJQbs8)

Developing investable infrastructure

Africa’s digital and energy ambitions also depend on projects moving from concept towards implementation. This requires project preparation, credible development pathways and connections between project owners and the organisations able to finance or support delivery.

The Project & Investment Network connects African infrastructure projects with investors, financiers and solution providers. ESI Africa’s African Infrastructure Elites is the Host Media Partner of the network, which invites organisations to submit projects and investors to register their interest.

Submit a project or become an investor (https://apo-opa.co/4e6vtN2)

The infrastructure discussion continues

As digital technologies develop, the relationship between smart systems, data centres and energy infrastructure will require continued industry attention. Integration, security, investment and infrastructure capacity will remain central considerations for organisations adopting connected technologies.

The forthcoming Smart Solutions & Data Centres Volume 2027 will continue examining the developments affecting smart technology and the infrastructure supporting Africa’s digital growth.

Join the Smart Solutions & Data Centres Volume 2027 waiting list (https://apo-opa.co/4ziADhn)

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Trending