Connect with us
Anglostratits

Business

Angola Strives for Energy Security through Increased Oil and Gas Production

Published

on

José Barroso

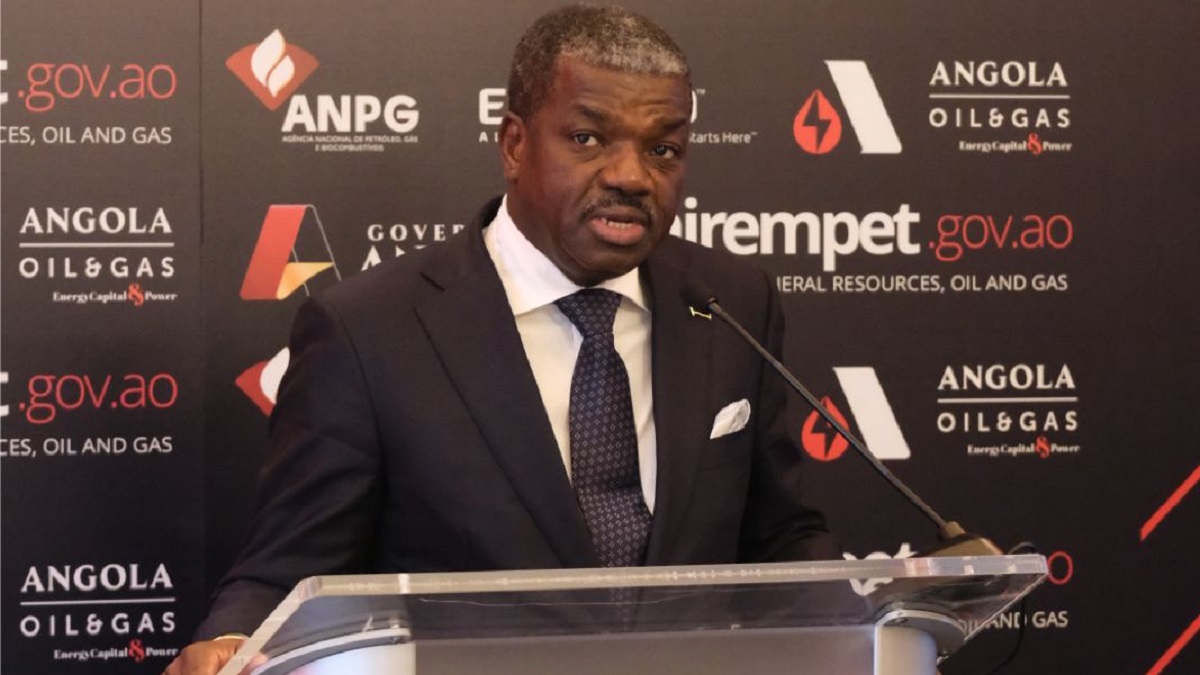
Speaking during CERAWeek in Houston, Angola’s Secretary of State for Oil and Gas José Barroso outlined the government’s long-term investment agenda

LUANDA, Angola, March 26, 2024/APO Group/ — 

Angola aims to hold and increase oil production beyond 1.18 million barrels per day (bpd) while positioning the gas sector to account for 25% of the country’s energy needs by 2025. To achieve this, government is inviting investment into exploration and production, with industry reforms guaranteeing both a competitive and stable investment environment.

Speaking at the CERAWeek conference in Houston this week, Angola’s Secretary of State for Oil and Gas José Barroso outlined the government’s vision to achieve energy security through oil and gas production. Barroso announced that the government will continue to promote investment opportunities through the continuous running of bid-rounds offering exploration licenses to qualified oil and gas companies while maintaining a robust outreach at major international oil and gas events and Angola’s premier industry event – the Angola Oil & Gas (AOG) conference, which takes place this year on October 2-4 in Luanda.

Organized by Energy Capital & Power, AOG is the largest oil and gas event in Angola. Taking place with the full support of the Ministry of Mineral Resources, Oil and Gas; the National Oil, Gas and Biofuels Agency (ANPG), the downstream regulator IRDP, national oil company Sonangol and the African Energy Chamber.

Industry Reforms Aim to Bolster Production

Since 2017, Angola has been undertaking aggressive industry reforms to ensure a transparent and competitive oil and gas market. The country introduced a six-year licensing round in 2019 which guarantees yearly investment opportunities in exploration for foreign players. The most recent of these – a 12-block tender covering blocks in the Lower Congo and Kwanza Basins – featured 53 bids, underscoring the scale of interest in Angolan oil and gas. Going forward, Barroso explained that the country’s national regulator and concessionaire, the National Oil, Gas & Biofuels Agency (ANPG), will continue to aggressively promote the industry, pushing bid rounds in line with national production targets.

Meanwhile, Barroso stated that Angola offers regulatory flexibility with regards to oil and gas agreements. In addition to production sharing agreements under the six-year licensing round, the country introduced a risk-reducing alternative in 2020, enabling the awarding of risk service contracts when the public bid process is unlikely to succeed. A permanent offer program initiated in 2021 also enables the ANPG to negotiate new contracts with operators without offering a bid round. Additional reforms include a Tax Benefits Code enacted in 2022, creating incentives for oil companies.

According to Barroso, the government is open to discussing terms and finding a balanced agreement that provides the right returns for investors. He added that the government is open to license renewal, thereby ensuring a strong and long-term relationship between oil companies and the state.

Leveraging Gas to Unlock Economic Growth

With over 11 trillion cubic feet of proven natural gas reserves, Angola plans to leverage investments in the sector to bolster industrialization and energy access. Barroso said that natural gas is of uttermost importance for the country, serving as a catalyst for the energy transition as well as economic growth.

Currently, LNG production is declining by 10-15% per year. However, upstream developments, including the Quiluma and Maboqueiro (Q&M) gas fields – set to start production in 2026 -, stand to reverse this trend. Q&M represents the country’s first non-associated gas development and will supply feedstock for the Angola LNG project. New investments in the sector, according to Barroso, will support industrialization by supplying gas for fertilizer plants, steel plants and power generation.

The government introduced a legal framework for gas in 2018 – Presidential Decree No. 7/18 – providing attractive terms and ensuring transparency within the sector. Now, Angola is inviting foreign investors to develop the market.

Angola’s 2050 Vision Prioritizes Diversification

The Angolan government approved the strategy for Vision 2050 in 2023 – a strategic plan for the country’s long-term economic growth. Vision 2050 aims to transform Angola from an oil-driven economy by creating investment opportunities in myriad economic sectors. Over $960 billion in investment is targeted across the economy under Vision 2050, with 80% of this raised through foreign direct investment. Centered on diversification, the strategy aims to more than double the non-oil sector’s long-term growth.

However, oil remains an integral part of the country’s economic agenda. According to Barroso, with oil accounting for over 30% of GDP, 70% of government revenue and 90% of exports, the plan ensures oil and gas production remains a top priority for the next ten years. Government aims to maintain or increase production above 1.1 million bpd while diversifying the economy through investments. This, in turn, creates opportunities for players within the oil sector as well as across the entire economic spectrum. As such, the government’s pro-growth approach to investment is poised to unlock high returns for many years to come.   

Join the AOG 2024 conference today and capitalize on the opportunities the growing Angolan economy has on offer. Covering the entire oil and gas value chain as well as associated sectors such as infrastructure, manufacturing, transport and ICT, the event connects companies to opportunities. Visit www.AngolaOilAndGas.com for more information.

Distributed by APO Group on behalf of Energy Capital & Power.

Business

World’s biggest brands increasingly spend less of their sales revenue on advertising – except consumer goods giants

Published

on

15 October 2026 – The world’s largest brand owners are, on average, spending a diminishing share of their sales revenue on advertising – with the notable exception of consumer goods companies, finds WARC Media.

In its latest “Global Ad Trends report: The cost of being seen”, WARC Media examines shifts in advertising intensity among 25 of the world’s largest advertisers, to better understand the extent to which big brand-owners are driving growth in the global market.


Alex Brownsell, Head of Content, WARC Media, says: “The global ad market is expanding rapidly, but companies from Meta to Mastercard and McDonald’s are allocating a diminishing share of revenue to advertising. Only consumer goods companies – buffeted by softening sales growth and with trade budgets moving into measured media – are increasing ad intensity.

“This underlines what we’ve previously reported – namely that we are operating in a two-speed marketplace. The expansion of digital platform spend by smaller businesses and cross-border e-commerce sellers is by far outpacing growth in ad investment by big brands. This has major implications for the ecosystem of agencies and vendors operating in the enterprise market.”

Key findings outlined in WARC’s “Global Ad Trends: The cost of being seen” are:

Advertising intensity is changing

WARC Media forecasts global ad spend to grow 11.9% this year to $1.34trn. Adjusted for inflation, this is an increase of 61.3% over the last 25 years, fuelled by new channels like retail media and platform advertising that didn’t exist a decade ago.

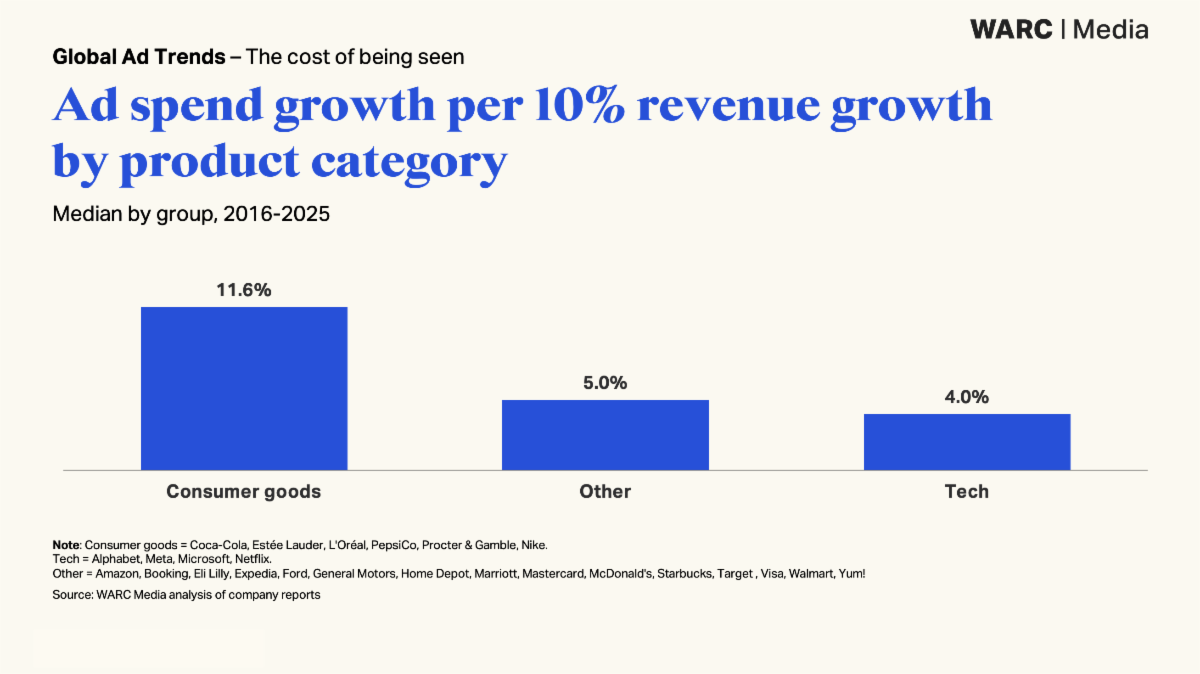
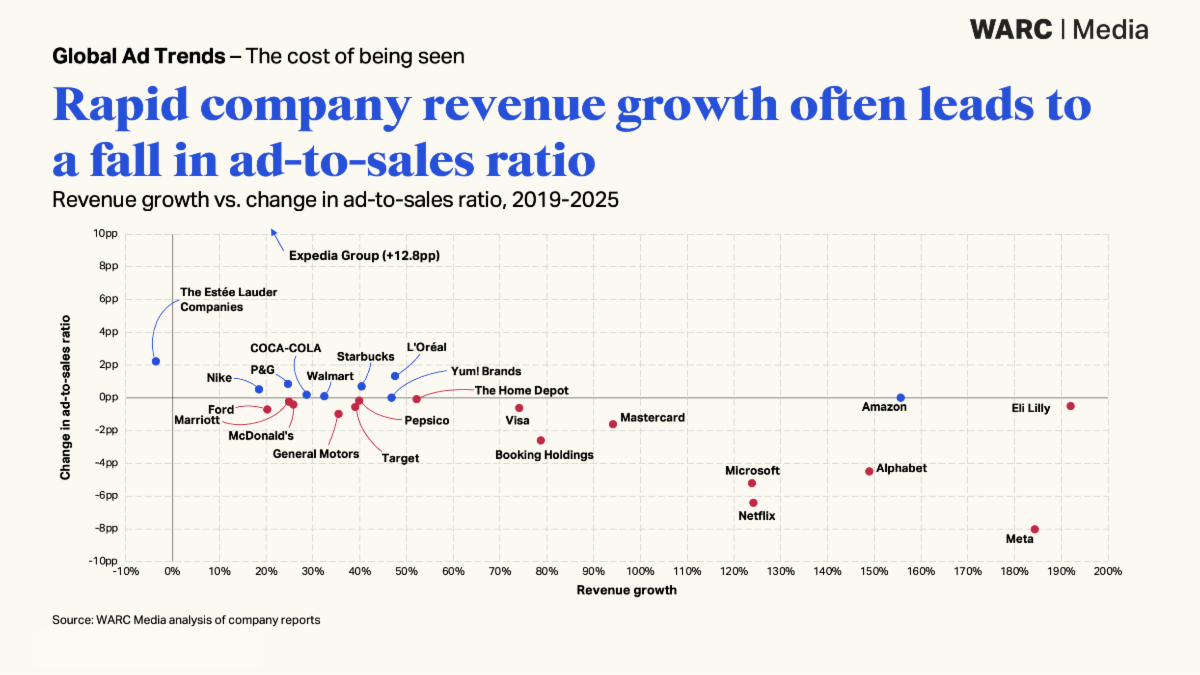
However, advertising intensity has declined in recent years. Across 25 large US-based advertisers, the combined ad-to-sales ratio, a measure of how much companies spend relative to their size, fell from 6.1% in 2019 to 5.5% in 2025. This does not represent a retreat from advertising: their combined ad spend rose 56%, but budgets have not kept pace with rising revenue, which rose by 73%.

Big Tech companies are driving the downward trend

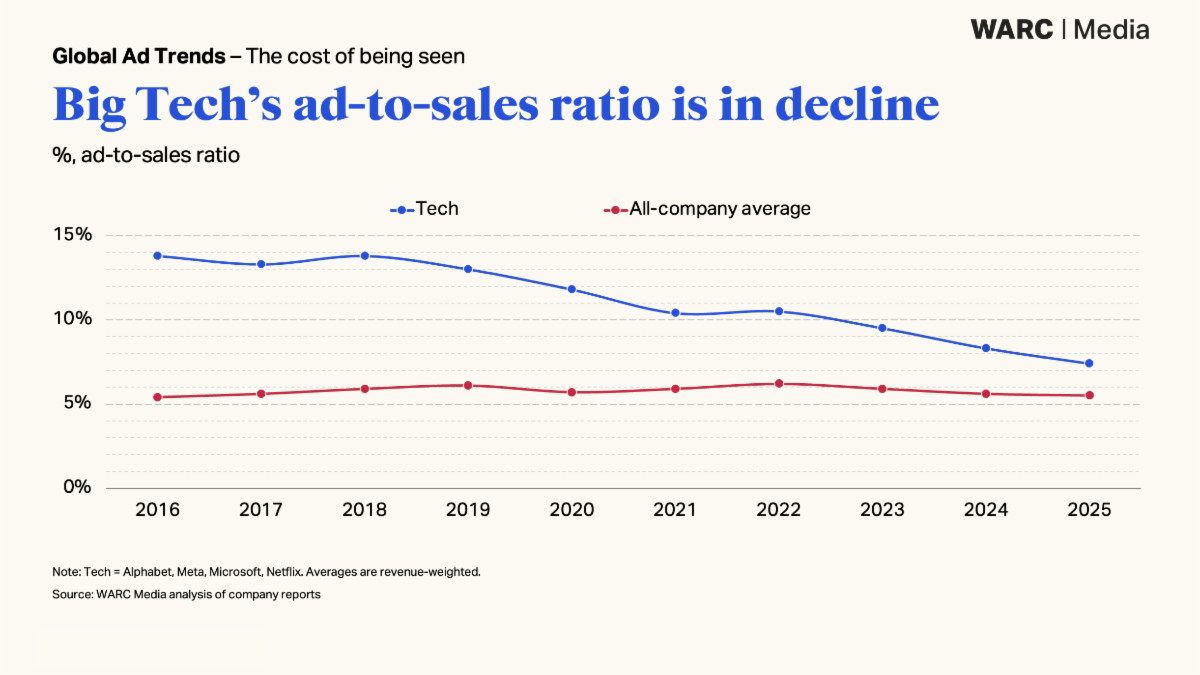
Alphabet, Meta, Microsoft and Netflix’s combined ad-to-sales ratio fell from 13.0% to 7.4% between 2019 and 2025, while their combined revenue rose 146%, from $379bn to $931bn. Had they maintained their 2019 ratio, these brands would have spent $121bn in 2025 – $52bn more than they actually did.

Consumer goods brands are an outlier, with intensity rising

The six biggest consumer goods brands analysed by WARC Media – Coca-Cola, Estée Lauder, L’Oréal, Nike, PepsiCo and Procter & Gamble – moved the other way. Five raised their ad-to-sales ratios between 2019 and 2025; PepsiCo’s was broadly flat.

Softening sales growth pushed the combined consumer goods ad-to-sales ratio from 11.6% in 2023 to 12.5% in 2025, with budget shifts into areas like retail media further lifting ad intensity. From 2019 to 2025, their collective ad spend grew 36%, outpacing 29% revenue growth.

Non tech companies and consumer goods brands are less consistent

The remaining 15 advertisers – neither tech nor consumer goods – tell a less consistent story. Weighted by revenue, the group’s average ratio was flat to slightly up, yet 10 of the 15 individual companies cut their ratios between 2019 and 2025:


  • Automotive: Ford (2.3% to 1.6%) and General Motors (2.7% to 1.7%).
  • Payments: Visa (4.8% to 4.2%) and Mastercard (5.6% to 4.0%).
  • Restaurants and retail: McDonald’s (1.7% to 1.3%) and Target (2.0% to 1.4%).
  • Also falling: Marriott, Booking Holdings, Eli Lilly and The Home Depot.
  • Amazon and Yum! Brands were broadly flat.
  • Three companies saw their ad-to-sales ratios rise: Walmart, Starbucks and Expedia.

The three forces behind the ratio split

There are three main forces that cause changes to ad intensity:

  1. Weak sales. Brands maintaining ad spend in adverse market conditions, with sales going into reverse, may see ad intensity rise.
  2. Budgets changing lines. Money that used to sit with sales teams as trade and shopper spend is moving into retail media, and so into the advertising line.
  3. Owning versus renting attention. Companies that own an audience, like Alphabet and Meta, have an opportunity to grow without renting attention.

WARC Media subscribers can read the report in full. A WARC podcast on the findings outlined in the report will be available from 17 November.


Global Ad Trends, part of WARC Media, is a quarterly report which draws on WARC’s dataset of advertising and media intelligence to take a holistic view on current industry developments.


Continue Reading

Business

Senegal Opens 104 Blocks to Investors, Targets New Upstream Contracts

Published

on

Senegal

Senegal’s Minister of Energy and Petroleum, El Hadji Abdourahmane Diouf, told AEW delegates that the country is seeking partners for its remaining acreage, the Yakaar-Teranga gas project and downstream developments

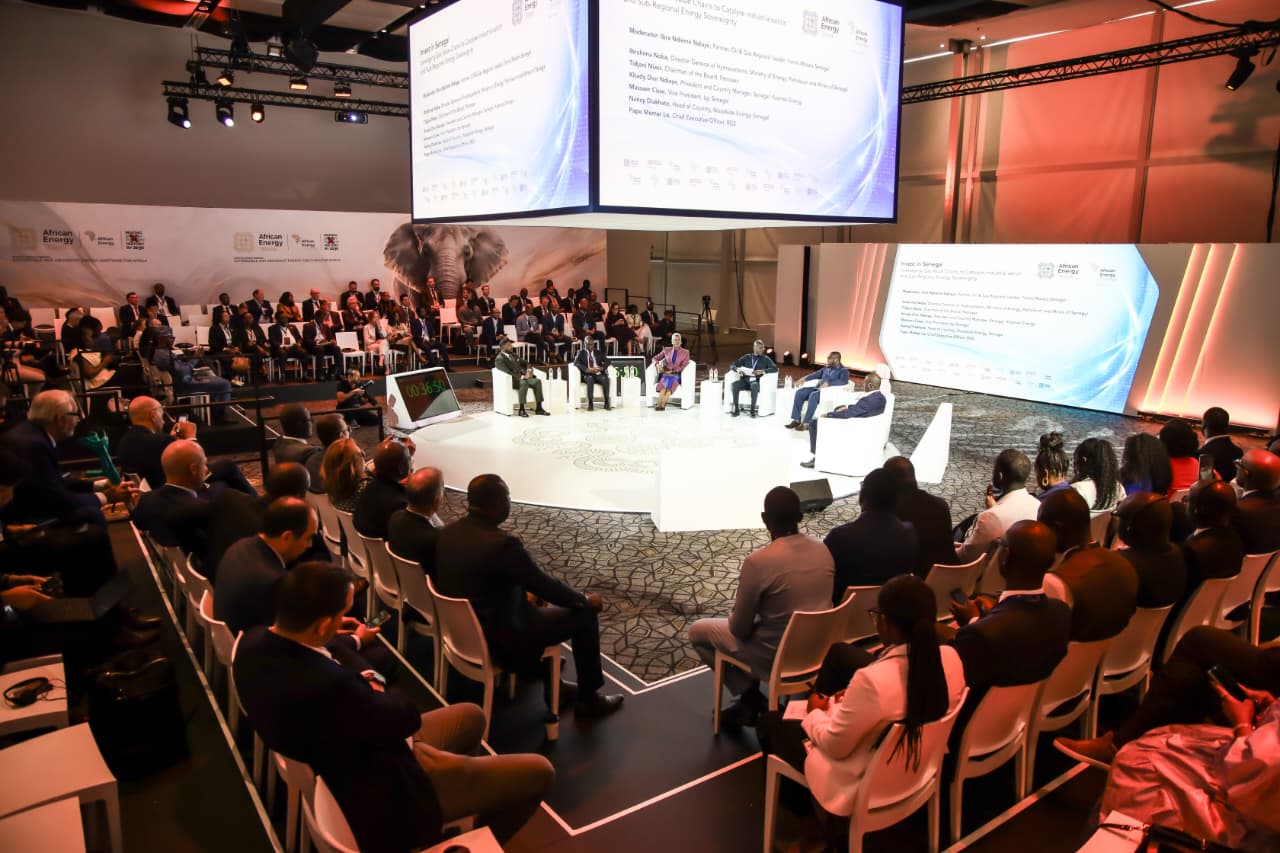
CAPE TOWN, South Africa, October 15, 2026/APO Group/ –Senegal has 104 oil and gas blocks available to investors and is seeking new upstream contracts to accelerate exploration and production, El Hadji Abdourahmane Diouf, Minister of Energy and Petroleum, said at African Energy Week 2026 in Cape Town. Of the 113 blocks in Senegal’s reorganized acreage, four are under contract and five have been allocated to Eni for studies, leaving substantial opportunities for international and regional operators.


“We hope to sign a number of contracts…” he said, adding that the country aims to “show investors that Senegal remains the country it has always been: open, hospitable and respectful of international procedures.”

Senegal reorganized its upstream acreage into 113 blocks in March 2026, comprising 65 onshore and 48 offshore blocks. The country also signed an agreement with Eni to assess the oil and gas potential of five offshore blocks.

Our strategy is to build the value chain from the well to the factory, with gas at the heart of our industrial ambition

Beyond new exploration acreage, Senegal is seeking partners to develop the Yakaar-Teranga gas project alongside national oil company Petrosen. Petrosen took full control of the project after Kosmos Energy withdrew in April 2026. Minister Diouf said Yakaar-Teranga will supply gas for power generation, industrial applications including fertilizer production, and exports. Advancing the project will require a coherent development structure, credible buyers and a clear investment program.

“Our strategy is to build the value chain from the well to the factory, with gas at the heart of our industrial ambition,” he said.

Downstream, Minister Diouf pointed to a planned second refinery that will process Sangomar crude, with investment estimated at $2 billion to $3 billion. The Société Africaine de Raffinage (SAR) and Turkey’s Yamata signed a Memorandum of Understanding for the four-million-ton-per-year refinery in New York on September 23, 2026. Minister Diouf said the project opens further opportunities in storage, logistics, distribution and petrochemicals.

Minister Diouf invited investors to examine Senegal’s data, work with its technical teams and bring proposals backed by the capacity to invest and execute. He also asked partners to involve Senegalese companies and skills from the outset, with support from the national local content monitoring committee.

“Capital must earn a return. Senegal must gain a stronger economy. The partnership we seek must serve both purposes,” he said.

According to Minister Diouf, Senegal hopes to expand the MSGBC alliance beyond its five host countries of Senegal, Mauritania, The Gambia, Guinea-Bissau and Guinea, but he did not specify which countries are being considered.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Energy

Africa shifts from carbon market potential to delivery as Carbon Markets Africa Summit (CMAS) 2026 opens in Kigali

Published

on

Carbon Markets Africa Summit

African governments, development finance institutions and global climate leaders call for high-integrity markets, investment-ready projects and greater value for African communities

KIGALI, Rwanda, October 15, 2026/APO Group/ –Africa must move beyond carbon market potential towards delivery, building high-integrity, investable markets that attract long-term capital while protecting national climate priorities and ensuring greater value reaches African countries and communities.


That was the central message from the opening keynote sessions of the Carbon Markets Africa Summit (CMAS) 2026 in Kigali, Rwanda, where policymakers, investors, project developers, development finance institutions and international climate organisations gathered to accelerate Africa’s participation in global carbon markets.

Representatives from 45 countries, including 21 African nations, are participating in the summit, where discussions have shifted decisively from market readiness to implementation, investment and transactions.

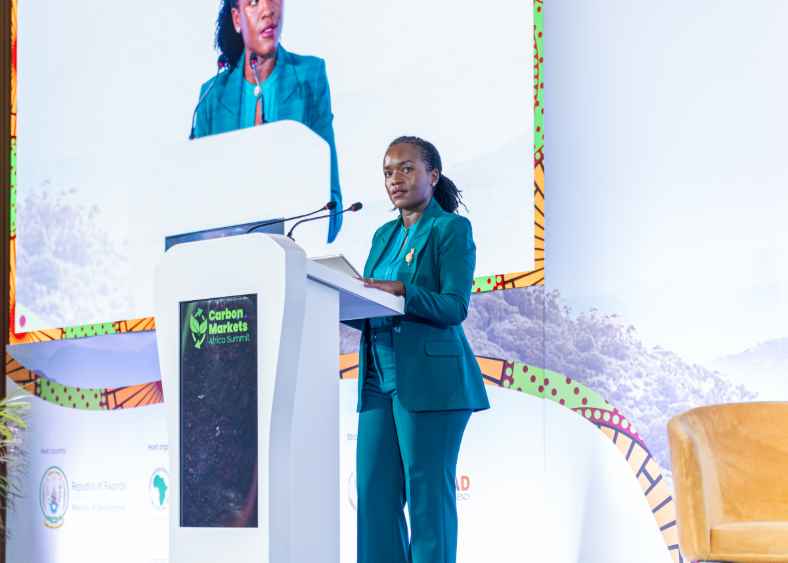
Officially opening the summit, Hon. Dr Bernadette Arakwiye, Rwanda’s Minister of Environment, said Africa’s carbon markets must be shaped by African priorities and deliver tangible benefits for the continent.

“The question before us is therefore no longer simply whether Africa is ready. It is whether we can deliver at scale, with integrity and with innovation.”

Minister Arakwiye said progress is already evident as African countries establish carbon market frameworks, grant authorisations, sign bilateral agreements and develop projects. However, she cautioned that carbon finance remains concentrated in a relatively narrow range of project types. She called for diversification into renewable energy, electric mobility, sustainable waste management, industrial decarbonisation, agriculture and landscape-scale nature-based solutions.

Minister Arakwiye identified three priorities for scaling Africa’s carbon markets: accessible methodologies suited to African contexts; project preparation and readiness finance; and long-term demand at fair value.

“Trust is the currency of this market,” she said. “To our buyers and investors, I say: look closely at these efforts. Reward them with long-term demand, fair prices and patient capital.”

From potential to execution

The call for delivery was echoed by Hon. Hamad Yusuf Masauni, Tanzania’s Minister of State in the Vice President’s Office responsible for Union Affairs and Environment, who said the continent now has an opportunity to reposition itself in global carbon markets.

“For too long, Africa has been spoken about as a continent of potential. At the Carbon Markets Africa Summit, we declare that the era of potential is giving way to the era of execution.”

Minister Masauni stressed the importance of moving high-quality, bankable projects through to issuance and offtake rather than focusing solely on the size of project pipelines.

“Credibility is built one verified tonne, one closed deal and one community that sees real benefit at a time.”

The importance of ensuring value reaches communities was also central to remarks from Maxwell Gomera, UNDP Resident Representative in South Africa and Director of the Africa Sustainable Finance Hub.

Gomera called for market infrastructure capable of carrying value “from the buyer all the way to the farmer”, backed by strong community rights, enforceable benefit-sharing, early-stage finance and partnerships focused on delivery.

Africa urged to compete on integrity, not price

For too long, Africa has been spoken about as a continent of potential

Speakers also stressed that Africa’s competitive advantage should be the quality and integrity of its carbon assets rather than simply offering the lowest-priced credits.

Perumal Arumugam, Manager of Markets and Non-Markets and Stakeholder Interaction at UN Climate Change (UNFCCC), said Africa should move beyond asking how it can participate in carbon markets and instead consider how carbon markets can advance African priorities.

“Africa should not compete simply by offering the cheapest tonnes. Africa should compete by offering credible and creditable tonnes, a sustainable tonne, and a tonne that the world can trust.”

He said success should ultimately be measured not only in credits issued, but in investment mobilised, mitigation unlocked, value reaching communities, stronger economies and African countries retaining control over their climate transitions.

Speaking on behalf of AUDA-NEPAD, Esterine Fotabong similarly called for African countries to scale carbon markets on their own terms, supported by predictable authorisations, functioning registries and credible monitoring, reporting and verification systems.

She also highlighted the need to build greater African capacity in validation and verification and expand access to carbon finance in sectors such as agriculture.

Global demand will reward quality

Representing the European Commission, Lukas Visek, Deputy Head of the Directorate-General for Climate Action Task Force for Carbon Pricing and Carbon Markets, signaled future European demand for international carbon credits while stressing that quality requirements would be stringent.

“Additionality and permanence are not negotiable,” he said. “Quality, however, will be rewarded.”

The message to developers was clear: projects being developed for future international demand will need robust data, genuine additionality, strong community participation and demonstrable alignment with national and global climate goals.

Turning carbon projects into investable assets

The summit’s opening programme then moved directly from policy to capital and deal flow, with leaders from the African Development Bank (AfDB), Development Bank of Southern Africa (DBSA) and Kigali International Financial Centre (KIFC) examining the practical barriers preventing more investment from reaching African projects.

Policy certainty, early-stage project preparation, bankable pipelines, robust governance and appropriate financial risk-sharing were identified as critical to accelerating capital flows.

Dr Anthony Nyong, Director of Climate Change and Green Growth at the African Development Bank, emphasised that carbon markets should ultimately be viewed through the lens of African development.

“We don’t have carbon projects. We have development projects.”

Greg Fyfe, Chief Investment Officer at DBSA, highlighted the catalytic role development finance institutions can play by supporting project preparation, providing patient capital and absorbing risks private investors are unable to take.

The opening sessions underscored a decisive shift in the African carbon market conversation: from readiness to delivery, from fragmented projects to investable pipelines, and from selling credits to building markets capable of delivering lasting economic, social and climate value.

As CMAS 2026 continues in Kigali, attention now turns to connecting credible African projects with buyers and capital, unlocking transactions and ensuring Africa plays a leading role in shaping the next generation of global carbon markets.
Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Trending