Connect with us
Anglostratits

Business

The Role of Algeria, Egypt, and Nigeria in Africa’s Search for European Gas Market Share (By NJ Ayuk)

Published

on

European Gas Market

This search has drawn attention to a number of African gas projects that are likely to help Europe in the future

JOHANNESBURG, South Africa, August 4, 2022/APO Group/ — 

By NJ Ayuk, Executive Chairman, African Energy Chamber (www.EnergyChamber.org)

The curtailment of Russian natural gas deliveries is a source of anxiety for the European Union — and rightly so, given that the bloc has been far too dependent for far too long on Gazprom, a majority state-owned Russian company that serves as a de facto instrument of policy for the Kremlin. But this anxiety is also a source of potential for African gas producers, as it’s driving European consumers to look elsewhere for fuel.

This search has drawn attention to a number of African gas projects that are likely to help Europe in the future, particularly as the EU looks to make a permanent shift away from dependence on Russian gas. Both Tanzania and Mozambique, for example, are planning large-scale offshore development schemes that will support liquefied natural gas (LNG) plants capable of sending large volumes of fuel to European markets toward the end of the decade. The Republic of Congo hopes to fast-track a medium-scale modular project that may begin production a few years sooner. Meanwhile, there are other greenfield initiatives under discussion in Mauritania and Namibia, and several international majors have banded together to bring new fields online to facilitate LNG production in Angola.

These projects are all exciting and new.

For the time being, though, they’re not going to have much concrete impact on the European energy balance.

That’s because they can’t.

They’re not ready yet.

The Timeline for African Gas

These projects have great potential, but their potential is yet to be realized. In countries such as Tanzania and Mozambique, we know the gas is there because international oil companies (IOCs) have seen it, measured it, analyzed it, and tested it; they just haven’t time yet to drill all the development wells and build all the infrastructure needed to extract it and turn it into LNG for export. In the Republic of Congo, we know the gas is there, and the Italian major Eni is already extracting it — just not on a scale that can immediately serve buyers in Europe or local power plants.

These projects have great potential, but their potential is yet to be realized

These obstacles can be overcome. The gaps can be filled in, the wells drilled, the pipelines connected, the gas liquefaction plants constructed, the tankers chartered. But it will take time — years, not weeks or months — to arrange the necessary financing, sign the necessary contracts, gather the necessary materials, and so on.

This doesn’t mean, though, that Africa can’t play a role in helping the EU shed its reliance on Russian gas in the short term. Absolutely not!

The Importance of Existing Capacity

But much of that assistance, at least in the short term, is going to come from existing capacity, that is, from the places in Africa that are already turning out gas for export to Europe. Above all, it’s going to come from these three countries: Algeria, Egypt, and Nigeria, which will account for fully 80% of African gas yields between 2022 and 2025, according to the African Energy Chamber’s State of African Energy Q2 2022 Report, drawn up in consultation with Rystad Energy. (Algeria, Egypt, and Nigeria will also account for about 60% of the continent’s total LNG production capacity during the same period, even as construction moves ahead on new facilities, the report says.)

These three states are already known to be the largest gas producers in Africa. According to the 2022 edition of BP’s Statistical Review of World Energy, they accounted for just a bit over 83% of the 257.5 billion cubic meters (bcm) of gas extracted in Africa in 2021 (for context, that’s roughly the equivalent of all of the gas consumed by Iran in one year), with Algeria contributing 100.8 bcm (or more than 39% of the total), Egypt 67.8 bcm (more than 26%) and Nigeria 45.9 bcm (nearly 18%).

What’s more, they also account for the vast majority of Africa’s gas liquefaction capacity of about 75.3 million tonnes per annum (mtpa), with Algeria contributing 29.3 mtpa, Nigeria 22.2 mtpa, and Egypt 12.2 mtpa. Algeria and Egypt have the only operational LNG plants in North Africa, while Nigeria is home to a plant that makes up nearly 66% of sub-Saharan Africa’s total LNG production capacity of 33.8 mtpa.

Algeria, meanwhile, doesn’t just have LNG; it also has pipelines. It’s already using two of them — the Medgaz and TransMed systems — to pump fuel directly to Spain and Italy across the floor of the Mediterranean Sea. Together, these two pipes are capable of handling up to 40 bcm per year of gas.

The good news is that Algeria, Egypt, and Nigeria are already supplying a good bit of the gas that Europe has been using to supplement Russian supplies. Even better, they also have enough spare capacity that their plans for raising production within the next few years are realistic.

Shows of confidence

Italy’s Eni — and the Italian government, which has a controlling share in the company — is equally confident in these countries’ potential to help meet European gas needs, as evidenced by the decision to turn to Algeria and Egypt in the search for alternatives to Russian gas. Both Italian government officials and Eni executives have traveled to Egypt and Algeria since Russia’s invasion of Ukraine in late February to negotiate and sign new supply deals.

Likewise, French oil major TotalEnergies recently extended its commitment to a project in Algeria’s North Berkine basin, partly with the aim of finding ways to export associated gas from its oil fields to Europe. They had good reasons to make these decisions — and good reasons to expect them to pay off in the near term!

It’s worth noting, of course, that Africa can help compensate for some of the difference and not all. It can’t serve as a substitute source for the entire volume of 155 bcm that Russia delivered to the EU in 2021! But it can play a key role in this process — and it doesn’t have to wait to start doing so.

Distributed by APO Group on behalf of African Energy Chamber.
Business

SLB commissions new fluids systems plant in Pemba to support Mozambique’s offshore energy development

Published

on

Mozambique

New facility expands in-country drilling and completion fluids capability, advancing the next phase of SLB’s growth in Mozambique

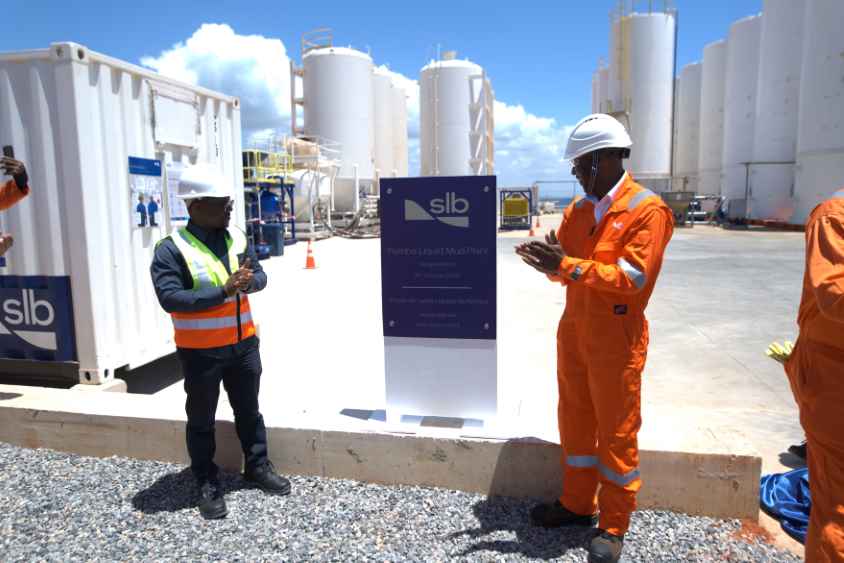
PEMBA, Mozambique, October 9, 2026/APO Group/ –SLB (NYSE: SLB) (www.SLB.com) announced the opening of a new fluids systems plant in Pemba, Mozambique. The new facility strengthens in-country capacity to prepare, store and deliver drilling and completion fluids for offshore operations, reinforcing the infrastructure needed as Mozambique’s offshore activity grows and its role as a strategic energy hub for East Africa continues to expand.

The commissioning of the plant, also known as a liquid mud plant, coincides with SLB marking 70 years of operations in Mozambique. It reflects the company’s long-term commitment to investing in people, infrastructure and capability that support the country’s long-term offshore energy development plans.


With an initial storage capacity of 21,000 barrels, the liquid mud plant provides a scalable platform for future growth, supporting multiple customers and rising offshore activity while improving logistics and enhancing operational flexibility.

As SLB marks 70 years in Mozambique, this investment reflects our confidence in the country’s future and our commitment to supporting its energy ambitions

“As SLB marks 70 years in Mozambique, this investment reflects our confidence in the country’s future and our commitment to supporting its energy ambitions,” said Miguel Baptista, Central, East and Southern Africa, Managing Director, SLB. The new liquid mud plant strengthens local energy infrastructure, expands opportunities for local content development, and enhances our ability to support customers as they deliver some of Africa’s most significant offshore energy resources.”

The liquid mud plant project was delivered with strong local participation and that momentum is expected to continue into operations. During project delivery, more than 100 jobs were created in Pemba with nationals representing 80% of the workforce, reflecting a focus on building local capability.

The project was delivered with a strong focus on safety, operational integrity, and quality, achieving more than 67,000 hours worked without a recordable safety incident.

This key infrastructure strengthens SLB’s ability to support consistent service quality and enhance supply chain readiness for increasing offshore activity across Mozambique, supporting customers execute safely and efficiently while developing local skills and expertise.

Key Points:

  • SLB has commissioned a new fluids system plant in Pemba, expanding in-country drilling and completion fluids capability for offshore operations.
  • With an initial storage capacity of 21,000 barrels, the facility provides a scalable platform to support growing offshore activity in Mozambique.
  • The investment marks the next phase of SLB’s growth in Mozambique, strengthening local capability and supporting long-term offshore energy development.

Distributed by APO Group on behalf of SLB.


Continue Reading

Business

South African Energy Storage Association (SAESA) welcomes 4,600 MW battery storage prioritisation and calls for integrated energy planning

Published

on

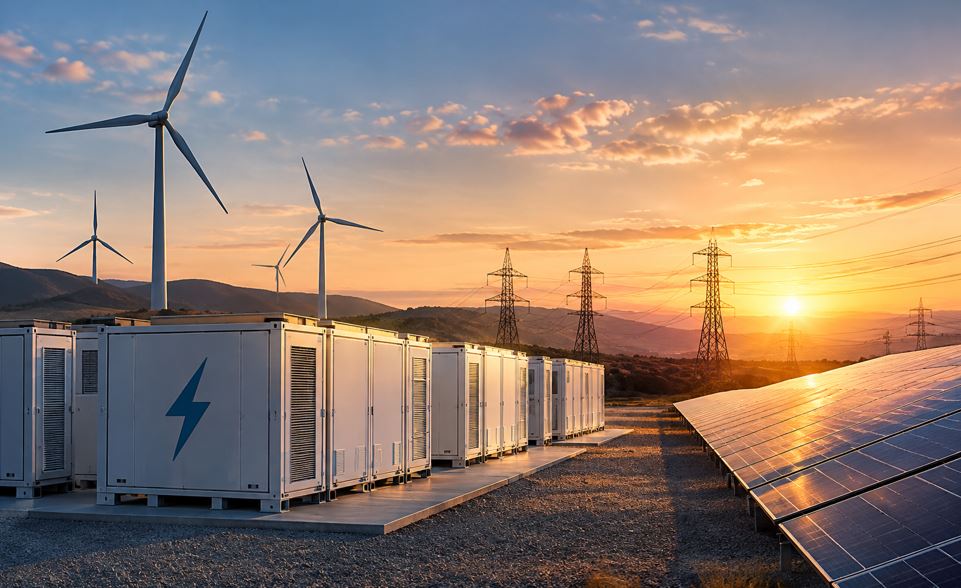
Battery energy storage systems (BESS) are becoming critical system infrastructure, supporting flexibility, reducing avoidable curtailment, shifting energy into periods of demand and strengthening security of supply

JOHANNESBURG, South Africa, October 9, 2026/APO Group/ –The South African Energy Storage Association (SAESA) (www.SAESA.org.za) welcomes the prioritisation of 4,600 MW of battery energy storage under the first Integrated Resource Plan (IRP) 2025 Section 34 determination.


The timing is significant. Recent Integrated Energy Plan (IEP) modelling and assumptions discussions highlighted a fundamental shift that South Africa’s energy planning now needs to capture: we cannot plan the future power system by counting megawatts of generation alone.

We must plan for when energy is available, where it is available, how it moves through a constrained grid and how it is stored and dispatched when the system needs it most.

The announcement reinforces that shift. Battery energy storage systems (BESS) are becoming critical system infrastructure, supporting flexibility, reducing avoidable curtailment, shifting energy into periods of demand and strengthening security of supply.

For SAESA, the message for the IEP is clear: storage, flexibility and system services must be modelled as integral components of South Africa’s future electricity architecture, with their contribution considered from the outset of generation planning.

“The IEP must plan the power system we are becoming, not simply model the power system we have inherited,” says SAESA.

The IEP must plan the power system we are becoming, not simply model the power system we have inherited

Partnership with C&I Energy + Storage Summit

SAESA is an association partner of the C&I Energy + Storage Summit, created by VUKA Group, taking place on 28–29 October 2026 at The Maslow Hotel, Sandton, Johannesburg.

The summit brings together commercial and industrial energy users, project developers, financiers, regulators and solution providers to explore practical approaches to energy security, procurement and storage deployment.

For businesses assessing how storage can support their operations, the event offers an opportunity to meet SAESA and engage with the wider energy community on the decisions shaping South Africa’s evolving electricity system.

Commercial and industrial energy decision-makers are invited to apply to attend as hosted buyers. Qualifying buyers receive complimentary summit access and curated opportunities to engage with industry partners.


Meet SAESA at C&I Energy + Storage Summit: Join the Hosted Buyer Programme

The Hosted Buyer Programme connects commercial and industrial energy decision-makers with solution providers shaping South Africa’s evolving private energy market.

Qualified energy buyers receive complimentary access to the summit and curated engagement with industry partners exploring energy procurement, storage deployment and project development.

Apply for the Hosted Buyer Programme (https://apo-opa.co/4ehLijJ)

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Business

Afreximbank welcomes launch of Africa Credit Rating Agency as an important step in strengthening Africa’s financial architecture

Published

on

Expanding credible rating coverage can improve the information available to investors and support the development of deeper domestic and regional capital markets

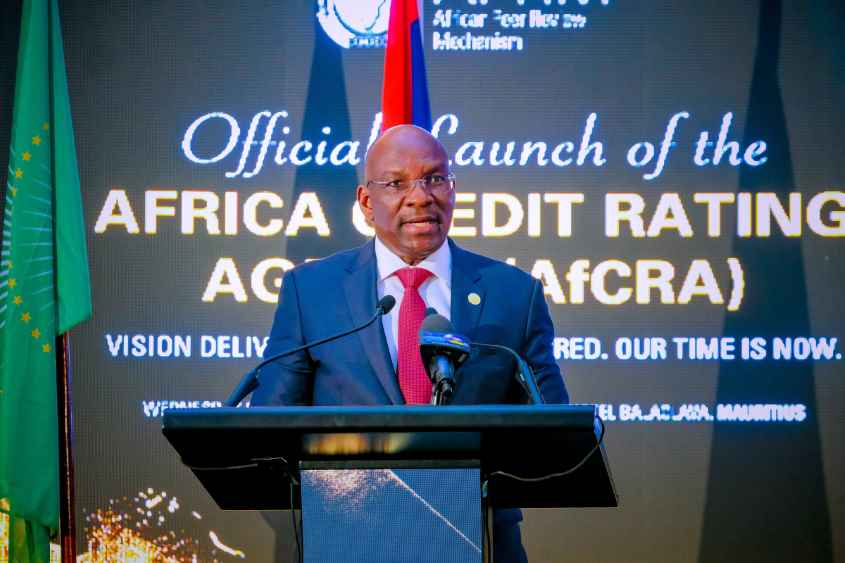
PORT LOUIS, Mauritius, October 8, 2026/APO Group/ –African Export-Import Bank (Afreximbank) (www.Afreximbank.com) welcomes today’s launch of the Africa Credit Rating Agency (AfCRA), an important milestone in strengthening Africa’s financial architecture and expanding the continent’s capacity to generate credible, independent analysis of African credit risk.


Credit ratings play an important role in determining access to capital, influencing investor perceptions and shaping the cost at which governments, institutions and businesses can finance development. It is therefore essential that assessments of African credit risk are independent, rigorous and evidence-based, while reflecting a complete understanding of the structures, institutions and economic realities being assessed.

The establishment of AfCRA adds an important African-led source of credit opinion to the market. Its value will not be measured by whether it produces more favourable ratings, but by the credibility of its analysis, the quality of its data and transparency of its methodology, and its ability to deepen understanding of African sovereigns, sub-sovereigns and corporate credit.

This is particularly important given that many African issuers remain unrated, while local-currency and sub-sovereign markets continue to have limited rating coverage. Expanding credible rating coverage can improve the information available to investors and support the development of deeper domestic and regional capital markets.

AfCRA must set a new benchmark for the continent, maintain its independence, and remain wholly owned and controlled by Africans

Alongside fellow members of the Alliance of African Multilateral Financial Institutions (AAMFI), Afreximbank has consistently maintained that African Multilateral Financial Institutions should be assessed on the basis of their fundamentals, performance, legal frameworks, mandates and operating models. Ensuring that these institutional characteristics are properly understood is essential to achieving informed, balanced and credible assessments of African risk.

Commenting on the uniqueness of the African market, and need for AfCRA’s rating methodology to reflect this, Mr Denys Denya, Senior Executive Vice President, Afreximbank, said: “The rating methodology AfCRA develops must recognise the uniqueness of our environment and its institutional structures. The Agency must set its own standards and not follow those set elsewhere — it must build a unique identity that conforms to an ‘African best practice.”

Highlighting the need for the autonomy of the Africa Credit Rating agency as it takes off, Mr Denya added: “Most importantly, AfCRA must set a new benchmark for the continent, maintain its independence, and remain wholly owned and controlled by Africans. We must all use it, and in return expect a complete assessment of where we (Africa) stand: the strengths the market has ignored, and the weaknesses we still need to fix.”

AfCRA should therefore be seen as complementary to existing international and regional rating agencies, broadening the range of credible analysis available to investors and issuers while strengthening competition, transparency and analytical capacity within Africa’s credit markets.

As Africa seeks to mobilise the scale of capital required for industrialisation, trade, infrastructure and economic transformation, credible African institutions that improve information, strengthen market confidence and deepen the continent’s financial markets will become increasingly important.

Afreximbank congratulates the African Union, the African Peer Review Mechanism (APRM) and all those involved in bringing AfCRA from concept to launch, and looks forward to the contribution the Agency will make to deeper, more transparent and more efficient African capital markets.

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Trending