Connect with us
Anglostratits

Business

Benin: The African Development Bank Supports a Study Aimed at Strengthening the Textile Industry Through the Private Sector

Published

on

Benin

The meeting helped to identify opportunities and make core proposals to strengthen efforts to dynamize the cotton industry

I am especially pleased to see that it is now possible for young designers to get financial and other forms of support for their initiatives in the textile sector

COTONOU, Benin, August 2, 2024/APO Group/ —

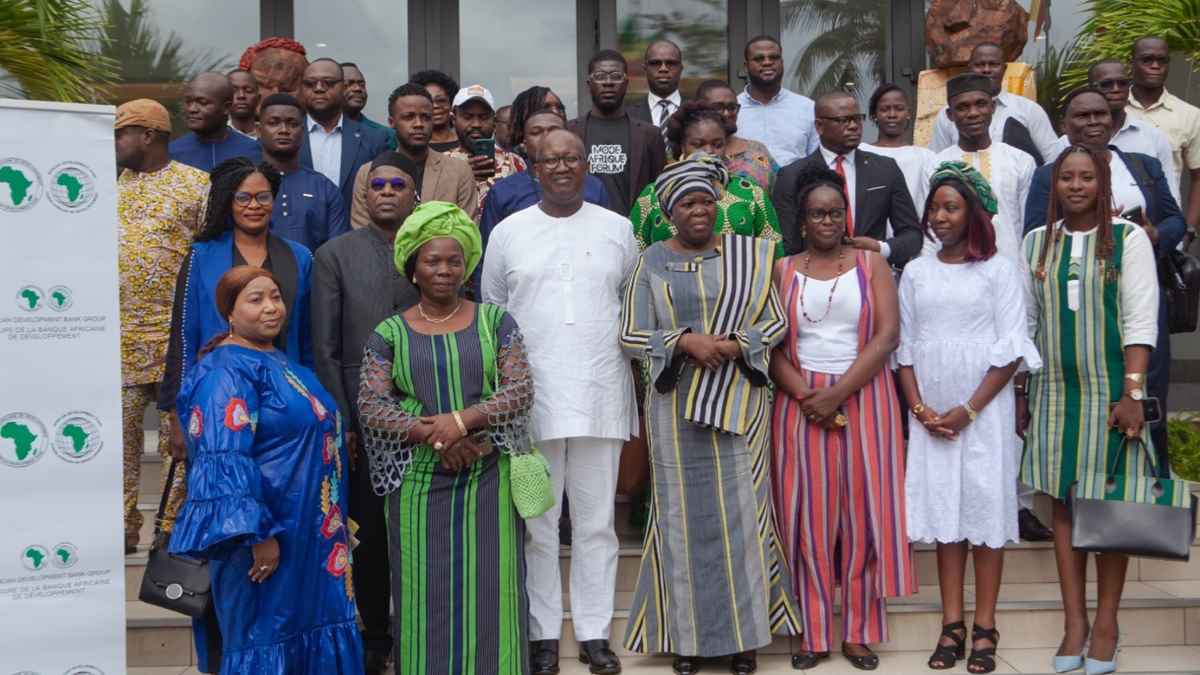
The Country Office of the African Development Bank Group (www.AfDB.org) in Benin – one of Africa’s leading cotton producers – organised a workshop in Cotonou on 31 July 2024 to provide feedback about a study on private sector players bringing fresh momentum to the country’s textile industry.

The meeting marked the end of a process that began on 9 March 2023 with a workshop dedicated to the sector. This has led to collecting important data for a better understanding of the issues in the industry faced by the West African country.

Attendees at the workshop included several experts and national authorities, including the Vice-President of Benin, Ms Mariam Chabi Talata Zimé Yérima, private-sector players operating at all stages of the local cotton value chain, support functions (finance, training, transport, logistics, etc.) and representatives from the country’s technical and financial partners.

The meeting helped to identify opportunities and make core proposals to strengthen efforts to dynamize the cotton industry.

The study revealed multiple opportunities for developing the textile value chain, ranging from production units for accessories to making, logistics, distribution and solutions for taking care of textile items. Other opportunities relate to producing textile items for medical use or for furnishing, cosmetics or the automotive or food industries. The sanitary towels sector alone could generate annual revenue of over USD 13 million (8 billion CFA francs) for the country.

The study emphasised the numerous opportunities for creating tens of thousands of skilled jobs for young people and women.

The report also highlighted the opportunities for the Bank to contribute to the socioeconomic development of the textile industry in Benin and called on senior leaders to take decisions that would support the development of new local industries.

As well as cotton-based textiles, the study pointed to the colossal economic potential and the opportunity to create over 45,000 jobs in a new industry based on pineapple-leaf fibre.

Ms Nathalie Daouda, an expert consultant in the private-sector textile industry at the African Development Bank’s Country Office in Benin, who carried out the study, commented: “The potential additional revenue for the Beninese economy is over USD 5 billion (FCFA 3,000 billion) a year. And it would not take much to make the forecasts a reality, since Benin already has the natural and human resources needed to do the work. The next step is to produce and implement a national plan. The Beninese government has provided ample evidence of its ability to tackle ambitious challenges.”

The Vice-President of the Republic, Ms Mariam Chabi Talata Zimé Yérima, congratulated the Bank on its commitment to supporting an inclusive economy in Benin but above all, for the “realism, completeness and feasibility” of the study. “This report (…) is a sort of strategic plan for strengthening our economy through the textile industry and is relevant to us because developing our economy by building on this sector will help create a large number of jobs,” she emphasized.

“This strategic plan is the first of the steps we need to take to move from ideas to action and from theory to practice,” added Ms Yérima. She highlighted the job-creation opportunities for women and young people but also the economic and social potential of the strategic use of pineapple-leaf fibre for the Beninese textile industry.

Ms Faridatou Yekini, the founder of Mod’Ukpè, which specializes in woven pagne cloth and producing clothes for women, recognized that several actions are underway to boost local small and medium-sized enterprises (SMEs), with a particular focus on women-led businesses. “I am especially pleased to see that it is now possible for young designers to get financial and other forms of support for their initiatives in the textile sector. This development marks a significant step towards the growth and sustainability of our industry,” she said delightedly.

“The African Development Bank has done well to create a favourable environment to encourage collaboration, particularly with visits to the Glo Djigbé industrial area and capacity-building sessions for small and medium-sized businesses. These initiatives helped to formalize and organize my business, Safari Textiles Afrique, and develop positive partnerships. The logical next step would be continuing to fund businesses that are working to bring themselves into line, backed by serious monitoring to ensure good management of the funds,” advocated Caleb Menou, co-founder of the Safari Textiles Afrique brand.

The head of the Bank’s Country Office in Benin, Robert Masumbuko, highlighted the economic and inclusive social development potential of the industry, which is a real windfall for Benin in his view. “The Beninese ecosystem is full of talented women and men who produce really beautiful textile items on a daily basis. But all of them have commented frequently on the need for a clear plan to help them increase not only volumes but also the quality of their training. They need help to acquire or access modern, quality equipment for processing and production and above all, to get access to local and international markets with high-quality, competitive textile solutions,” he commented.

One of the Bank’s missions in relation to the private sector is to intervene financially in a smart, agile manner to provide efficient support for actors in various value chains, concluded Mr Masumbuko. 

Distributed by APO Group on behalf of African Development Bank Group (AfDB).
Business

African Energy Leaders Call for Action on South-South Oil and Gas Partnerships

Published

on

African Energy Chamber

At AEW 2026, industry representatives from Africa and the Caribbean say joint ventures, enforceable local-content rules and regional financing are needed to turn petroleum resources into domestic industrial growth

CAPE TOWN, South Africa, October 17, 2026/APO Group/ –African and Caribbean energy leaders called for stronger cross-border investment, technology transfer and enforceable local-content requirements to ensure emerging oil and gas producers capture more value from their resources during the session South-South Energy Partnership: Advancing Africa’s Oil and Gas Future in 2026 at African Energy Week (AEW) 2026 in Cape Town.


Ndapwilapo Selma Shimutwikeni, CEO, RichAfrica Consultancy, said partnerships could accelerate skills development.

“From a business perspective, we need to build partnerships that encourage joint ventures between experienced countries and emerging countries like Namibia,” she said. “We need to look beyond just oil production and actually look at the entire value chain.”

Building on Shimutwikeni’s remarks, Gilbert Yevi, Lead Consultant, Grenada Hydrocarbon Technical Working Group, called for partnerships that share risks and benefits rather than simply replace one source of financing with another.

We want cooperation and a collaboration in risk sharing, skill sharing, and sharing in the benefits

“We want cooperation and a collaboration in risk sharing, skill sharing, and sharing in the benefits,” he said.

Yevi also advocated regional training centers to pool expertise and help emerging producers access established industry capabilities.

Expanding on the topic of local content, Eric Williams, Principal Consultant and President, Royal Triangle Energy Solutions, said policies must be linked to a broader national development strategy, using petroleum resources to build domestic industries rather than focusing solely on exports.

“The Trinidad model is about using the molecules to develop the country,” he said, arguing that this vision should shape negotiations with upstream investors and the terms of petroleum contracts.

Omar Farouk Ibrahim, Regional Chair for Africa, World Energy Council, said national sovereignty concerns continued to limit practical regional cooperation, despite public commitments to collaboration.

“The first question they ask is: ‘Will the industry be in my territory?’ If it’s not, why should I? And for as long as we have this mentality, believe me, this cooperation and collaboration we’re talking about will just be theory,” he said.

Across the discussion, speakers emphasized that cooperation must translate into financing, enforceable commitments and local capabilities that endure beyond individual projects.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Business

Nigeria NOW! opens its project boardrooms to global investors in Abuja

Published

on

Nigeria

With Nigeria’s annual mining revenue up more than tenfold to above N70bn, Nigeria NOW! brings global investors to Abuja on 19 and 20 November, where the Minister of Solid Minerals Development is Chief Host

First and foremost all international investors coming to Abuja should understand that Nigeria is ready and open for business

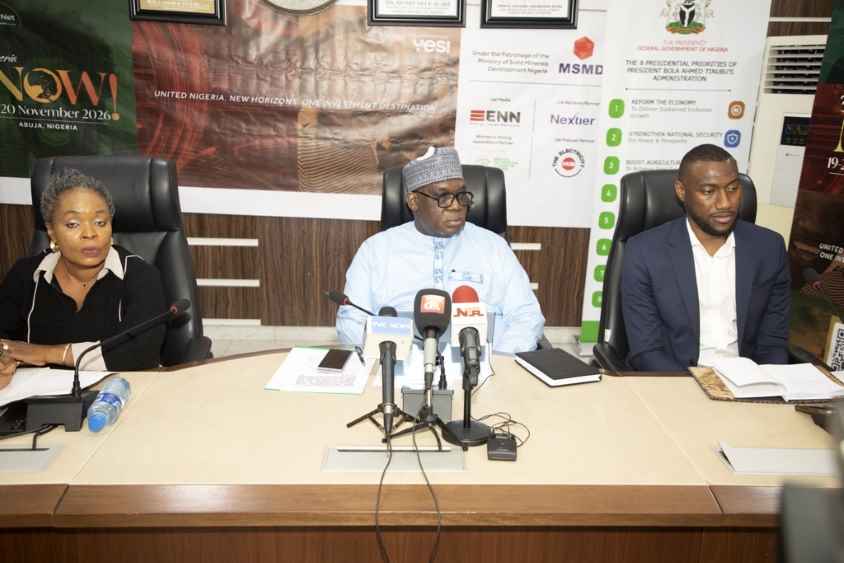
LONDON, United Kingdom, October 21, 2026/APO Group/ –Platinum group metals, gold, nickel, copper, lithium and rare earth elements lie together in one mineral province in Kaduna State, which the Minister of Solid Minerals Development announced in June as world-class and the Nigerian Geological Survey Agency has verified. The Ministry opens its doors to global investors at Nigeria NOW!, held at the Bola Ahmed Tinubu International Conference Centre in Abuja on 19 and 20 November.


Processing is following the discoveries, as lithium facilities of $600m in Nasarawa State and $200m near Abuja sit alongside a $400m rare earth processing project in Nasarawa, and mining lease applicants must now submit value-addition plans. Annual mining revenue has risen from about N6bn before the current administration to more than N70bn by the end of 2025.

The routes to export markets are moving too, as the Federal Executive Council has approved deep seaports at Bakassi and Ondo as public-private partnerships, with the Bakassi port alone valued at $2.27bn.

With a month to go, investors and developers travelling to Abuja will meet these projects at close quarters. In investor boardrooms, the Government of Nigeria will review specific projects in depth, from large-scale infrastructure to multilateral programmes such as Mission 300.

Speaking to Energy News Network in September, Tunde Arisekola, Senior Advisor, Geological and Minerals Information at the African Minerals Development Centre, who joins the minerals session on the first day, said that “first and foremost all international investors coming to Abuja should understand that Nigeria is ready and open for business”. In the same interview he described Nigeria’s economy as “stable, safe, peaceful and welcoming to all international investors”.

The programme opens with a welcome from the Chief Host, H.E. Dr Oladele Henry Alake, Minister of Solid Minerals Development, followed by sessions on how the Ministry of Power will drive capacity into Nigeria’s industrial hubs and on the policies opening the minerals sector to foreign investment, including domestic processing and value addition. The second day turns to the pipeline of transport and port infrastructure and the $1bn Domestic Green Bond, and closes with an investors’ clinic on the 2025 Tax Act.

Lagos State Government, a Nigeria NOW! partner, now regulates its own electricity market after NERC transferred oversight to the Lagos State Electricity Regulatory Commission. Hon. Biodun Ogunleye, Lagos State Commissioner for Energy and Mineral Resources, told Energy News Network that “capital follows bankable cashflows”. The state’s job, he said, is “to create both the infrastructure plan and the commercial architecture that makes that plan financeable”.

On Friday 20 November, YES! Nigeria runs alongside the main programme under the theme “Empowering Today’s Entrepreneurs, Building Tomorrow’s Industrialists”. Abuja University and Philomath University are partners, and the Youth Sustainable Development Network is Community Partner. Its opening session hands the stage to young Nigerians already at work in the sector, among them Damilola Hamid Balogun of YSDN and Emmanuel Terwase of Boost Power.

Nigeria NOW! is held under the patronage of the Minister of Solid Minerals Development, with the Lagos State Government, the Nigerian Indigenous Women in Mining & Natural Resources Organisation, Women in Mining, Nextier and The Electricity Hub as partners.

Distributed by APO Group on behalf of EnergyNet Ltd..


Continue Reading

Business

Global Islamic finance industry assets to reach US$10.5 trillion by 2030 as adoption broadens

Published

on

Global Islamic finance

The report draws on the Islamic Finance Development Indicator (IFDI), a global benchmark that assesses the development of the Islamic finance industry across 140 countries through five key areas, Financial Performance, Governance, Sustainability, Awareness, and Knowledge

For ICD, these developments reinforce the importance of ensuring that Islamic finance serves as a practical instrument for inclusive and sustainable economic transformation

KUALA LUMPUR, Malaysia, October 21, 2026/APO Group/ –LSEG, in collaboration with the Islamic Corporation for the Development of the Private Sector (ICD) (www.ICD-ps.org), the private sector arm of the Islamic Development Bank (IsDB) Group, today announced the results of the 2026 edition of the Islamic Finance Development Report at the Kuala Lumpur Islamic Finance Forum (KLIFF) in Malaysia.


Key findings of the report include:

  • The global Islamic finance industry maintained a strong growth trajectory in 2025, with total assets reaching US$6.5 trillion, up 9% year-on-year. Growth was supported by the continued expansion in Islamic banking, record sukuk issuance, strong Islamic fund performance, and new regulatory frameworks.
  • Malaysia, Saudi Arabia, the United Arab Emirates, Indonesia, and Pakistan retained their positions as the world’s most developed Islamic finance markets. These countries continued to benefit from comprehensive regulation, strong institutional development, active financial markets, and well-established knowledge ecosystems.
  • Several markets recorded notable gains in performance, including Türkiye, Tanzania, Kenya, Benin, Azerbaijan, and Uzbekistan, highlighting the growing momentum across both established and emerging Islamic finance markets.

The report also identified several structural trends that are shaping the industry’s development. Regulatory reforms and stronger market infrastructure are supporting growth beyond core markets, particularly across Africa and Central Asia. Sustainability guidelines are increasingly prioritised, although activity remains concentrated in developed markets. Digitalisation is also advancing, with FinTech, open banking, and tokenised sukuk influencing financing, issuance, and settlement while widening access to financial products. However, talent development is lagging industry expansion, emphasising the need for stronger specialist education.

Khalid Khalafalla, Acting Chief Executive Officer of ICD, said: “For ICD, these developments reinforce the importance of ensuring that Islamic finance serves as a practical instrument for inclusive and sustainable economic transformation. ICD remains committed to advancing private-sector development across its member countries through targeted financing and the promotion of Islamic financial solutions.”

Mustafa Adil, Head of Islamic Finance, LSEG, added: “Looking ahead, global Islamic finance assets are projected to exceed US$10.5 trillion by 2030, supported by continued Islamic banking expansion, growing sukuk issuance momentum, emerging-market adoption and demand for sustainable and digital financial solutions.”

The report draws on the Islamic Finance Development Indicator (IFDI), a global benchmark that assesses the development of the Islamic finance industry across 140 countries through five key areas, Financial Performance, Governance, Sustainability, Awareness, and Knowledge. It provides a holistic view of the global Islamic finance landscape, measuring progress in alignment with Islamic principles and supporting stakeholders in identifying opportunities for growth and reform.

Read full report: Link (https://apo-opa.co/3TTw9yq)

Distributed by APO Group on behalf of Islamic Corporation for the Development of the Private Sector (ICD).


Continue Reading

Trending