Connect with us
Anglostratits

Business

Afreximbank and Kenyan government ink milestone agreements to promote industralisation

Published

on

Afreximbank

Afreximbank will finance the development and operationalisation of industrial parks (IPs) and special economic zones (SEZs) to bolster the country’s industrialisation and export manufacturing

MOMBASA, Kenya, February 28, 2025/APO Group/ —

  • Afreximbank to finance development and operationalisation of industrial parks and special economic zones to bolster industralisation and export manufacturing
  • Afreximbank also commits to three-year US$3 billion Kenya country programme to support trade and trade-related investments

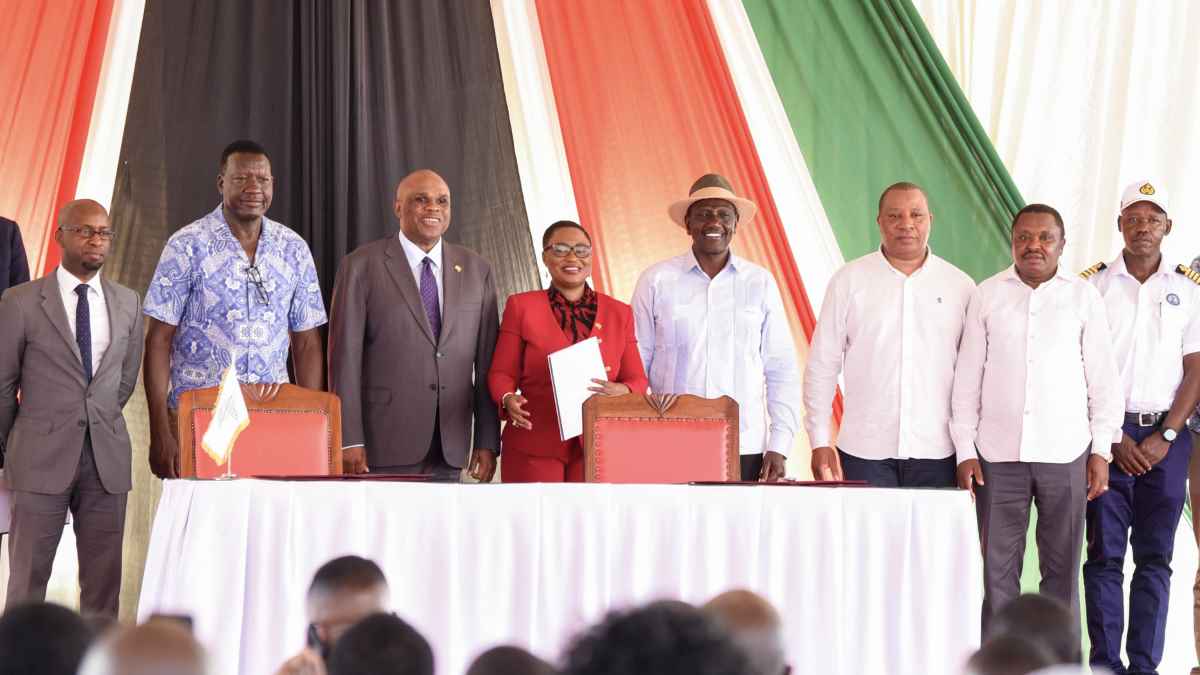
African Export-Import Bank (Afreximbank) (www.Afreximbank.com), Africa’s foremost trade development Bank, today in Mombasa, Kenya, ratified a series of initiatives designed to support Kenya’s industrialisation and export-led development agenda. Under the terms of the initiatives, formalised at a signing ceremony with the Kenyan authorities, Afreximbank will finance the development and operationalisation of industrial parks (IPs) and special economic zones (SEZs) to bolster the country’s industrialisation and export manufacturing.

The proposed industrial parks, to be developed by Afreximbank through its affiliate company, Arise Integrated Industrial Platforms (Arise IIP), will create and sustain an environment in which export-oriented industries can thrive, by leveraging economies of scale, shared infrastructure and access to global markets.

Two projects to be undertaken by Afreximbank, with the support of the Government of Kenya and other strategic collaborators, are the development of the Dongo Kundu Integrated Industrial Park and the Naivasha Special Economic Zone II (Naivasha II), for which, having secured leases of the relevant land, Afreximbank intends to leverage the expertise and experience of Arise IIP, a special economic zone developer with experience in the development of integrated industrial parks in Africa.

Both the Dongo Kundu Integrated Industrial Park and the Naivasha Special Economic Zone II are included in the Fourth Medium Term Plan (2023-2027) of the Kenyan government’s Vision 2030, entitled “Bottom-Up Economic Transformation Agenda for Inclusive Growth”, reflecting the high priority which state institutions are giving to measures that strengthen, expand and accelerate Kenya’s capacity to export value-added goods within Africa and globally.

Speaking on the signing, the President of the Republic of Kenya, H.E. Dr. William S. Ruto said; “We have a responsibility to steer the country in the right direction, harnessing the immense potential of manufacturing, industrialization, agro-processing, and value addition within Special Economic Zones. The signing of these agreements today marks a significant milestone in Kenya’s development, expanding opportunities to enhance our manufacturing sector and create a more conducive environment for investment. We convene here today to sign an investment – and not a loan – undertaken by people whose faith in this country and its possibilities motivates their decision. This is our country, let’s continue to do whatever it takes to make it an attractive destination for those who want to invest.”

In his own comments, Prof. Benedict Oramah, President and Chairman of the Board of Directors of Afreximbank, said:

“Africa has been heralded as a land of opportunity, blessed with resources that power the world. Yet, we have struggled to translate this wealth into lasting prosperity for our people. For decades, we have watched as others reap the rewards of our natural resources, leaving us tethered to a cycle of dependency—exchanging our riches for aid and loans that kept us on the fringes of the global breadbasket.

We convene here today to sign an investment – and not a loan – undertaken by people whose faith in this country and its possibilities motivates their decision

“Those days are behind us. Today, Kenya takes a bold step to reshape this story in a profound and impactful manner. These Parks are an integral part of the Government’s plan to boost the country’s economic growth under the Vision 2030 development blueprint.

Today’s signatures are more than ink on paper—they are a promise to the people of Kenya, a pledge that the country will rise as a beacon of industrial might and self-reliance.”

Mrs. Oluranti Doherty, Managing Director of Export Development at Afreximbank, and Captain William K. Ruto, Managing Director of the Kenya Ports Authority, signed the Dongo Kundu Special Economic Zone agreement. Dr. Kenneth Chelule, Chief Executive Officer of the Special Economic Zones Authority, and Mrs. Doherty signed the Naivasha Special Economic Zone agreement, with H.E. Dr. William Ruto, President of the Republic of Kenya, and Prof. Benedict Oramah, President and Chairman of the Board of Directors of Afreximbank, witnessing the signing of both agreements for the State and for the Bank, respectively.

The Dongo Kundu Industrial Park within the Mombasa SEZ is expected, upon completion, to boost the area with a state-of-the-art industrial park that will contribute significantly to economic growth and industrialisation efforts in Mombasa County and in Kenya as a whole.

The Naivasha II Special Economic Zone – Naivasha II project is located at Mai Mahiu and will include a free trade zone, an industrial park, a logistics zone and a public utility area with a supporting road network. The project will occupy an area of approximately 5000 acres.

The Naivasha II project will also derive value from its strategic geographic position as it sits on the gateway to East and Central Africa through the Northern Corridor Transport System, which comprises both a standard gauge railway and a major highway. Moreover, the SEZ will be close to the Naivasha Inland Container Depot, which serves the East African hinterland countries of Burundi, the Democratic Republic of Congo, Kenya, Rwanda, South Sudan and Uganda.

Other dignitaries in attendance included Mrs Oluranti Doherty, Managing Director, Export Development, Afreximbank; Hon. Davis Chirchir E.G.H, Roads and Transport Cabinet Secretary; Hon. Hassan Ali Joho, Cabinet Secretary for Mining, Blue Economy and Maritime Affairs; Hon. Salim Mvurya, Cabinet Secretary for Youth Affairs, Creative Economy and Sports of Kenya and Honourable Lee Kinyanjui, Cabinet Secretary, Ministry of Investment, Trade and Industry. Additionally, Captain William K. Ruto, Managing Director, Kenya Ports Authority; Dr. Kenneth Chelule, Chief Executive Officer, Special Economic Zones Authority; His Excellency Abdulswamad Shariff Nassir, Governor of Mombasa County; the Honourable Benjamin Tayari, Chairman, Kenya Ports Authority, and Mr. Fredrick Muteti, EBS, Chairperson, Special Economic Zones Authority attended the event.
Distributed by APO Group on behalf of Afreximbank.

Business

Afreximbank Announces Speakers for Africa’s Largest Compliance Forum

Published

on

Afreximbank

Bankers, compliance specialists and fintech leaders from more than 40 countries will explore how regulatory cooperation and technology can align compliance approaches, reduce barriers and advance intra-African and global trade

CAIRO, Egypt, November 3, 2026/APO Group/ –Afreximbank (www.Afreximbank.com) has announced speakers for its 2026 Compliance Forum, Africa’s largest compliance-focused gathering. Discussions will address regulatory fragmentation and barriers across Africa, improve access to correspondent banking services, and explore how technology can strengthen compliance and facilitate cross-border trade


Organised in partnership with the Botswana Investment and Trade Centre (BITC), the Forum will take place from 16 to 18 November 2026 at the Gaborone International Convention Centre in Botswana. Discussions will focus on strengthening regulatory cooperation, improving access to financial services and using technology to support effective compliance across African markets.

Confirmed speakers include Governor Lesego Caster Moseki, Bank of Botswana, Dr. Patrick Ndzana Olomo, Ag. Director, Economic Development, Integration and Trade, and Head of Economic Policy and Sustainable Development, African Union Commission (AUC), Luis Koberg, Founder and CEO of Klearium Group; Shane Ridel, CEO of Elucidate, Sophie Barre, Global Head of Risk and Compliance at Wave Mobile Money Group; Mr Mooketsi Ramanteba, Non-Bank Financial Institutions Regulatory Authority (NBFIRA), Nellie Nuyoni, Head of Private Sector, CBZ Holdings, Moira Mapundu, Head of Compliance, NMB Bank Limited and Boitumelo William of Continental Reinsurance. Compliance specialists from Dow Jones and Standard Chartered will also participate.

Mr Keletsositse Olebile, Chief Executive Officer of the Botswana Investment and Trade Centre, said: “Strong and predictable compliance systems build investor confidence, protect institutions, and create the conditions in which trade and enterprise can flourish.”

Under the theme “Better Compliance – Better Trade: Leveraging Compliance to Promote African Regulations that Advance Intra-African Economic and Trade Integration,” the Forum will examine how African markets can make their regulatory systems work more effectively together while preserving national sovereignty.

Idrissa Diop, Compliance Director at Afreximbank, said: “Our banks across Africa operate across very different legal systems, supervisory approaches and levels of digital maturity. Africa does not need uniformity at any cost. It needs interoperability that reduces friction while preserving regulatory sovereignty.

Our banks across Africa operate across very different legal systems, supervisory approaches and levels of digital maturity

“We invite regulators, compliance specialists, banks, fintechs, trade institutions and technology providers from across the continent to come to Gaborone ready to turn shared principles into practical cooperation, because better compliance can and should deliver better trade for Africa.”

The opening session, “Is Better Compliance Leading to Better Trade?”, will assess how regulatory cooperation can facilitate cross-border business. Other sessions will cover anti-money laundering and countering the financing of terrorism, sanctions, cybersecurity, consumer protection and the use of artificial intelligence in compliance.

Access to correspondent banking services will be a key focus. Luis Koberg, Founder and CEO of Klearium Group, said: “Many African banks continue to face barriers to accessing correspondent banking services. The reasons given often overlook a fundamental challenge: limited visibility across the payment chain. Improved transparency gives our industry the ability to accurately assess and manage risk, on a case-by-case basis with confidence.”

Delegates will also examine how fintech and risk-based onboarding can extend access to affordable financial services while meeting compliance requirements.

Sophie Barre, Global Head of Risk and Compliance at Wave Mobile Money Group, said: “Fintechs are rewriting the rules of financial inclusion and efficiency. By combining world-class technology with intelligent, risk-based onboarding, they can deliver affordable, simple and reliable services within a compliant ecosystem.”

The Compliance Forum will also feature an exhibition of AI-enabled anti-money laundering and counter-terrorist financing compliance systems. These demonstrations will let delegates engage with emerging technologies that can strengthen risk detection, monitoring, and reporting.

This Forum comes as artificial intelligence, automation, cybersecurity, third-party risk and diverging regulatory requirements place new demands on financial institutions. These developments reinforce the need for compliance approaches that reflect Africa’s regulatory, economic and institutional realities while drawing on global good practices.

ACF2026 will provide a platform for stakeholders to redefine compliance strategies for a changing financial environment and develop practical approaches that protect institutions while enabling more efficient movement of capital, goods and services across African borders.

For programme details and registration, visit ACF2026 (https://apo-opa.co/4iVtopG)

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Business

Gas Exporting Countries Forum (GECF) Leadership Roundtable Brings Gas Producer Coordination to Paris

Published

on

Etu Energias

As African gas producers navigate rising domestic demand, global LNG competition and a renewed push for investment, the GECF Leadership Roundtable at the Invest in African Energy 2027 Forum will examine how greater coordination can support project development, market access and long-term gas monetization

PARIS, France, November 3, 2026/APO Group/ –Africa’s gas industry is entering a period in which cooperation between producing countries could become increasingly important. Demand is rising, LNG markets are being reshaped by geopolitical disruptions and new supply, while major gas developments across the continent continue to compete for capital.


Against this backdrop, the GECF Leadership Roundtable at the Invest in African Energy (IAE) Forum 2027 in Paris will bring the perspectives of gas-producing countries into a discussion focused on the commercial and strategic priorities shaping the sector.

The session comes as Africa continues to expand its role in global LNG markets. The GECF forecasts LNG exports from the continent to reach about 110 billion cubic meters (bcm), or 80 million tons per annum (mtpa), by 2030, rising to 215 bcm, or 160 mtpa, by 2050. The outlook spans producers including Algeria, Angola, Egypt, Equatorial Guinea, Mozambique, Mauritania, Senegal and Nigeria, while GECF projections point to growing LNG trade with Asia and within African markets.

Recent developments have reinforced the strategic value of that supply base. Tanzania’s long-delayed $42 billion LNG project has gained renewed attention as disruptions to Middle Eastern gas supplies have increased the value of diversified LNG sources, while ExxonMobil is advancing preparations for Mozambique’s Rovuma LNG project after years of delay.

For African producers, however, expanding exports is only one part of the equation. Domestic gas demand is rising at the same time that governments are seeking to use gas to improve electricity supply, support industrial development and create new revenue streams. That creates a need to balance export projects with domestic offtake, pipeline infrastructure, gas processing and gas-to-power development.

Coordination between producing countries can help address some of these challenges. Sharing experience on fiscal frameworks, project development, infrastructure and market access can help governments compete for investment while strengthening the case for regional gas infrastructure and cross-border trade.

The global market is also becoming more competitive. Reuters reported this month that gas and LNG infrastructure investment is expanding across multiple regions, with Asia accounting for the largest share of planned LNG import capacity. At the same time, disruptions to Middle Eastern supply have reinforced concerns around security of supply and increased the strategic importance of alternative producers. That creates an opening for African gas producers, but converting that opportunity into projects will require capital, infrastructure and credible long-term markets.

The GECF Leadership Roundtable at IAE 2027, taking place in Paris from May 11-13, will provide a senior-level setting to examine those issues alongside the investors and project developers needed to advance them. The wider forum is designed to connect African energy markets with global capital, with a focus on projects spanning gas, LNG, infrastructure and power.

For African gas producers, the question is how effectively its resources can be developed, connected to markets and converted into reliable energy and industrial growth. The Paris roundtable will put producer coordination at the center of that investment conversation.

Distributed by APO Group on behalf of Energy Capital & Power.


Continue Reading

Business

Islamic Corporation for the Development of the Private Sector (ICD) and Open Bank Sign Expression of Intent for a Potential USD 10 Million Line of Financing in Uzbekistan

Published

on

Islamic Corporation

The EoI sets out the intent to establish a Shariah-compliant LoF facility of up to USD 10 million from ICD to Open Bank to be deployed for the onward financing of eligible private sector projects, including small and medium-sized enterprises (SMEs) and corporates operating in the Republic of Uzbekistan

JEDDAH, Saudi Arabia, November 1, 2026/APO Group/ –

  • ICD and JSC Open Bank (Uzbekistan) have signed an Expression of Intent for a potential Shariah-compliant Line of Financing facility of up to USD 10 million
  • The facility aims to channel funds to eligible private sector projects, including SMEs and corporates across Uzbekistan
  • The potential Line of Financing facility intends to support job creation and SME growth, contributing to broader economic development in Uzbekistan
  • Open Bank, a privately owned digital bank licensed by the Central Bank of Uzbekistan, will serve as the intermediary institution to channel the funds to private enterprises


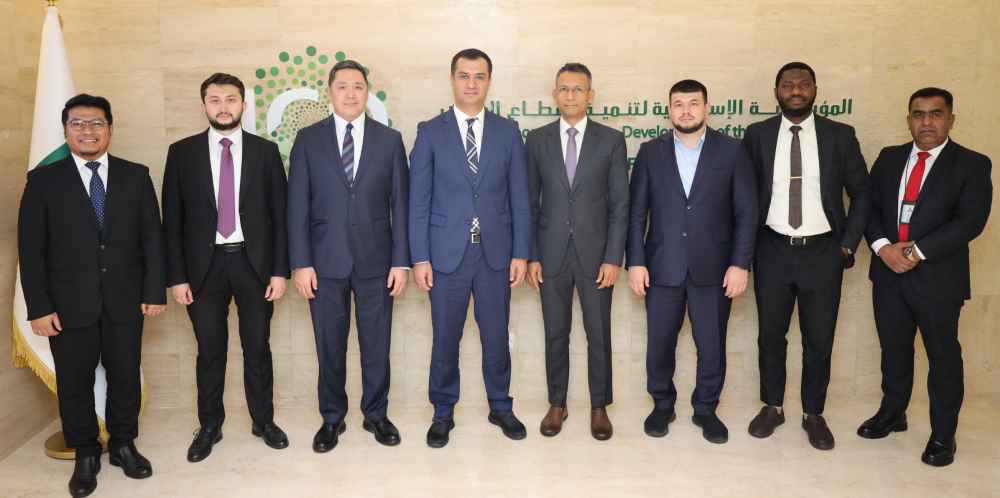
The Islamic Corporation for the Development of the Private Sector (ICD) (www.ICD-PS.org), the private sector arm of the Islamic Development Bank (IsDB) Group, and Joint Stock Company “Open Bank” (Open Bank) from Uzbekistan have signed an Expression of Intent (EoI) in Jeddah, Saudi Arabia, on 26 October 2026, for a potential Shariah-compliant Line of Financing (LoF) facility of up to USD 10 million, aimed at supporting eligible private sector projects in the Republic of Uzbekistan.

The EoI sets out the intent to establish a Shariah-compliant LoF facility of up to USD 10 million from ICD to Open Bank to be deployed for the onward financing of eligible private sector projects, including small and medium-sized enterprises (SMEs) and corporates operating in the Republic of Uzbekistan. The facility is designed to ensure that financing reaches productive segments of the economy in a manner consistent with Shariah principles and in line with the development objectives of ICD and Uzbekistan.

The intended facility reflects ICD’s commitment to expanding access to Shariah-compliant financial services in Central Asia. By working through Open Bank, a digitally oriented institution with a focus on retail and SME customers, the proposed LoF aims to direct resources toward businesses that can generate meaningful employment opportunities and contribute to sustainable economic growth in Uzbekistan. SME support of this nature plays an important role in strengthening the private sector and broadening economic participation across the country.

ICD’s development mandate centers on advancing private sector growth and improving livelihoods in its member countries through Shariah-compliant financing solutions. The intended LoF with Open Bank aims to contribute to job creation and SME support in Uzbekistan, outcomes that align with ICD’s broader objective of fostering inclusive and sustainable economic development across the IsDB Group’s member countries.

Distributed by APO Group on behalf of Islamic Corporation for the Development of the Private Sector (ICD).


Continue Reading

Trending