Connect with us
Anglostratits

Business

Achieving a Frictionless Customer Experience in Fintech (By Lelen Udayan)

Published

on

fintech

Modern customers expect fintechs to focus as much on the experience they provide as the products and services being offered

CAPE TOWN, South Africa, February 14, 2023/APO Group/ — 

By Lelen Udayan, head of customer experience at Mukuru (www.Mukuru.com)

By definition, a truly frictionless customer experience (CX) is unobtainable even though it is the end state every fintech company strives for. Along the way, the focus falls on providing enhanced experiences that stem from the points of friction identified across the customer journey. In doing so, businesses can improve on the products, processes, and services they deliver.

According to Gartner (https://apo-opa.info/3lyxYiG), this requires fintechs to remove the elements that create unnecessary friction or make it unnecessarily difficult for customers to access products and services. To this end, Gartner repositions (https://apo-opa.info/3E4pZ3f) frictionless as rather about creating an effortless experience. This is important as it shifts the spotlight from what it calls ‘feel good’ moments that have low impact on loyalty or repeat business. Instead, more attention is put on using CX as the means to secure repeat business while reducing operating costs.

Removing friction

Modern customers expect fintechs to focus as much on the experience they provide as the products and services being offered. An enhanced experience is important because it shows customers that the fintech acknowledges its failures and is working on improving those areas while also removing the elements that can lead to dissatisfaction.

For an organisation like Mukuru, increasing customer satisfaction, retention, and referrals are largely due to making sure pain points are seen, heard, and addressed. This is done by tracking the customer journey, measuring satisfaction, and customer effort. Additionally, Mukuru (https://apo-opa.info/3lB0396) ensures that customer sentiment and the voice of the customer are prioritised across the business.

Fundamentally, the only way a fintech can remove friction is to ensure its service teams are equipped to assist customers when they do have a problem, query, or complaint.

Channels of engagement

Fundamentally, the only way a fintech can remove friction is to ensure its service teams are equipped to assist customers when they do have a problem, query, or complaint

For this to happen, the company must embrace all of the channels within its capabilities to invest in an omnichannel CX. A PWC report (https://apo-opa.info/3RVAiw4) found that the number of companies doing this has increased by more than 60% in recent years.

Closer to home, the State of CX in South Africa 2022 report (https://apo-opa.info/3YvNAlF) writes that 45% of financial sector respondents identified seamless omnichannel experience on their channel of choice as the main factor influencing customer satisfaction. As many as 64% of local fintech’s have fully implemented virtual assistants and chatbots or are in the process of doing so as critical enablers of this omnichannel experience. Similarly, 27% of companies in financial services have installed bots on messaging apps like WhatsApp and Facebook Messenger, compared to only 7% average in other sectors.

At Mukuru, our purpose is to enable greater degrees of financial inclusion for customers on the African continent – still predominantly cash-based – and globally, which is why we take a tailored approach to customer channels. Channels such as USSD and WhatsApp perform well across Africa, whereas our App is a more relevant channel for UK customers. We have seen the impact of this strategy with WhatsApp, our biggest transacting customer channel in South Africa, where the proportion of transacting customers have almost doubled in the last 3 years.

The golden thread running through a successful omnichannel strategy is how best to meet customer expectations. This requires providing the right fintech employees with the tools, systems and processes to effectively support customers. With these in place, the most common points of friction can be addressed. These include things like resolution time and understanding who the customer really is. In the case of the former, the challenges encompass response times and why the first point of contact might not have the answer. When it comes to the latter, it is about knowing who the individual customer is without having them provide different pieces of information at every engagement point.

FinTech’s must therefore be more consistent and remove the frustration of customers repeating the query to every person in the engagement chain or, even worse, having to phone back at a later stage. Furthermore, the value of self-services cannot be ignored as digital-savvy customers might prefer to resolve the common queries they have themselves.

Through all of this, the fintech must have access to fit-for-purpose tools, competent staff, and efficient processes across product lines and platforms.

Continuous journey

One of the biggest mistakes any fintech can make is to assume that creating a frictionless experience is a once-off exercise. As mentioned, becoming frictionless is an end goal that will never be fully realised. Driving this is setting the business up to learn from its past CX mistakes.

To do so requires the process of CX improvements to be formalised and rolled out to all applicable areas of the business. Service staff must be empowered to resolve customer pain points. Additionally, there is a growing need to establish effective self-service solutions where customers become less reliant on human touch points. Perhaps most crucially, customer success can only be realised by continually monitoring the journey, touchpoints, and the voice of the customer.

All of this can be distilled into initiating a CX project, implementing it, and then iterating as needed. Mukuru (https://apo-opa.info/3lB0396) has made CX a part of its ethos. This enables the business to continually drive improvements in this space. FinTech’s should strive to make every customer interaction with the business a positive one.

Distributed by APO Group on behalf of Mukuru.
Business

SLB commissions new fluids systems plant in Pemba to support Mozambique’s offshore energy development

Published

on

Mozambique

New facility expands in-country drilling and completion fluids capability, advancing the next phase of SLB’s growth in Mozambique

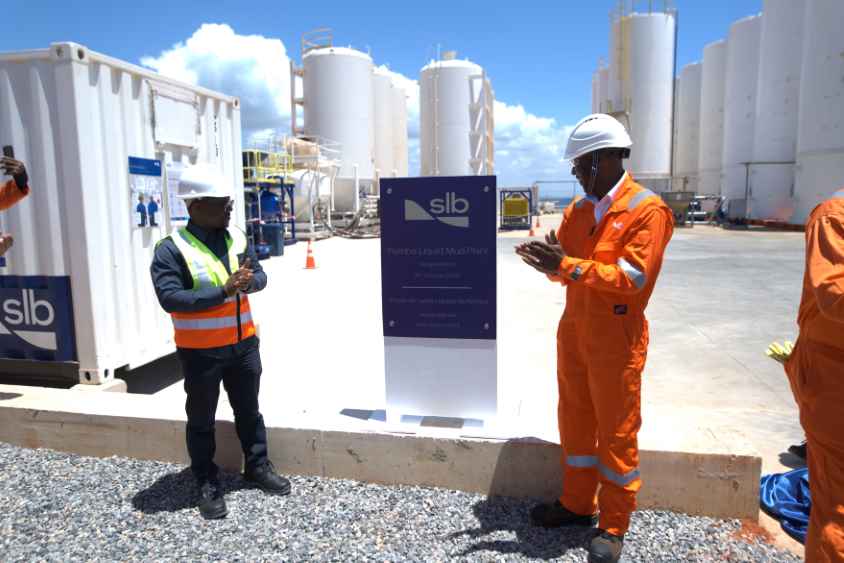
PEMBA, Mozambique, October 9, 2026/APO Group/ –SLB (NYSE: SLB) (www.SLB.com) announced the opening of a new fluids systems plant in Pemba, Mozambique. The new facility strengthens in-country capacity to prepare, store and deliver drilling and completion fluids for offshore operations, reinforcing the infrastructure needed as Mozambique’s offshore activity grows and its role as a strategic energy hub for East Africa continues to expand.

The commissioning of the plant, also known as a liquid mud plant, coincides with SLB marking 70 years of operations in Mozambique. It reflects the company’s long-term commitment to investing in people, infrastructure and capability that support the country’s long-term offshore energy development plans.


With an initial storage capacity of 21,000 barrels, the liquid mud plant provides a scalable platform for future growth, supporting multiple customers and rising offshore activity while improving logistics and enhancing operational flexibility.

As SLB marks 70 years in Mozambique, this investment reflects our confidence in the country’s future and our commitment to supporting its energy ambitions

“As SLB marks 70 years in Mozambique, this investment reflects our confidence in the country’s future and our commitment to supporting its energy ambitions,” said Miguel Baptista, Central, East and Southern Africa, Managing Director, SLB. The new liquid mud plant strengthens local energy infrastructure, expands opportunities for local content development, and enhances our ability to support customers as they deliver some of Africa’s most significant offshore energy resources.”

The liquid mud plant project was delivered with strong local participation and that momentum is expected to continue into operations. During project delivery, more than 100 jobs were created in Pemba with nationals representing 80% of the workforce, reflecting a focus on building local capability.

The project was delivered with a strong focus on safety, operational integrity, and quality, achieving more than 67,000 hours worked without a recordable safety incident.

This key infrastructure strengthens SLB’s ability to support consistent service quality and enhance supply chain readiness for increasing offshore activity across Mozambique, supporting customers execute safely and efficiently while developing local skills and expertise.

Key Points:

  • SLB has commissioned a new fluids system plant in Pemba, expanding in-country drilling and completion fluids capability for offshore operations.
  • With an initial storage capacity of 21,000 barrels, the facility provides a scalable platform to support growing offshore activity in Mozambique.
  • The investment marks the next phase of SLB’s growth in Mozambique, strengthening local capability and supporting long-term offshore energy development.

Distributed by APO Group on behalf of SLB.


Continue Reading

Business

South African Energy Storage Association (SAESA) welcomes 4,600 MW battery storage prioritisation and calls for integrated energy planning

Published

on

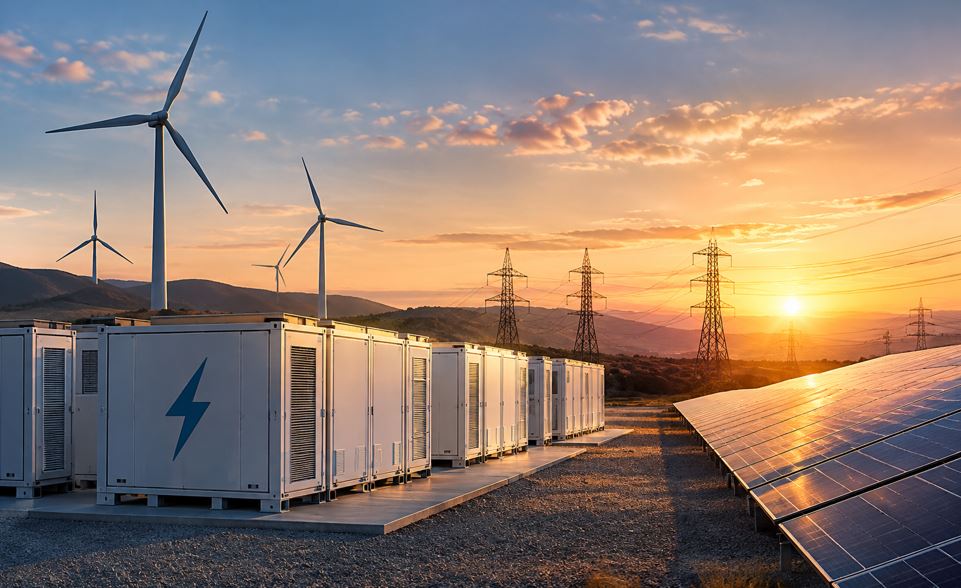
Battery energy storage systems (BESS) are becoming critical system infrastructure, supporting flexibility, reducing avoidable curtailment, shifting energy into periods of demand and strengthening security of supply

JOHANNESBURG, South Africa, October 9, 2026/APO Group/ –The South African Energy Storage Association (SAESA) (www.SAESA.org.za) welcomes the prioritisation of 4,600 MW of battery energy storage under the first Integrated Resource Plan (IRP) 2025 Section 34 determination.


The timing is significant. Recent Integrated Energy Plan (IEP) modelling and assumptions discussions highlighted a fundamental shift that South Africa’s energy planning now needs to capture: we cannot plan the future power system by counting megawatts of generation alone.

We must plan for when energy is available, where it is available, how it moves through a constrained grid and how it is stored and dispatched when the system needs it most.

The announcement reinforces that shift. Battery energy storage systems (BESS) are becoming critical system infrastructure, supporting flexibility, reducing avoidable curtailment, shifting energy into periods of demand and strengthening security of supply.

For SAESA, the message for the IEP is clear: storage, flexibility and system services must be modelled as integral components of South Africa’s future electricity architecture, with their contribution considered from the outset of generation planning.

“The IEP must plan the power system we are becoming, not simply model the power system we have inherited,” says SAESA.

The IEP must plan the power system we are becoming, not simply model the power system we have inherited

Partnership with C&I Energy + Storage Summit

SAESA is an association partner of the C&I Energy + Storage Summit, created by VUKA Group, taking place on 28–29 October 2026 at The Maslow Hotel, Sandton, Johannesburg.

The summit brings together commercial and industrial energy users, project developers, financiers, regulators and solution providers to explore practical approaches to energy security, procurement and storage deployment.

For businesses assessing how storage can support their operations, the event offers an opportunity to meet SAESA and engage with the wider energy community on the decisions shaping South Africa’s evolving electricity system.

Commercial and industrial energy decision-makers are invited to apply to attend as hosted buyers. Qualifying buyers receive complimentary summit access and curated opportunities to engage with industry partners.


Meet SAESA at C&I Energy + Storage Summit: Join the Hosted Buyer Programme

The Hosted Buyer Programme connects commercial and industrial energy decision-makers with solution providers shaping South Africa’s evolving private energy market.

Qualified energy buyers receive complimentary access to the summit and curated engagement with industry partners exploring energy procurement, storage deployment and project development.

Apply for the Hosted Buyer Programme (https://apo-opa.co/4ehLijJ)

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Business

Afreximbank welcomes launch of Africa Credit Rating Agency as an important step in strengthening Africa’s financial architecture

Published

on

Expanding credible rating coverage can improve the information available to investors and support the development of deeper domestic and regional capital markets

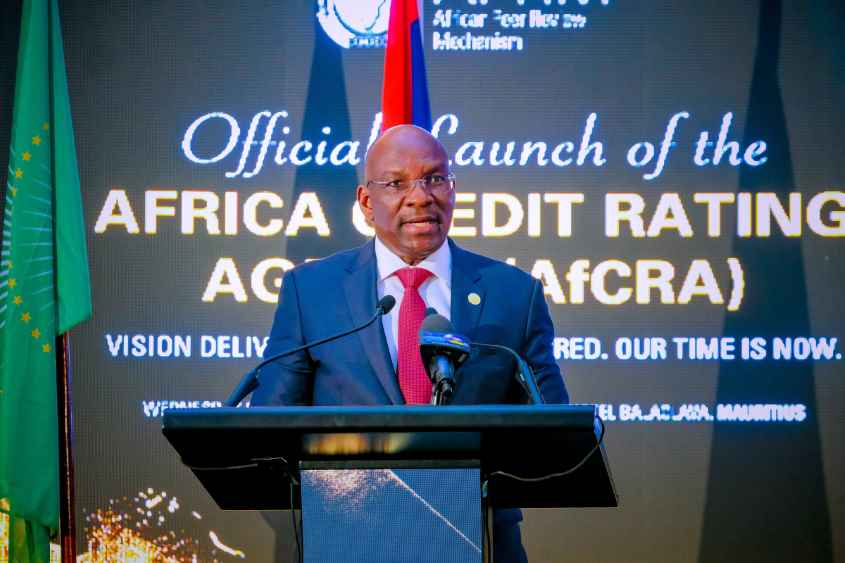
PORT LOUIS, Mauritius, October 8, 2026/APO Group/ –African Export-Import Bank (Afreximbank) (www.Afreximbank.com) welcomes today’s launch of the Africa Credit Rating Agency (AfCRA), an important milestone in strengthening Africa’s financial architecture and expanding the continent’s capacity to generate credible, independent analysis of African credit risk.


Credit ratings play an important role in determining access to capital, influencing investor perceptions and shaping the cost at which governments, institutions and businesses can finance development. It is therefore essential that assessments of African credit risk are independent, rigorous and evidence-based, while reflecting a complete understanding of the structures, institutions and economic realities being assessed.

The establishment of AfCRA adds an important African-led source of credit opinion to the market. Its value will not be measured by whether it produces more favourable ratings, but by the credibility of its analysis, the quality of its data and transparency of its methodology, and its ability to deepen understanding of African sovereigns, sub-sovereigns and corporate credit.

This is particularly important given that many African issuers remain unrated, while local-currency and sub-sovereign markets continue to have limited rating coverage. Expanding credible rating coverage can improve the information available to investors and support the development of deeper domestic and regional capital markets.

AfCRA must set a new benchmark for the continent, maintain its independence, and remain wholly owned and controlled by Africans

Alongside fellow members of the Alliance of African Multilateral Financial Institutions (AAMFI), Afreximbank has consistently maintained that African Multilateral Financial Institutions should be assessed on the basis of their fundamentals, performance, legal frameworks, mandates and operating models. Ensuring that these institutional characteristics are properly understood is essential to achieving informed, balanced and credible assessments of African risk.

Commenting on the uniqueness of the African market, and need for AfCRA’s rating methodology to reflect this, Mr Denys Denya, Senior Executive Vice President, Afreximbank, said: “The rating methodology AfCRA develops must recognise the uniqueness of our environment and its institutional structures. The Agency must set its own standards and not follow those set elsewhere — it must build a unique identity that conforms to an ‘African best practice.”

Highlighting the need for the autonomy of the Africa Credit Rating agency as it takes off, Mr Denya added: “Most importantly, AfCRA must set a new benchmark for the continent, maintain its independence, and remain wholly owned and controlled by Africans. We must all use it, and in return expect a complete assessment of where we (Africa) stand: the strengths the market has ignored, and the weaknesses we still need to fix.”

AfCRA should therefore be seen as complementary to existing international and regional rating agencies, broadening the range of credible analysis available to investors and issuers while strengthening competition, transparency and analytical capacity within Africa’s credit markets.

As Africa seeks to mobilise the scale of capital required for industrialisation, trade, infrastructure and economic transformation, credible African institutions that improve information, strengthen market confidence and deepen the continent’s financial markets will become increasingly important.

Afreximbank congratulates the African Union, the African Peer Review Mechanism (APRM) and all those involved in bringing AfCRA from concept to launch, and looks forward to the contribution the Agency will make to deeper, more transparent and more efficient African capital markets.

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Trending