Connect with us
Anglostratits

Business

A Stronger Africa Requires Stronger Investment Policies (By NJ Ayuk)

Published

on

African Energy Chamber

Stable fiscal regimes, predictable contract terms, and anti-corruption measures help de-risk projects and give investors the confidence to commit long-term capital

JOHANNESBURG, South Africa, December 17, 2025/APO Group/ —By NJ Ayuk, Executive Chairman, African Energy Chamber (https://EnergyChamber.org/).


Investor confidence in Algeria’s energy sector is climbing. The country — already one of Africa’s most active oil and gas producers — has seen even more momentum in 2025.


In October, Algeria’s national oil company, Sonatrach, announced a USD5.4 billion partnership with Saudi Arabia’s Midad Energy to explore and develop new fields in the Illizi Basin. The government has also entered advanced talks with ExxonMobil and Chevron on a groundbreaking framework that would give US companies access to Algeria’s vast natural gas reserves — a first in the nation’s history. Earlier this year, Sonatrach and China’s Sinopec signed a Memorandum of Understanding (MoU) to jointly assess and potentially develop resources in the Gourara and Berkine-Est basins.


These agreements are not emerging in a vacuum. They reflect the deliberate reforms Algeria has enacted in recent years: simplifying business registration, establishing special economic zones, improving contract transparency, and signaling a stronger commitment to international partnership. As a result, the country is drawing a diverse roster of major players, from Eni and Equinor to TotalEnergies.


Algeria’s progress offers a timely lesson for African nations with petroleum resources. Africa’s oil and gas sector will require billions in new investment over the next decade, yet securing capital has become more difficult. As noted in the African Energy Chamber’s (AEC) “State of African Energy: 2026 Outlook Report,” Western financial institutions continue to retreat from fossil-fuel financing, and many investors remain cautious about perceived risks in emerging markets.

The governments that confront these challenges by adopting investor-friendly policies and strengthening governance will be the ones to realize the key benefits of oil and gas, including energy security, job creation, and broader economic growth.


Algeria shows what is possible when reforms align with clear investment objectives. Other countries that have taken similar steps, such as Angola and Nigeria, are also seeing renewed activity. But this cannot remain limited to a handful of markets. The resources are here. The opportunities are here. Now is the time to act.


The Opportunity Is Enormous. The Capital Isn’t.


Africa certainly doesn’t lack opportunity — it has an abundance of it. The continent holds an estimated 125 billion barrels of proven oil reserves and roughly 625 trillion cubic feet of natural gas as of 2025. These are not abstract numbers; they represent jobs, infrastructure, and prosperity waiting to be unlocked.


According to our outlook report, Africa’s overall hydrocarbon production is projected to hold steady at around 11.4 million barrels of oil equivalent per day (MMboe/d). But maintaining — let alone expanding — that output requires continuous investment. Wells decline. Infrastructure ages. New discoveries must be developed. Without consistent capital inflows, Africa risks leaving its wealth in the ground.


And while our outlook points to encouraging signs of renewed spending — particularly in countries like Namibia, Angola, and Mozambique — the continent remains far from reaching its full investment potential. The AEC estimates that the continent faces an annual energy finance gap between USD31.5 billion and USD45 billion. External investment is expected to average roughly USD35 billion per year between 2020 and 2030 — a level that will not deliver the production growth Africa needs to meet rising domestic demand or strengthen export capacity.


Investment Won’t Come Without Reform


Whether Africa can increase production hinges on several factors, but few are more important than governments’ ability to offer investment terms that meet industry needs. Oil and gas projects demand massive upfront capital — often in the hundreds of millions or even billions of dollars — and investors are keenly aware of the risks associated with frontier markets. These risks include political instability, abrupt regulatory changes, contract uncertainty, weak infrastructure, and security concerns. On top of that, private-sector financiers continue to face global pressure to channel capital toward renewable energy rather than fossil fuels.


If African countries want to compete for scarce investment dollars, they must demonstrate that their markets are stable, predictable, and commercially attractive.


One of the greatest deterrents to investors is slow or unpredictable regulatory approval processes. Lengthy permitting timelines, unclear requirements, or frequent policy changes can stall projects and undermine returns. Governments must streamline approvals and establish transparent regulatory frameworks with firm timelines. Fast, direct communication channels between regulators and companies also make an enormous difference in reducing delays.


A proven approach is the creation of one-stop regulatory agencies that consolidate multiple approvals under one roof. Equatorial Guinea has implemented a system that allows investors to establish a business within a week, and Angola recently launched a one-stop center for local content compliance in the oil and gas sector. These reforms dramatically reduce friction and make markets far more competitive.


Equally important is ensuring strong governance and transparency. Stable fiscal regimes, predictable contract terms, and anti-corruption measures help de-risk projects and give investors the confidence to commit long-term capital. Countries such as Nigeria and Ghana have emphasized clear rules, transparent licensing processes, and improved sector governance as central pillars of their investment strategies — and these efforts are widely recognized as strengthening investor trust.


The Green Energy Gap Africa Cannot Afford


Ironically, even as global institutions push investors to prioritize renewable energy, Africa is experiencing a significant green-energy investment shortfall.


If African countries want to compete for scarce investment dollars, they must demonstrate that their markets are stable, predictable, and commercially attractive

Our outlook report addresses this problem: “Africa’s renewable energy sector holds the potential to reshape the power landscape and enhance energy security for millions. However, given Africa is the second most populous continent in the world, the scale of investment in the renewable energy sector remains significantly behind that of other global initiatives.


“Between 2020 and 2025, Africa invested USD34 billion in clean power technologies, with 52% directed towards solar power and 25% towards onshore wind. Despite this investment, Africa’s share of global investments is projected to be just 1.5% in 2025.”


Just like the fossil-fuel financing gap, this shortfall is tied directly to investor risk perceptions. As the report explains, Africa continues to lag other regions because its energy markets are seen as high risk, marked by political instability, regulatory uncertainty, inadequate infrastructure, policy reversals, corruption concerns, and burdensome bureaucracy. Limited access to capital and high interest rates compound these challenges.


African governments must adopt policies that counter these concerns. The same reforms that draw investment into oil and gas — transparent rules, predictable contract terms, streamlined approvals, and stable fiscal regimes — will also increase investor confidence in solar, wind, hydrogen, and other green energy sources.


Strengthening renewable-energy financing is urgent, particularly because one of the power sources with the greatest potential to support Africa’s long-term energy security and economic growth is also among the costliest to develop: nuclear energy.


To grasp the scale of the challenge, consider that Africa plans to spend around USD105 billion to build 15,000 MW of new nuclear power capacity by 2035. Egypt’s 4,800 MW project on the continent is expected to cost nearly USD29 billion alone.


Yet the potential benefits of nuclear power cannot be overstated. As our report says, “Nuclear offers a unique advantage: it delivers stable baseload power, crucial for replacing fossil fuel generation and for stabilising grids that increasingly depend on intermittent renewable sources.” Without that stability, Africa risks unreliable supply as less-predictable solar and wind take on larger shares of the energy generation mix.


And while traditional nuclear infrastructure requires massive upfront capital, new small modular reactor technologies offer “smaller, more flexible project scales and lower capital requirements,” our report notes. For example, a microreactor with 10–20 MW output can cost between USD50 million and USD300 million, while a 300 MW SMR might cost around USD900 million to USD1 billion, much less than conventional nuclear plants.


For African countries seeking long-term, low-carbon energy security, encouraging nuclear investment will be worth the effort. But Africa cannot fully unlock its renewable-energy potential — or its nuclear potential — without creating a policy environment in which investors feel confident financing long-term, capital-intensive projects.


A Call for the World Bank to Step Up


Even with growing private-sector participation, Africa will need far greater financial support to develop its oil and gas resources, scale renewables, and build the foundation for a viable nuclear sector. Private capital alone cannot meet the scale of Africa’s energy needs.


This is why the AEC continues to call on the World Bank to end its 2017 ban on financing upstream oil and gas projects, a policy adopted in response to global concerns about greenhouse gases and climate change. Africa cannot eliminate its widespread energy poverty without responsibly developing its natural gas resources. Gas-to-power projects offer one of the fastest and most affordable pathways to expanding electricity access, providing the reliable baseload supply needed to power households, industries, and growing cities. And at a time when renewable-energy investment remains far below required levels, revenues from oil and gas can help finance the long-term transition to cleaner energy sources.


The AEC welcomes the World Bank’s decision to lift its ban on financing nuclear energy, as well as its ongoing review of restrictions surrounding natural gas exploration and production. But review is no longer enough. The pace of change must match the urgency of Africa’s energy crisis.


Population growth is accelerating faster than our electrification efforts, meaning every incremental gain is being swallowed by demographic realities. Africa needs the capital to expand access to electricity rapidly and at scale — not in 10 or 20 years, but now. By maintaining its prohibition on upstream oil and gas financing, the World Bank is unintentionally contributing to prolonged energy poverty, limiting Africa’s ability to industrialize and undermining progress toward a balanced and sustainable energy future.


Lifting this ban would not undermine global climate goals. On the contrary, it would support Africa’s responsible use of natural gas as a transition fuel, while enabling the continent to invest in renewables, storage, and nuclear power — the technologies that will power Africa for generations to come. What Africa needs from the World Bank is not hesitation, but partnership.


I would add that the AEC is not the only voice calling for change. The United States government has also urged the World Bank to reconsider its restrictions. As US President Donald Trump’s administration recently noted, multilateral development banks cannot fulfil their core mandates if the World Bank continues to restrict natural-gas financing. “An all-of-the-above energy strategy that provides for the financing of upstream gas would be a positive step towards reconnecting the World Bank, and all other multilateral development banks, to their core missions of economic growth and poverty reduction,” a spokesperson for the US Treasury Department told the Financial Times.

A Decisive Moment

Africa’s energy future will not be secured through rhetoric or cautious half-measures. It will be secured by creating the conditions that allow investment to flow — conditions that give global partners the confidence to support our oil and gas resources, expand our renewable-energy capacity, and build the nuclear infrastructure that can anchor our long-term energy security.


If African governments embrace reform rather than stagnation and if institutions like the World Bank commit to partnership instead of prohibition, Africa can end energy poverty, drive industrialization, and give millions the reliable power they need to thrive. Africa’s future depends on what we choose to do today.


“The State of African Energy: 2026 Outlook Report” is available for download. Visit https://apo-opa.co/3Yv2WZ8 to request your copy.
Distributed by APO Group on behalf of African Energy Chamber.

Business

Cassava Technologies and Mauritius Telecom sign Memorandum of Understanding (MoU) on Artificial Intelligence (AI) services and education in Africa

Published

on

Africa

The partnership combines this computing scale, Cassava’s AI platforms and regional reach with MT’s own AI products, local language capabilities and operating experience

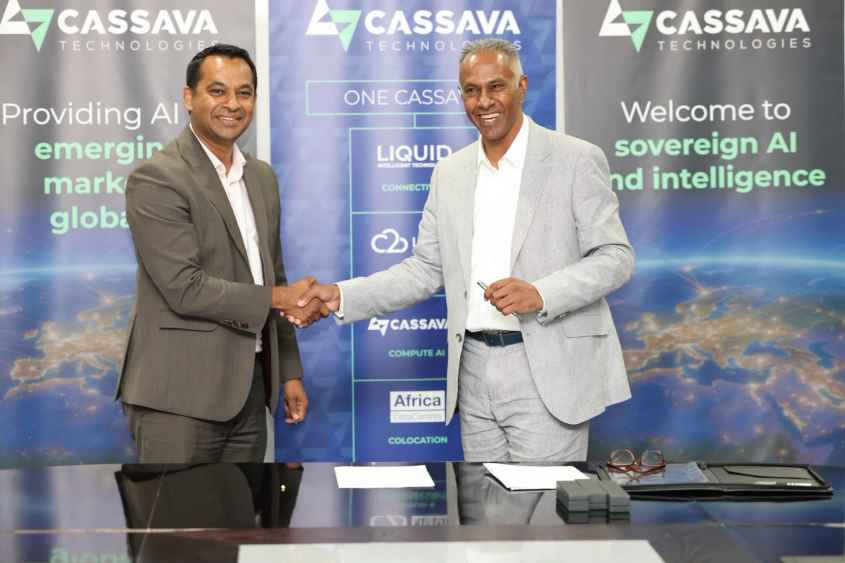
CAPE TOWN, South Africa, November 18, 2026/APO Group/ –Cassava Technologies (https://www.CassavaTechnologies.com/), a global technology company of African heritage, and Mauritius Telecom (MT) have signed a memorandum of understanding (MoU) at Africa Tech Festival to develop a strategic partnership focused on strengthening compute and model access for MT’s AI services and exploring opportunities for myt Learn, MT’s AI-powered education platform, in South Africa and other African markets.


Cassava’s NVIDIA-powered AI Factory in Cape Town is Africa’s most powerful supercomputer. The partnership combines this computing scale, Cassava’s AI platforms and regional reach with MT’s own AI products, local language capabilities and operating experience.

This partnership brings together products we have developed and Cassava’s infrastructure and reach to take that work further

“Realising AI’s promise in Africa requires more than potential; it takes infrastructure, technology, and proven expertise. By pairing Mauritius Telecom’s AI products and operating experience with Cassava’s AI infrastructure and reach, we aim to bring locally relevant AI services and education solutions to more African markets,” said Ziaad Suleman, SVP Cassava Technologies for South Africa and Botswana.

“We are building AI capability in Mauritius that can also serve other African markets. With myt Learn, we are already putting that capability to work in our schools, supporting both students and teachers. This partnership brings together products we have developed and Cassava’s infrastructure and reach to take that work further. Our ambition is to make trusted AI useful and accessible, while ensuring that those responsible for its use retain meaningful control,” said Veemal Gungadin, CEO of Mauritius Telecom.

The companies will explore access to Cassava’s AI Factory as an additional source of on-demand computing capacity for MT’s AI offerings, alongside access to AI models through CAIMEx, Cassava’s AI platform. Cassava capacity and model access would be used only for workloads where customers permit it. These options would complement MT’s existing myt AI Cloud platform and infrastructure in Mauritius, and could support its expansion into other African markets.

In education, the partners will jointly assess opportunities for myt Learn, starting with South Africa’s public and private education sectors, with potential expansion into other Cassava markets. Created by MT and rolling out in Mauritian schools for selected grades, myt Learn provides curriculum-aligned guided lessons, a multilingual AI tutor and personalised revision. Teachers have access to performance insights and AI tools for marking, test creation and lesson preparation. The platform can be adapted to local curricula and teaching needs.

Together, the companies aim to show how telecommunications operators can bring locally relevant AI services to customers and take African-developed products into new markets.

Distributed by APO Group on behalf of Cassava Technologies.


Continue Reading

Business

Afreximbank puts trade finance and compliance at the heart of Africa’s industrial transformation

Published

on

afreximbank

The forums will also explore how digitalisation, artificial intelligence and innovative financial instruments can improve trade efficiency, reduce costs and strengthen risk management

GABORONE, Botswana, November 17, 2026/APO Group/ –Afreximbank (www.Afreximbank.com) has called for increased financing of intra-African trade, stronger regulatory compliance frameworks and greater investment in value-added production to accelerate the continent’s economic integration and industrial transformation.


Speaking at the opening ceremony of the inaugural jointly held Afreximbank Trade Finance Seminar and Compliance Forum in Gaborone, Mr Lesego Moseki, Governor of the Bank of Botswana, emphasised that compliance should be recognised as a strategic asset that strengthens resilience, builds trust and enhances competitiveness. He called for greater collaboration among regulators, financial institutions and development finance institutions to foster a more harmonised and efficient trading environment across Africa.

In his opening remarks at the 2026 Afreximbank Trade Finance Seminar (ATFS) and Afreximbank Compliance Forum (ACF), Mr Haytham El Maayergi, Executive Vice President, Global Trade Bank, Afreximbank, highlighted the need for trade finance and compliance frameworks to work hand in hand to unlock the full potential of the African Continental Free Trade Area (AfCFTA) and accelerate intra-African trade.

“To build an integrated African market we to finace  connects us, and we cannot expand that trade sustainably without the trust, transparency and compliance systems that underpin it.”

El Maayergi said the changing global landscape made this imperative even more urgent, with geopolitical tensions and disrupted supply chains exposing the risks of overreliance on distant markets.

“As global markets look to diversify production beyond China, Africa must position itself as a natural partner of choice. The continent has the resources, vast land and, most importantly, its people. By 2050, one in four people globally will be African. Whether this demographic advantage becomes an asset or a liability will depend on the decisions we make today.

“To seize this opportunity, Africa must trade more with itself, and that trade must be adequately financed and underpinned by trust.”

He noted that although intra-African trade grew by 5.5 per cent in 2025, it still represents only around 14 per cent of Africa’s total trade. With 50 countries having ratified the AfCFTA but only 12 actively trading under its framework, he stressed that the priority must now be translating the agreement into tangible economic opportunities.

“We have opened the market. Our task now is to make that market work.

“It is about moving from exporting raw materials to processing, manufacturing, and creating greater value here in Africa. In other words, how can we get African resources to feed African industries and African businesses to serve African markets, while creating jobs for our people and retaining value that will support the growth and prosperity of African economies?”

As global markets look to diversify production beyond China, Africa must position itself as a natural partner of choice

Botswana’s industrial transformation presents opportunities for African trade

Highlighting Botswana’s role in advancing continental integration, Mr El Maayergi cited the country’s success in developing greater domestic participation in the diamond value chain, including the relocation of De Beers Group’s global rough-diamond sales activities from London to Gaborone.

He also highlighted the Botswana Stock Exchange’s collaboration with the Nigerian Exchange Group and other African exchanges to broaden cross-border investor access to the Dangote Petroleum Refinery IPO share offer.

Acting CEO of the Botswana Investment and Trade Centre (BITC), Mr Anthony Sefako, said Botswana’s economic transformation agenda presents significant opportunities for trade finance, investment and regional value-chain development.

“Botswana is currently pursuing a bold productive transformation, shifting from reliance on diamond mining towards a digitally enabled, export-led and diversified high-income economy.

“Botswana is targeting an increase in manufacturing exports to reach 23 per cent by 2036. From battery metal refining, pharmaceutical biomanufacturing and industrial steel to renewable energy hubs and agricultural value chains.

“The country is actively commercialising bankable industrial projects that require the very trade finance and supply chain liquidity tools being discussed during this gathering.”

Financing, innovation and compliance to unlock Africa’s potential

El Maayergi outlined four priorities to advance Africa’s trade and industrialisation agenda: integration, value creation, conviction in African enterprise, and trust.

He further highlighted Afreximbank’s role for regional integration through the Pan-African Payment and Settlement System (PAPSS), which enables cross-border payments in local currencies across more than 30 African countries. He also pointed to the Bank’s financing for mineral processing, its Strategic Minerals Development Programme and support for major African enterprises, including the Dangote Group.

He also mentioned XTRA, Afreximbank’s trading platform for African trade confirmations, which has facilitated more than US$1.5 billion in transactions and help develop a more liquid market for African risk.

On compliance, he emphasised the importance of effective regulatory and due diligence frameworks that facilitate rather than constrain trade. Such frameworks are essential to enabling African banks to maintain correspondent banking relationships, attract capital and participate confidently in global financial markets.

The forums will also explore how digitalisation, artificial intelligence and innovative financial instruments can improve trade efficiency, reduce costs and strengthen risk management. Afreximbank’s Africa Trade Gateway, which brings together TRADAR for trade information, MANSA for due diligence and verification, ATEX for market access and PAPSS for payments, was highlighted as an important part of this effort.

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Business

Tüyap highlights Middle East and North Africa (MENA) sourcing opportunities at the carpet expo in Istanbul

Published

on

Tüyap

Organised by Tüyap in Istanbul, ICFE 2027 expects more than 500 exhibitors and 35,000 industry professionals, offering Middle East and North Africa buyers opportunities to meet international carpet and flooring suppliers

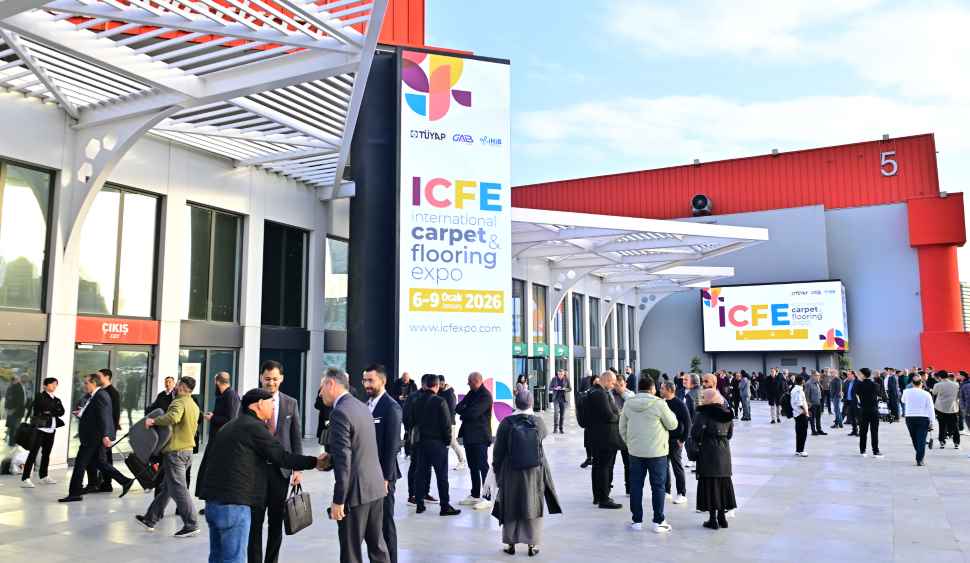
ISTANBUL, Türkiye, November 17, 2026/APO Group/ –Türkiye, a major global carpet manufacturing and exporting centre, will host the fourth International Carpet and Flooring Expo (ICFE 2027) (https://www.ICFExpo.com/en) in Istanbul from 6 to 9 January 2027. Organised by Tüyap (www.Tuyap.com.tr) Fairs and Exhibitions Organization Inc. in cooperation with the Southeastern Anatolia Carpet Exporters’ Association (GAHİB) and the Istanbul Carpet Exporters’ Association (İHİB), the event will bring international manufacturers and buyers together at the Istanbul Expo Center. Organisers expect more than 500 exhibitors and approximately 35,000 industry professionals from over 150 countries, including professional buyers from the Middle East and North Africa.


“Businesses across the Middle East and North Africa are looking for opportunities to compare products, meet manufacturers and develop supplier relationships across international markets,” said İlhan Ersözlü, General Manager at Tüyap Fairs Production Inc. “Bringing these connections together in Istanbul gives buyers and exhibitors a practical setting to explore new partnerships and understand where future trade opportunities may emerge.”

International participation expected to expand in 2027

ICFE enters its fourth edition following an event that attracted 445 exhibitors and 31,410 visitors from 127 countries in 2026. The 2027 targets point to a wider international gathering.

Manufacturers and exporters will showcase products to importers, distributors, wholesalers, retailers, architects and interior designers. The exhibition will cover handmade and machine-made carpets, rugs, textile materials, laminate and wood flooring, artificial grass and other floor coverings.

For international buyers, the event provides an opportunity to examine products from different suppliers, compare manufacturing capabilities and discuss potential commercial relationships in person.

Buyers from MENA among target markets

Professional buyers from the United Arab Emirates, Saudi Arabia and Morocco are among the international audiences expected at ICFE 2027, alongside visitors from Europe, Asia and the Americas.

For carpet and flooring businesses operating in these markets, the exhibition offers access to manufacturers and suppliers across multiple product categories. Importers and distributors can explore potential sourcing arrangements, while retailers, architects and interior designers can assess new collections, materials and design developments.

Businesses across the Middle East and North Africa are looking for opportunities to compare products

Istanbul’s location between Europe and Asia also supports the exhibition’s international business focus. Its extensive direct flight connections provide access for professionals travelling from the Gulf, North Africa and other major trading regions.

Organisers are conducting promotional activities in more than 80 countries across 6 continents. Targeted international campaigns, digital marketing and B2B matchmaking initiatives are intended to attract professional buyers and facilitate meetings with exhibitors.

Exhibition-specific customs arrangement aims to support foreign exhibitors

An exhibition-specific customs measure is also expected to support international participation at ICFE 2027.

Türkiye’s Ministry of Trade, Directorate General of Customs, has reduced the rate applied to the FOB (Free on Board) value of products brought to the exhibition by foreign exhibitors from 100% to 10% under the relevant temporary customs arrangement.

The measure applies specifically to ICFE 2027 and is intended to reduce the financial burden associated with bringing exhibition products into Türkiye.

For overseas exhibitors considering the event, the arrangement represents an additional factor in assessing the costs of participation and presenting products to potential international buyers.

Design and Industry Events Complementing Business Meetings

Alongside its commercial programme, ICFE 2027 will host industry discussions and design-focused activities.

Carpet Talks will bring industry professionals together to discuss developments in design, production, branding and the evolving carpet industry. Carpet Workshop will bring designers from different countries together to collaborate on creative projects.

These activities will complement the exhibition’s business meetings, providing manufacturers, designers and buyers with an opportunity to explore emerging approaches to carpet production and product development.

The four-day exhibition will take place at the Istanbul Expo Center in Yeşilköy from 6 to 9 January 2027. Further information is available at https://www.ICFExpo.com/en.

Distributed by APO Group on behalf of TÜYAP.


Continue Reading

Trending