Connect with us
Anglostratits

Business

To Stem Investment Elsewhere, Nigeria’s Oil Sector Requires Change (By NJ Ayuk)

Published

on

TotalEnergies

With two-thirds or more of its revenue coming from oil, investor flight is a serious problem for Nigeria

LAGOS, Nigeria, July 29, 2024/APO Group/ — 

By NJ Ayuk, Executive Chairman, African Energy Chamber (www.EnergyChamber.org).

Nigeria, a previous bright spot on big oil and gas investors’ radar screens, has dimmed substantially as investor attention is increasingly drawn to new and emerging developments in Namibia, Ivory Coast, Angola, and the Republic of Congo.

With two-thirds or more of its revenue coming from oil, investor flight is a serious problem for Nigeria.

Divestments: The Reasons and the Buyers

Big foreign players, including TotalEnergies and Shell, are exiting or shifting their priorities in Nigeria, rattled by a variety of deleterious forces: an uninviting regulatory environment, lack of transparency, safety issues, vandalism, and theft, among other factors.

For a country whose economy is dependent on fossil fuels, this divestment by majors, totaling around £17 billion since 2006, is catastrophic. Nigeria’s 37 trillion barrels of reserves can do the country no good underground.

Among those looking to pull out of the country, at least in part, is France’s TotalEnergies. The company is seeking to sell its share of Shell Petroleum Development Company of Nigeria, Limited (SPDC), although it will continue to have 18% of its investments in Nigeria.

TotalEnergies CEO Patrick Pouyanne says (https://apo-opa.co/3A2CNbe) his company hasn’t explored for oil in Nigeria for 12 years, explaining, “There is always a new legislature in Nigeria about a new petroleum law. When you have such permanent debates, it’s difficult for investors looking for long-term structure to know what direction to go.”

TotalEnergies’ stance highlights the obvious — investors want predictable environments and simple, trustworthy systems of regulation. A dearth of these factors seems to have trumped the fact that Nigeria yet contains large reserves that could be tapped.

Five global oil companies are still working in the country, but three of those — Shell, Eni, and ExxonMobil — are selling in-country assets valued at £1.8 billion, £4 billion, and £11.9 billion, respectively.

Both Shell and Eni have stated an intent to continue operating in Nigeria’s offshore sector, and ExxonMobil has expressed a commitment to continued investment in Nigeria.

Nigerian companies such as Seplat, Aiteo, and Eroton have moved quickly to buy divested assets. So has the Nigerian government, which has been named top bidder for 57 oilfields and granted licenses to 130 firms for development.

I am pleased to see indigenous companies seizing these opportunities created by divestments. I also urge them to take serious measures to control emissions and limit flaring, as large international firms have. In doing so, they will be taking care of their own families, neighbors, friends, and fellow citizens, while building top-notch reputations.

Large or small companies — Nigeria must never choose one or the other. International oil companies, national oil companies, independents, and indigenous companies all have important roles to play in Nigeria’s economic growth.

Where the Investments Are Going

As I said, Ivory Coast, Namibia, the Republic of Congo, and Angola are drawing investors’ attention away from Nigeria.

Shell is pursuing deepwater blocks in Ivory Coast for exploration, while large Italian firm Eni has just added offshore Block CI-205 to its vast Murene Bailene discovery of 2021. Production from the Baleine discovery has shot Ivory Coast’s production to 30,000 barrels per day (bpd), a number that is expected to rise an astonishing 556% to 200,000 bpd by 2027.

All of this is happening while Ivory Coast is successfully emphasizing carbon-reducing technologies and natural gas as a transition fuel.

Overseas investment has also spurred significant recent discoveries in Namibia, earning the country the nickname, “new Guyana.” (That South American country’s crude oil production soared by a yearly average of 98,000 bpd from 2020 to 2023, making Guyana the third-fastest growing non-OPEC oil-producing country.)

Notable among recent Namibian discoveries is TotalEnergies’ Venus Discovery, for which the French major is seeking approval to move ahead by the close of 2025. Venus is expected to produce up to 180,000 bpd of oil.

Nigeria must work tirelessly to mitigate not only government instability, but other factors that discourage investment

TotalEnergies is also looking to invest $600 million in exploration and production in the Republic of Congo’s Moho Nord deep offshore field this year. As I have said before, this kind of investment is evidence that the company is in the Republic of Congo to stay.

Angola, too, has become a major investment site for TotalEnergies. The firm’s CEO has said (https://apo-opa.co/3A2CNbe) it will invest $6 billion in energy in Angola, as “a country with a more stable policy framework.”

Nigerian Reforms and Rules Changes

March 2024 brought some much-needed federal policy reforms to Nigeria’s petroleum industry in the form of presidential executive orders and policy directives. The reforms are aimed at improving the country’s investment environment and reinvigorating growth in its petroleum industry.

The changes include investor tax credits, an investment allowance, simplifying contracting procedures, and easing local content rules.

The tax credits apply to non-associated gas greenfields — that is, new ventures — both onshore and in shallow water and vary according to hydrocarbon liquids (HCL) content. The credit becomes an allowance after 10 years, making it an ongoing investment incentive.

A 25% investment allowance has also been added for qualified capital expenditures (QCEs) on plants and equipment, cutting down on large capital outlays and thus encouraging industry growth and improvement. 

Changes in third-party contracting aim to decrease both contracting costs and the time it takes for companies to get to production. The new rules encompass financial approval thresholds, consent timelines, and contract duration.  The requirements call for only one level of approval at each contract stage and establish time limits for completion of approvals.

Local content requirements have also been modified to take local capacity into account, enabling investors to keep their projects cost competitive.

Overall, the executive orders help clear up the regulatory fog that has been discouraging major investment and will hopefully help the country regain its status among investors.

The Economy and the New Licensing Round

It’s been estimated that Nigeria requires USD 25 billion of investment per year to keep its production at 2 million bpd — a level that will sustain the nation’s economy. Historically, 2014 marked the peak of investment in Nigerian oil at USD 22.1 billion.

The federal government is strategizing for increased oil production to meet this fiscal need in an environment where vandals have attacked pipelines and stolen oil — factors the government has claimed as reasons it has fallen short of its 1.5 million bpd OPEC quota. (Though not by much: for example, production in March 2024 declined from 1.47 million bpd to 1.45 million bpd, according to S&P Global Commodity Insights.)

Looking to improve those figures in the remainder of 2024, the government’s target is 1.78 million bpd. Although recent problems on the Trans Niger Pipeline and maintenance by oil companies have dropped output, President Bola Tinubu expects a return to target levels.

By using every available well to increase production and revenue, the government aspires to increase crude production to 2.6 million bpd by 2027.

In April 2024, Nigeria began a new oil and gas licensing round, with an attached promise to investors that the process would be transparent. The new round is intended to help stem the flow of investments to African competitors like Angola and Namibia by easing the process of acquiring oil blocks.

The new licensing round offers 19 onshore and deepwater oil blocks, plus an additional 17 deep offshore blocks. These were chosen for their attractiveness to foreign investors who have both the necessary finances and technical savvy to develop the areas.

Successful bidders will be held to precise exploration timelines.

Bidding had begun on seven offshore blocks in 2022 but was delayed for the installation of a new government — just the sort of shaky situation large foreign investors like to avoid.

With that experience in mind, Nigeria must work tirelessly to mitigate not only government instability, but other factors that discourage investment, be they regulatory hurdles, lack of transparency, or safety and security issues.

Distributed by APO Group on behalf of African Energy Chamber.
Business

SLB commissions new fluids systems plant in Pemba to support Mozambique’s offshore energy development

Published

on

Mozambique

New facility expands in-country drilling and completion fluids capability, advancing the next phase of SLB’s growth in Mozambique

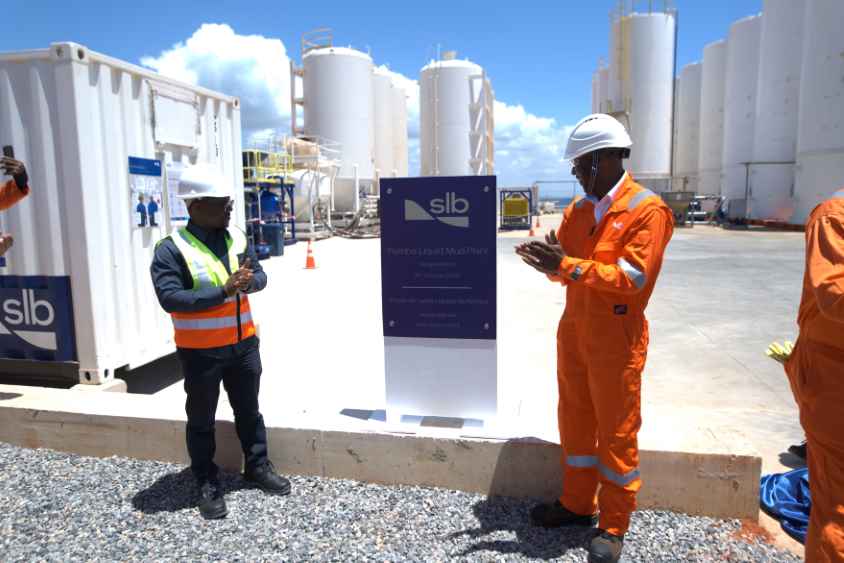
PEMBA, Mozambique, October 9, 2026/APO Group/ –SLB (NYSE: SLB) (www.SLB.com) announced the opening of a new fluids systems plant in Pemba, Mozambique. The new facility strengthens in-country capacity to prepare, store and deliver drilling and completion fluids for offshore operations, reinforcing the infrastructure needed as Mozambique’s offshore activity grows and its role as a strategic energy hub for East Africa continues to expand.

The commissioning of the plant, also known as a liquid mud plant, coincides with SLB marking 70 years of operations in Mozambique. It reflects the company’s long-term commitment to investing in people, infrastructure and capability that support the country’s long-term offshore energy development plans.


With an initial storage capacity of 21,000 barrels, the liquid mud plant provides a scalable platform for future growth, supporting multiple customers and rising offshore activity while improving logistics and enhancing operational flexibility.

As SLB marks 70 years in Mozambique, this investment reflects our confidence in the country’s future and our commitment to supporting its energy ambitions

“As SLB marks 70 years in Mozambique, this investment reflects our confidence in the country’s future and our commitment to supporting its energy ambitions,” said Miguel Baptista, Central, East and Southern Africa, Managing Director, SLB. The new liquid mud plant strengthens local energy infrastructure, expands opportunities for local content development, and enhances our ability to support customers as they deliver some of Africa’s most significant offshore energy resources.”

The liquid mud plant project was delivered with strong local participation and that momentum is expected to continue into operations. During project delivery, more than 100 jobs were created in Pemba with nationals representing 80% of the workforce, reflecting a focus on building local capability.

The project was delivered with a strong focus on safety, operational integrity, and quality, achieving more than 67,000 hours worked without a recordable safety incident.

This key infrastructure strengthens SLB’s ability to support consistent service quality and enhance supply chain readiness for increasing offshore activity across Mozambique, supporting customers execute safely and efficiently while developing local skills and expertise.

Key Points:

  • SLB has commissioned a new fluids system plant in Pemba, expanding in-country drilling and completion fluids capability for offshore operations.
  • With an initial storage capacity of 21,000 barrels, the facility provides a scalable platform to support growing offshore activity in Mozambique.
  • The investment marks the next phase of SLB’s growth in Mozambique, strengthening local capability and supporting long-term offshore energy development.

Distributed by APO Group on behalf of SLB.


Continue Reading

Business

South African Energy Storage Association (SAESA) welcomes 4,600 MW battery storage prioritisation and calls for integrated energy planning

Published

on

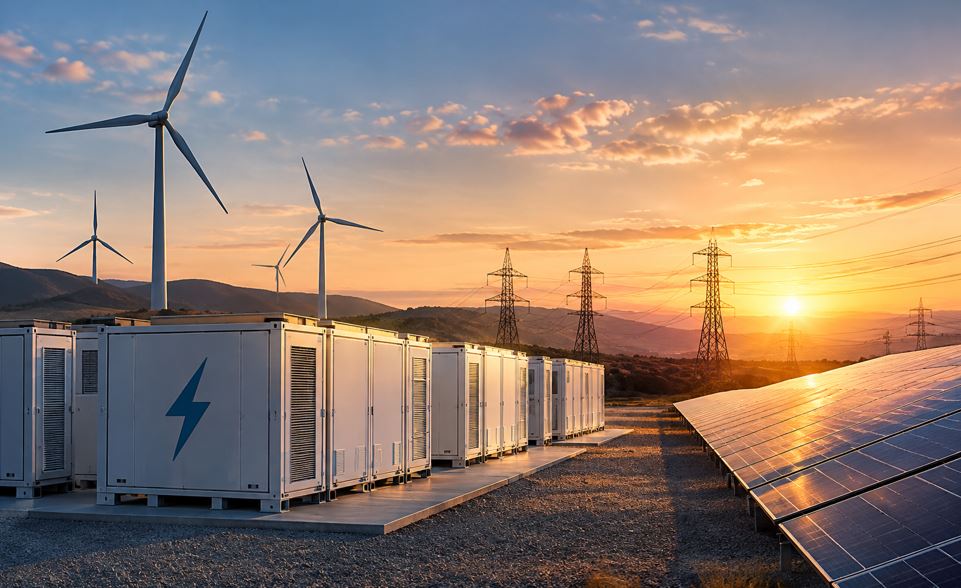
Battery energy storage systems (BESS) are becoming critical system infrastructure, supporting flexibility, reducing avoidable curtailment, shifting energy into periods of demand and strengthening security of supply

JOHANNESBURG, South Africa, October 9, 2026/APO Group/ –The South African Energy Storage Association (SAESA) (www.SAESA.org.za) welcomes the prioritisation of 4,600 MW of battery energy storage under the first Integrated Resource Plan (IRP) 2025 Section 34 determination.


The timing is significant. Recent Integrated Energy Plan (IEP) modelling and assumptions discussions highlighted a fundamental shift that South Africa’s energy planning now needs to capture: we cannot plan the future power system by counting megawatts of generation alone.

We must plan for when energy is available, where it is available, how it moves through a constrained grid and how it is stored and dispatched when the system needs it most.

The announcement reinforces that shift. Battery energy storage systems (BESS) are becoming critical system infrastructure, supporting flexibility, reducing avoidable curtailment, shifting energy into periods of demand and strengthening security of supply.

For SAESA, the message for the IEP is clear: storage, flexibility and system services must be modelled as integral components of South Africa’s future electricity architecture, with their contribution considered from the outset of generation planning.

“The IEP must plan the power system we are becoming, not simply model the power system we have inherited,” says SAESA.

The IEP must plan the power system we are becoming, not simply model the power system we have inherited

Partnership with C&I Energy + Storage Summit

SAESA is an association partner of the C&I Energy + Storage Summit, created by VUKA Group, taking place on 28–29 October 2026 at The Maslow Hotel, Sandton, Johannesburg.

The summit brings together commercial and industrial energy users, project developers, financiers, regulators and solution providers to explore practical approaches to energy security, procurement and storage deployment.

For businesses assessing how storage can support their operations, the event offers an opportunity to meet SAESA and engage with the wider energy community on the decisions shaping South Africa’s evolving electricity system.

Commercial and industrial energy decision-makers are invited to apply to attend as hosted buyers. Qualifying buyers receive complimentary summit access and curated opportunities to engage with industry partners.


Meet SAESA at C&I Energy + Storage Summit: Join the Hosted Buyer Programme

The Hosted Buyer Programme connects commercial and industrial energy decision-makers with solution providers shaping South Africa’s evolving private energy market.

Qualified energy buyers receive complimentary access to the summit and curated engagement with industry partners exploring energy procurement, storage deployment and project development.

Apply for the Hosted Buyer Programme (https://apo-opa.co/4ehLijJ)

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Business

Afreximbank welcomes launch of Africa Credit Rating Agency as an important step in strengthening Africa’s financial architecture

Published

on

Expanding credible rating coverage can improve the information available to investors and support the development of deeper domestic and regional capital markets

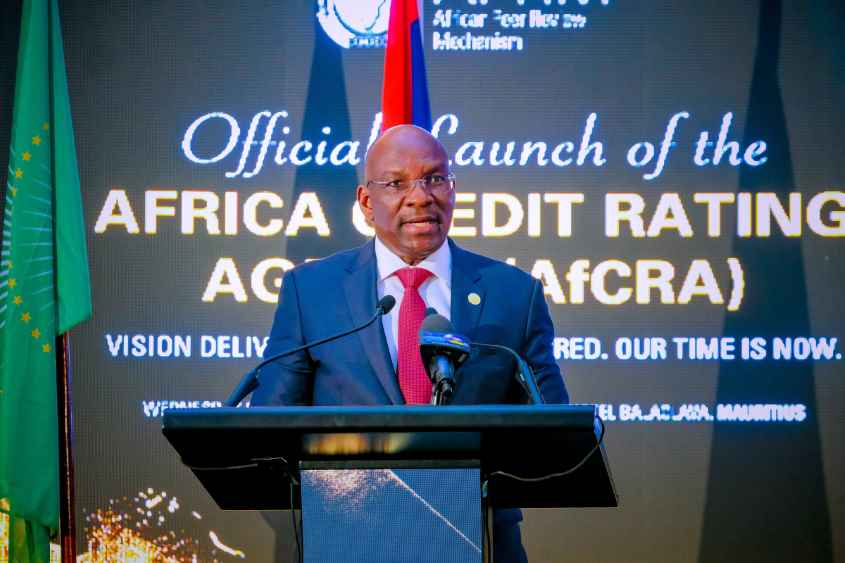
PORT LOUIS, Mauritius, October 8, 2026/APO Group/ –African Export-Import Bank (Afreximbank) (www.Afreximbank.com) welcomes today’s launch of the Africa Credit Rating Agency (AfCRA), an important milestone in strengthening Africa’s financial architecture and expanding the continent’s capacity to generate credible, independent analysis of African credit risk.


Credit ratings play an important role in determining access to capital, influencing investor perceptions and shaping the cost at which governments, institutions and businesses can finance development. It is therefore essential that assessments of African credit risk are independent, rigorous and evidence-based, while reflecting a complete understanding of the structures, institutions and economic realities being assessed.

The establishment of AfCRA adds an important African-led source of credit opinion to the market. Its value will not be measured by whether it produces more favourable ratings, but by the credibility of its analysis, the quality of its data and transparency of its methodology, and its ability to deepen understanding of African sovereigns, sub-sovereigns and corporate credit.

This is particularly important given that many African issuers remain unrated, while local-currency and sub-sovereign markets continue to have limited rating coverage. Expanding credible rating coverage can improve the information available to investors and support the development of deeper domestic and regional capital markets.

AfCRA must set a new benchmark for the continent, maintain its independence, and remain wholly owned and controlled by Africans

Alongside fellow members of the Alliance of African Multilateral Financial Institutions (AAMFI), Afreximbank has consistently maintained that African Multilateral Financial Institutions should be assessed on the basis of their fundamentals, performance, legal frameworks, mandates and operating models. Ensuring that these institutional characteristics are properly understood is essential to achieving informed, balanced and credible assessments of African risk.

Commenting on the uniqueness of the African market, and need for AfCRA’s rating methodology to reflect this, Mr Denys Denya, Senior Executive Vice President, Afreximbank, said: “The rating methodology AfCRA develops must recognise the uniqueness of our environment and its institutional structures. The Agency must set its own standards and not follow those set elsewhere — it must build a unique identity that conforms to an ‘African best practice.”

Highlighting the need for the autonomy of the Africa Credit Rating agency as it takes off, Mr Denya added: “Most importantly, AfCRA must set a new benchmark for the continent, maintain its independence, and remain wholly owned and controlled by Africans. We must all use it, and in return expect a complete assessment of where we (Africa) stand: the strengths the market has ignored, and the weaknesses we still need to fix.”

AfCRA should therefore be seen as complementary to existing international and regional rating agencies, broadening the range of credible analysis available to investors and issuers while strengthening competition, transparency and analytical capacity within Africa’s credit markets.

As Africa seeks to mobilise the scale of capital required for industrialisation, trade, infrastructure and economic transformation, credible African institutions that improve information, strengthen market confidence and deepen the continent’s financial markets will become increasingly important.

Afreximbank congratulates the African Union, the African Peer Review Mechanism (APRM) and all those involved in bringing AfCRA from concept to launch, and looks forward to the contribution the Agency will make to deeper, more transparent and more efficient African capital markets.

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Trending