Connect with us

Business

To Stem Investment Elsewhere, Nigeria’s Oil Sector Requires Change (By NJ Ayuk)

Published

on

TotalEnergies

With two-thirds or more of its revenue coming from oil, investor flight is a serious problem for Nigeria

LAGOS, Nigeria, July 29, 2024/APO Group/ — 

By NJ Ayuk, Executive Chairman, African Energy Chamber (www.EnergyChamber.org).

Nigeria, a previous bright spot on big oil and gas investors’ radar screens, has dimmed substantially as investor attention is increasingly drawn to new and emerging developments in Namibia, Ivory Coast, Angola, and the Republic of Congo.

With two-thirds or more of its revenue coming from oil, investor flight is a serious problem for Nigeria.

Divestments: The Reasons and the Buyers

Big foreign players, including TotalEnergies and Shell, are exiting or shifting their priorities in Nigeria, rattled by a variety of deleterious forces: an uninviting regulatory environment, lack of transparency, safety issues, vandalism, and theft, among other factors.

For a country whose economy is dependent on fossil fuels, this divestment by majors, totaling around £17 billion since 2006, is catastrophic. Nigeria’s 37 trillion barrels of reserves can do the country no good underground.

Among those looking to pull out of the country, at least in part, is France’s TotalEnergies. The company is seeking to sell its share of Shell Petroleum Development Company of Nigeria, Limited (SPDC), although it will continue to have 18% of its investments in Nigeria.

TotalEnergies CEO Patrick Pouyanne says (https://apo-opa.co/3A2CNbe) his company hasn’t explored for oil in Nigeria for 12 years, explaining, “There is always a new legislature in Nigeria about a new petroleum law. When you have such permanent debates, it’s difficult for investors looking for long-term structure to know what direction to go.”

TotalEnergies’ stance highlights the obvious — investors want predictable environments and simple, trustworthy systems of regulation. A dearth of these factors seems to have trumped the fact that Nigeria yet contains large reserves that could be tapped.

Five global oil companies are still working in the country, but three of those — Shell, Eni, and ExxonMobil — are selling in-country assets valued at £1.8 billion, £4 billion, and £11.9 billion, respectively.

Both Shell and Eni have stated an intent to continue operating in Nigeria’s offshore sector, and ExxonMobil has expressed a commitment to continued investment in Nigeria.

Nigerian companies such as Seplat, Aiteo, and Eroton have moved quickly to buy divested assets. So has the Nigerian government, which has been named top bidder for 57 oilfields and granted licenses to 130 firms for development.

I am pleased to see indigenous companies seizing these opportunities created by divestments. I also urge them to take serious measures to control emissions and limit flaring, as large international firms have. In doing so, they will be taking care of their own families, neighbors, friends, and fellow citizens, while building top-notch reputations.

Large or small companies — Nigeria must never choose one or the other. International oil companies, national oil companies, independents, and indigenous companies all have important roles to play in Nigeria’s economic growth.

Where the Investments Are Going

As I said, Ivory Coast, Namibia, the Republic of Congo, and Angola are drawing investors’ attention away from Nigeria.

Shell is pursuing deepwater blocks in Ivory Coast for exploration, while large Italian firm Eni has just added offshore Block CI-205 to its vast Murene Bailene discovery of 2021. Production from the Baleine discovery has shot Ivory Coast’s production to 30,000 barrels per day (bpd), a number that is expected to rise an astonishing 556% to 200,000 bpd by 2027.

All of this is happening while Ivory Coast is successfully emphasizing carbon-reducing technologies and natural gas as a transition fuel.

Overseas investment has also spurred significant recent discoveries in Namibia, earning the country the nickname, “new Guyana.” (That South American country’s crude oil production soared by a yearly average of 98,000 bpd from 2020 to 2023, making Guyana the third-fastest growing non-OPEC oil-producing country.)

Notable among recent Namibian discoveries is TotalEnergies’ Venus Discovery, for which the French major is seeking approval to move ahead by the close of 2025. Venus is expected to produce up to 180,000 bpd of oil.

Nigeria must work tirelessly to mitigate not only government instability, but other factors that discourage investment

TotalEnergies is also looking to invest $600 million in exploration and production in the Republic of Congo’s Moho Nord deep offshore field this year. As I have said before, this kind of investment is evidence that the company is in the Republic of Congo to stay.

Angola, too, has become a major investment site for TotalEnergies. The firm’s CEO has said (https://apo-opa.co/3A2CNbe) it will invest $6 billion in energy in Angola, as “a country with a more stable policy framework.”

Nigerian Reforms and Rules Changes

March 2024 brought some much-needed federal policy reforms to Nigeria’s petroleum industry in the form of presidential executive orders and policy directives. The reforms are aimed at improving the country’s investment environment and reinvigorating growth in its petroleum industry.

The changes include investor tax credits, an investment allowance, simplifying contracting procedures, and easing local content rules.

The tax credits apply to non-associated gas greenfields — that is, new ventures — both onshore and in shallow water and vary according to hydrocarbon liquids (HCL) content. The credit becomes an allowance after 10 years, making it an ongoing investment incentive.

A 25% investment allowance has also been added for qualified capital expenditures (QCEs) on plants and equipment, cutting down on large capital outlays and thus encouraging industry growth and improvement. 

Changes in third-party contracting aim to decrease both contracting costs and the time it takes for companies to get to production. The new rules encompass financial approval thresholds, consent timelines, and contract duration.  The requirements call for only one level of approval at each contract stage and establish time limits for completion of approvals.

Local content requirements have also been modified to take local capacity into account, enabling investors to keep their projects cost competitive.

Overall, the executive orders help clear up the regulatory fog that has been discouraging major investment and will hopefully help the country regain its status among investors.

The Economy and the New Licensing Round

It’s been estimated that Nigeria requires USD 25 billion of investment per year to keep its production at 2 million bpd — a level that will sustain the nation’s economy. Historically, 2014 marked the peak of investment in Nigerian oil at USD 22.1 billion.

The federal government is strategizing for increased oil production to meet this fiscal need in an environment where vandals have attacked pipelines and stolen oil — factors the government has claimed as reasons it has fallen short of its 1.5 million bpd OPEC quota. (Though not by much: for example, production in March 2024 declined from 1.47 million bpd to 1.45 million bpd, according to S&P Global Commodity Insights.)

Looking to improve those figures in the remainder of 2024, the government’s target is 1.78 million bpd. Although recent problems on the Trans Niger Pipeline and maintenance by oil companies have dropped output, President Bola Tinubu expects a return to target levels.

By using every available well to increase production and revenue, the government aspires to increase crude production to 2.6 million bpd by 2027.

In April 2024, Nigeria began a new oil and gas licensing round, with an attached promise to investors that the process would be transparent. The new round is intended to help stem the flow of investments to African competitors like Angola and Namibia by easing the process of acquiring oil blocks.

The new licensing round offers 19 onshore and deepwater oil blocks, plus an additional 17 deep offshore blocks. These were chosen for their attractiveness to foreign investors who have both the necessary finances and technical savvy to develop the areas.

Successful bidders will be held to precise exploration timelines.

Bidding had begun on seven offshore blocks in 2022 but was delayed for the installation of a new government — just the sort of shaky situation large foreign investors like to avoid.

With that experience in mind, Nigeria must work tirelessly to mitigate not only government instability, but other factors that discourage investment, be they regulatory hurdles, lack of transparency, or safety and security issues.

Distributed by APO Group on behalf of African Energy Chamber.

Business

South Sudan Targets New Energy Investment as African Financing Options Expand

Published

on

The launch of the Africa Energy Bank, regional banking partnerships and upstream exploration activity bring new financing opportunities into focus at SSOP 2026

JUBA, South Sudan, November 9, 2026/APO Group/ –South Sudan is seeking new investment to expand oil production, develop exploration acreage and strengthen petroleum infrastructure as African financial institutions increase their focus on energy project financing. With 14 exploration blocks available and plans to raise crude output from approximately 174,000 barrels per day (bpd) to 230,000 bpd in the near term, the country is targeting capital for both new developments and existing producing assets.


The upcoming South Sudan Oil & Power (SSOP) conference – scheduled for November 24-25, 2026, in Juba – will serve as the premier venue for investors, development finance institutions (DFIs) and project developers to structure funding, forge partnerships and allocate capital across the nation’s evolving energy value chain.

South Sudan Advances Upstream, Infrastructure Opportunities  

South Sudan’s investment pipeline spans exploration, enhanced oil recovery, refining, crude transportation and power infrastructure. With an estimated 3.5 billion barrels of proven oil reserves, the country is seeking to attract new operators and technical partners to develop available acreage while improving production efficiency across mature fields.

Regional national oil companies are already advancing exploration activities. The South African National Petroleum Company (SANPC), through its subsidiary Strategic Fuel Fund, holds a 90% interest in Block B2 alongside national oil company Nile Petroleum Corporation (Nilepet). SANPC is preparing further exploration work, including a planned 2D seismic campaign, creating opportunities for geophysical contractors, equipment suppliers and technical service providers.

Nilepet is also pursuing investment in downstream infrastructure, including a proposed 350-kilometre crude pipeline connecting the Tharjiath oilfields in Block 5A with the Paloch oilfields in Blocks 3 and 7. The company is seeking strategic investment partnerships for refinery development and the pipeline project, alongside plans to expand fuel storage, distribution and LPG infrastructure.

Development Finance Expands Investment Options 

The formal establishment of the Africa Energy Bank on October 31, 2026, marks a significant development in regional energy financing. Created by the African Petroleum Producers’ Organisation and Afreximbank, the institution has $5 billion in authorized capital and is expected to begin financing projects in 2027.

The bank aims to address funding gaps across Africa’s oil and gas sector, with an initial focus on regional infrastructure, including pipelines, refining and domestic energy development. Its establishment could create additional financing options for South Sudan’s petroleum projects, although no funding commitments to the country have been announced.

Beyond the AEB, development finance institutions are already supporting South Sudan’s wider energy infrastructure. The World Bank is financing the $53 million South Sudan Energy Sector Access and Institutional Strengthening Project, which includes grid expansion in Juba and support for decentralized electrification. Meanwhile, the African Development Bank Group has approved $153.66 million in financing for the Uganda–South Sudan electricity interconnection project, supporting regional power trade and improved electricity access.

Afreximbank also maintains a trade finance partnership with South Sudan’s Kush Bank, which was appointed as an intermediary in 2023. The arrangement provides a framework for trade finance instruments, including letters of credit and bank guarantees, that can support equipment imports and commercial activity. Access to these instruments could benefit domestic suppliers and service companies participating in the energy sector.

SSOP 2026 Connects Energy Projects with Global Capital 

As South Sudan seeks to accelerate production growth and expand its energy infrastructure, SSOP 2026 will provide a platform to connect priority projects with regional and international financiers.

Returning as the country’s official energy investment platform, the conference will bring together government representatives, national and international oil companies, development finance institutions, commercial banks, private investors and technology providers to explore financing structures, investment partnerships and project development opportunities.

Held under the theme Resource Renaissance – Energy-Fueled Growth for a New Generation, SSOP 2026 will focus on mobilizing capital across exploration, production optimization, refining, petroleum transportation and power infrastructure, supporting South Sudan’s efforts to translate its energy resources into commercial development.

For more information, visit https://SouthSudanOilPower.com/.

Distributed by APO Group on behalf of Energy Capital & Power.


Continue Reading

Business

Zambia–Lobito Railway Moves Towards Financial Close as President Hichilema Meets Africa Finance Corporation (AFC) Leadership

Published

on

Project advances towards financing with preferred EPC bidders selected and letters of intent covering approximately 2 million tonnes a year signed

LUSAKA, Zambia, November 6, 2026/APO Group/ –His Excellency Hakainde Hichilema, President of the Republic of Zambia, has received a delegation from Africa Finance Corporation (AFC) (www.AfricaFC.org), led by its President and Chief Executive Officer, Samaila Zubairu, to review progress on the Zambia–Lobito Railway Project. AFC, the continent’s leading infrastructure solutions provider, is the lead sponsor and developer of the project.

The approximately 830-kilometre railway will connect Chingola in Zambia’s Copperbelt to Luacano in Angola, where it will link with the existing Benguela Railway and provide direct access to the Atlantic Ocean through the Port of Lobito.


A strategic component of the broader Lobito Corridor initiative, the project has reached several important development milestones. AFC last month announced preferred bidders for the engineering, procurement and construction (EPC) contracts for the Angolan and Zambian sections, following an international competitive tender. The project has also signed memoranda of understanding and letters of intent with prospective railway users covering approximately 2 million tonnes of freight a year.

Every tonne that leaves Zambia unprocessed takes jobs away with it

In addition to providing a direct Atlantic export route for Zambia’s copper and critical minerals, the project is being developed as an integrated economic corridor supporting agricultural exports, petroleum logistics, manufacturing and regional trade. Transit from the Copperbelt to the Port of Lobito is expected to take approximately seven days.

The project’s commercial strategy targets approximately 5 million tonnes of annual freight at steady state, comprising petroleum products, agricultural commodities, copper, cobalt, zinc and other industrial cargo. AFC is targeting financial close in 2027.

Discussions focused on continued collaboration between AFC and the Government of Zambia on the project’s next steps, including the railway’s right of way and land for associated agricultural, petroleum and freight-handling facilities. The meeting also considered rail sector policy measures to support the corridor’s long-term competitiveness, including integration with the Zambia Railways network and the Chingola–Ndola line.

President Hichilema reaffirmed the railway’s importance to Zambia’s economic development and regional integration. He said: “The Zambia–Lobito Railway is central to our vision of transforming Zambia into a competitive regional hub for trade, manufacturing, agriculture and mineral value addition. By connecting our productive sectors to international markets more efficiently, we can reduce logistics costs, attract investment and create jobs. We welcome AFC’s progress and will continue working closely together to advance this strategic project.”

Samaila Zubairu, President and Chief Executive Officer of AFC, said: “Every tonne that leaves Zambia unprocessed takes jobs away with it. This railway changes that. Starting in Chingola, it gives Zambia a seven-day route to the Atlantic and every reason to process, manufacture and add value at home. With preferred EPC bidders selected and strong interest from freight users, we are now working with the Governments of Zambia and Angola, the African Development Bank, the Government of Italy and our other partners to reach financial close. We are building a railway. Zambia will build an economy on it.”

AFC continues to work with the Governments of Angola and Zambia, the European Union, the United States Government, the Government of Italy and the African Development Bank, alongside Italian development finance institution CDP and Italian export credit agency SACE, to bring the Zambia–Lobito Railway into construction.

Distributed by APO Group on behalf of Africa Finance Corporation (AFC).


Continue Reading

Business

Mukuru Partners with Flash to Add 170,000 Cash Pay-in Points Across South Africa

Published

on

New partnership brings remittance payments into township, peri-urban and rural spaza shops nationwide

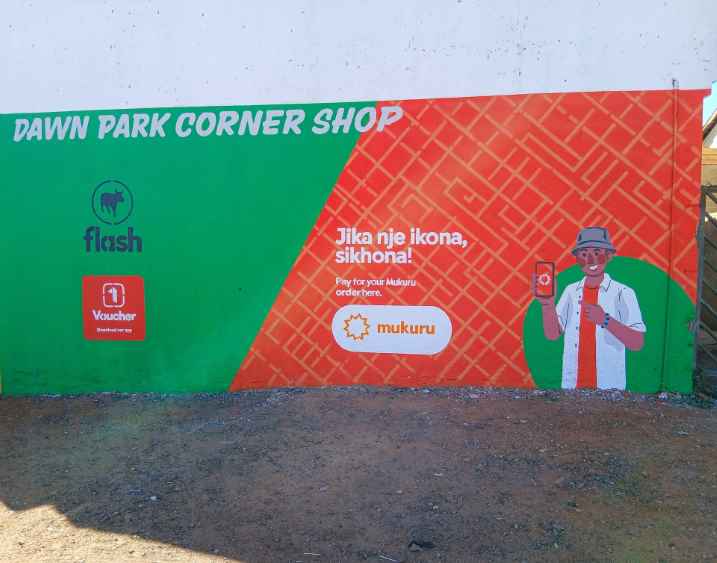
JOHANNESBURG, South Africa, November 6, 2026/APO Group/ –Mukuru (www.Mukuru.com), a leading financial services provider, has partnered with Flash, a payments technology company with an extensive network of spaza shops across South Africa, adding 170,000 cash pay-in points where customers can now pay for their Mukuru remittance orders. The network includes Flash’s broader merchant footprint, giving Mukuru access to locations through Flash and its partner networks. These new locations are now operational, reducing the time and distance many customers currently travel to make a payment.

Previously, customers often had to travel to banks or dedicated payment outlets to pay for their Mukuru orders. Now, they can simply visit a spaza shop close to home, work or where they usually shop.

For people in townships, peri-urban and rural areas who rely on cash and have traditionally had limited access to formal pay-in points, particularly South Africa’s migrant communities, this change removes a real barrier and makes it easier to send money home. With these pay-in points inside spaza shops, Mukuru’s services become part of places people already go, meaning fewer extra trips and more timely payments.

Every additional pay-in point represents one less barrier for a customer trying to send money home

“Every additional pay-in point represents one less barrier for a customer trying to send money home,” said Erone Kyte, Commercial Manager: Cross-Border Remittances at Mukuru. “Our partnership with Flash gives us the scale to bring Mukuru’s services into the everyday spaces our customers already know and trust. It’s a meaningful step in making remittances simpler, more accessible and genuinely closer to the communities we serve.”

For Mukuru, working with Flash means reaching even more customers in underserved urban, township, and rural areas. By leveraging Flash’s established network, Mukuru can now offer cash pay-in options where they didn’t exist before. The expanded network is expected to help more people access Mukuru’s services, support growth in its South African customer base, and make cross-border payments more convenient.

Rens Rezelman, General Manager for Flash’s Merchant Division, commented, “Flash works to bridge the digital product and payments gap between businesses and consumers across the country. Launching Mukuru across our network presents another opportunity to bring a familiar brand closer to the people who need it most.”

The sector is now recognised as a R750 billion  industry. According to data tracked by Trade Intelligence, total turnover recently reached R197 billion, growing at roughly 15% annually. Research confirms that traditional trade and spaza shops are growing faster than large supermarket chains, with almost 80% of South African households shopping at these traditional trade outlets regularly. (https://apo-opa.co/4iDwZr8) Bringing Mukuru payments to these stores is a natural fit and helps shop owners draw in more customers and offer more services to their communities. Mukuru and Flash will build awareness of the new pay-in option through store, digital, and community promotions in the coming months.

This partnership is part of Mukuru’s ongoing drive to make cash pay-ins easier and improve access to remittance services for people living and working in areas with limited formal financial services. Over the past two years, the company has made similar moves to make its payment network bigger and more accessible across the region.

Mukuru customers looking to pay closer to home can easily find their nearest participating Flash pay-in point using the Mukuru app or website.

Distributed by APO Group on behalf of Mukuru.


Continue Reading

Trending

Exit mobile version