Connect with us

Energy

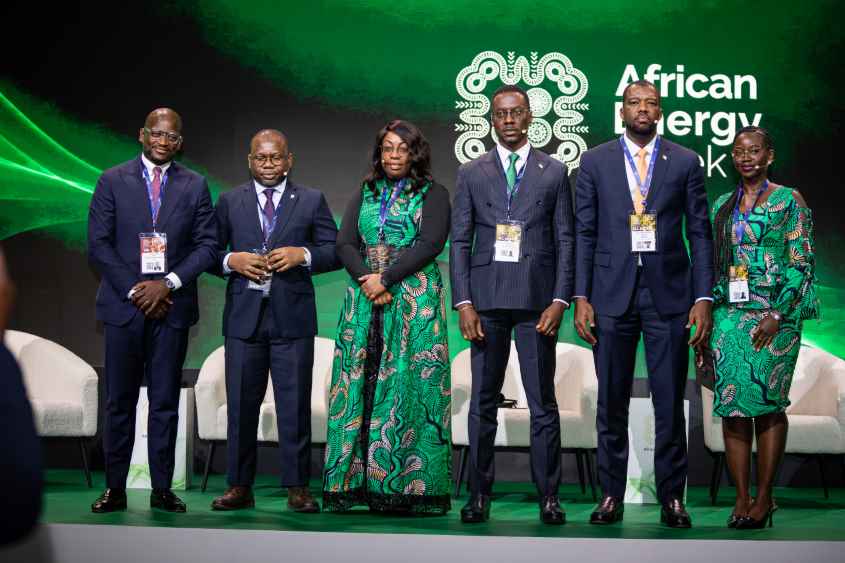
Nigeria’s Nigerian Content Development and Monitoring Board (NCDMB) Secures Key Local Content Role at African Energy Week (AEW) 2026

Published

on

African Energy Chamber

NCDMB joins AEW 2026 as Local Content Partner, showcasing Nigeria’s capacity-building drive, industrial projects and funding initiatives aimed at boosting indigenous participation and investor confidence

CAPE TOWN, South Africa, March 27, 2026/APO Group/ –Parastatal regulatory agency the Nigerian Content Development and Monitoring Board (NCDMB) will participate at this year’s African Energy Week (AEW) 2026 as an official Local Content Partner, reinforcing its leadership in advancing indigenous capacity across Africa’s energy sector. Taking place from October 12–16 in Cape Town, the event will provide a strategic platform for the NCDMB to showcase Nigeria’s evolving local content framework and investment opportunities.


In parallel, the NCDMB continues to strengthen its domestic capabilities, most recently launching a 12-month pipeline engineering training program in March 2026 for 33 young engineers in Port Harcourt. Delivered in partnership with Renaissance Africa Energy and MJD Oilfield Services, the initiative focuses on pipeline pigging, corrosion control and integrity management, aligning workforce development with major infrastructure projects like the Ajaokuta-Kaduna-Kano Gas Pipeline.


On the infrastructure front, the board is advancing construction of a 204-room Radisson-managed hotel and conference center in Yenagoa, scheduled for commissioning this December. Positioned adjacent to the Nigerian Content Tower, the facility is designed to support industry collaboration. Complementing this, the NCDMB has commissioned a Clinical Skills and Simulation Laboratory at Bayelsa Medical University, enhancing healthcare capacity in host communities through cutting-edge training technologies.


The participation of the NCDMB at AEW 2026 is a strong signal that Africa is serious about building its own capacity and retaining value within the continent

Industrial expansion remains a core pillar of the board’s strategy. Under the Nigerian Oil and Gas Parks Scheme, pilot parks in Odukpani and Emeyal-1 are nearing completion and are expected to generate around 2,000 jobs each. These shared-services industrial hubs are designed to localize manufacturing, reduce costs and enable indigenous firms to scale production across upstream and midstream value chains.


From a financial and policy standpoint, the NCDMB is deploying multiple funding mechanisms, including a $100 million equity investment scheme, a $500 million intervention fund and a $20 million women-focused initiative. Recent enforcement measures – such as stricter expatriate quota controls and mandatory compliance certification – further signal a shift toward deeper localization, transparency and long-term investor confidence in Nigeria’s oil and gas sector.


“The participation of the NCDMB at AEW 2026 is a strong signal that Africa is serious about building its own capacity and retaining value within the continent,” says NJ Ayuk, Executive Chairman, African Energy Chamber. “Local content is not just policy – it is the foundation for sustainable growth, job creation and energy security across African markets.”


As AEW 2026 convenes global investors, policymakers and operators, the inclusion of the NCDMB as a Local Content Partner underscores the growing importance of in-country value creation. With dedicated forums on skills development, technology transfer and industrialization, the event is set to drive actionable dialogue on how local content can unlock resilient, competitive and investment-ready energy ecosystems across Africa.

Distributed by APO Group on behalf of African Energy Chamber.

Business

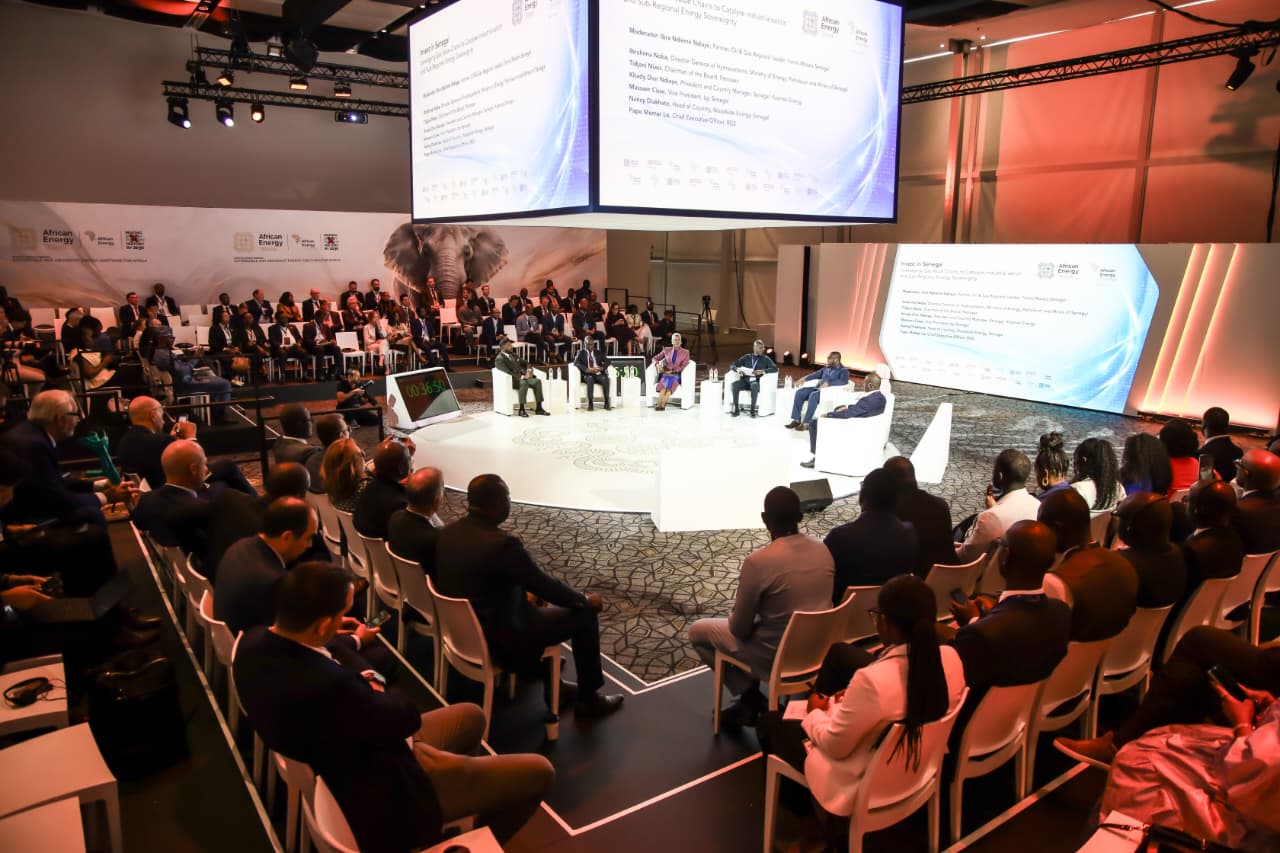
Senegal Opens 104 Blocks to Investors, Targets New Upstream Contracts

Published

on

Senegal’s Minister of Energy and Petroleum, El Hadji Abdourahmane Diouf, told AEW delegates that the country is seeking partners for its remaining acreage, the Yakaar-Teranga gas project and downstream developments

CAPE TOWN, South Africa, October 15, 2026/APO Group/ –Senegal has 104 oil and gas blocks available to investors and is seeking new upstream contracts to accelerate exploration and production, El Hadji Abdourahmane Diouf, Minister of Energy and Petroleum, said at African Energy Week 2026 in Cape Town. Of the 113 blocks in Senegal’s reorganized acreage, four are under contract and five have been allocated to Eni for studies, leaving substantial opportunities for international and regional operators.


“We hope to sign a number of contracts…” he said, adding that the country aims to “show investors that Senegal remains the country it has always been: open, hospitable and respectful of international procedures.”

Senegal reorganized its upstream acreage into 113 blocks in March 2026, comprising 65 onshore and 48 offshore blocks. The country also signed an agreement with Eni to assess the oil and gas potential of five offshore blocks.

Our strategy is to build the value chain from the well to the factory, with gas at the heart of our industrial ambition

Beyond new exploration acreage, Senegal is seeking partners to develop the Yakaar-Teranga gas project alongside national oil company Petrosen. Petrosen took full control of the project after Kosmos Energy withdrew in April 2026. Minister Diouf said Yakaar-Teranga will supply gas for power generation, industrial applications including fertilizer production, and exports. Advancing the project will require a coherent development structure, credible buyers and a clear investment program.

“Our strategy is to build the value chain from the well to the factory, with gas at the heart of our industrial ambition,” he said.

Downstream, Minister Diouf pointed to a planned second refinery that will process Sangomar crude, with investment estimated at $2 billion to $3 billion. The Société Africaine de Raffinage (SAR) and Turkey’s Yamata signed a Memorandum of Understanding for the four-million-ton-per-year refinery in New York on September 23, 2026. Minister Diouf said the project opens further opportunities in storage, logistics, distribution and petrochemicals.

Minister Diouf invited investors to examine Senegal’s data, work with its technical teams and bring proposals backed by the capacity to invest and execute. He also asked partners to involve Senegalese companies and skills from the outset, with support from the national local content monitoring committee.

“Capital must earn a return. Senegal must gain a stronger economy. The partnership we seek must serve both purposes,” he said.

According to Minister Diouf, Senegal hopes to expand the MSGBC alliance beyond its five host countries of Senegal, Mauritania, The Gambia, Guinea-Bissau and Guinea, but he did not specify which countries are being considered.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Energy

Africa shifts from carbon market potential to delivery as Carbon Markets Africa Summit (CMAS) 2026 opens in Kigali

Published

on

African governments, development finance institutions and global climate leaders call for high-integrity markets, investment-ready projects and greater value for African communities

KIGALI, Rwanda, October 15, 2026/APO Group/ –Africa must move beyond carbon market potential towards delivery, building high-integrity, investable markets that attract long-term capital while protecting national climate priorities and ensuring greater value reaches African countries and communities.


That was the central message from the opening keynote sessions of the Carbon Markets Africa Summit (CMAS) 2026 in Kigali, Rwanda, where policymakers, investors, project developers, development finance institutions and international climate organisations gathered to accelerate Africa’s participation in global carbon markets.

Representatives from 45 countries, including 21 African nations, are participating in the summit, where discussions have shifted decisively from market readiness to implementation, investment and transactions.

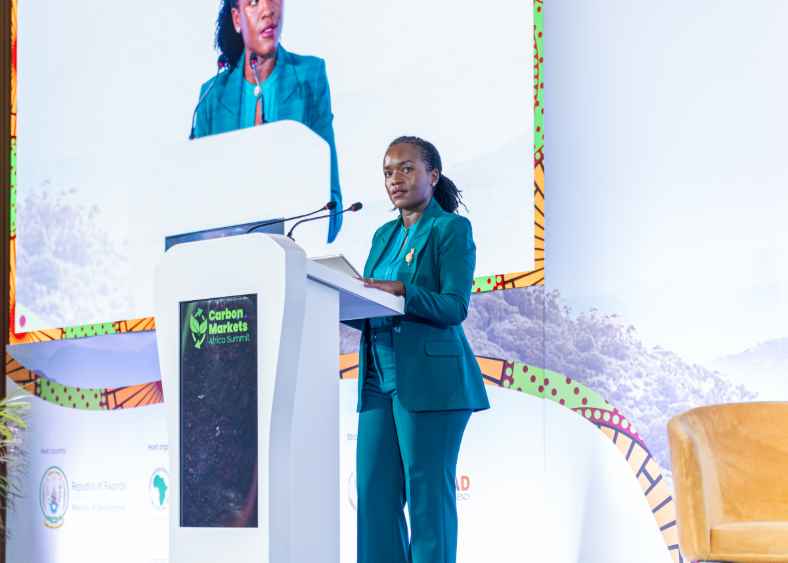
Officially opening the summit, Hon. Dr Bernadette Arakwiye, Rwanda’s Minister of Environment, said Africa’s carbon markets must be shaped by African priorities and deliver tangible benefits for the continent.

“The question before us is therefore no longer simply whether Africa is ready. It is whether we can deliver at scale, with integrity and with innovation.”

Minister Arakwiye said progress is already evident as African countries establish carbon market frameworks, grant authorisations, sign bilateral agreements and develop projects. However, she cautioned that carbon finance remains concentrated in a relatively narrow range of project types. She called for diversification into renewable energy, electric mobility, sustainable waste management, industrial decarbonisation, agriculture and landscape-scale nature-based solutions.

Minister Arakwiye identified three priorities for scaling Africa’s carbon markets: accessible methodologies suited to African contexts; project preparation and readiness finance; and long-term demand at fair value.

“Trust is the currency of this market,” she said. “To our buyers and investors, I say: look closely at these efforts. Reward them with long-term demand, fair prices and patient capital.”

From potential to execution

The call for delivery was echoed by Hon. Hamad Yusuf Masauni, Tanzania’s Minister of State in the Vice President’s Office responsible for Union Affairs and Environment, who said the continent now has an opportunity to reposition itself in global carbon markets.

“For too long, Africa has been spoken about as a continent of potential. At the Carbon Markets Africa Summit, we declare that the era of potential is giving way to the era of execution.”

Minister Masauni stressed the importance of moving high-quality, bankable projects through to issuance and offtake rather than focusing solely on the size of project pipelines.

“Credibility is built one verified tonne, one closed deal and one community that sees real benefit at a time.”

The importance of ensuring value reaches communities was also central to remarks from Maxwell Gomera, UNDP Resident Representative in South Africa and Director of the Africa Sustainable Finance Hub.

Gomera called for market infrastructure capable of carrying value “from the buyer all the way to the farmer”, backed by strong community rights, enforceable benefit-sharing, early-stage finance and partnerships focused on delivery.

Africa urged to compete on integrity, not price

For too long, Africa has been spoken about as a continent of potential

Speakers also stressed that Africa’s competitive advantage should be the quality and integrity of its carbon assets rather than simply offering the lowest-priced credits.

Perumal Arumugam, Manager of Markets and Non-Markets and Stakeholder Interaction at UN Climate Change (UNFCCC), said Africa should move beyond asking how it can participate in carbon markets and instead consider how carbon markets can advance African priorities.

“Africa should not compete simply by offering the cheapest tonnes. Africa should compete by offering credible and creditable tonnes, a sustainable tonne, and a tonne that the world can trust.”

He said success should ultimately be measured not only in credits issued, but in investment mobilised, mitigation unlocked, value reaching communities, stronger economies and African countries retaining control over their climate transitions.

Speaking on behalf of AUDA-NEPAD, Esterine Fotabong similarly called for African countries to scale carbon markets on their own terms, supported by predictable authorisations, functioning registries and credible monitoring, reporting and verification systems.

She also highlighted the need to build greater African capacity in validation and verification and expand access to carbon finance in sectors such as agriculture.

Global demand will reward quality

Representing the European Commission, Lukas Visek, Deputy Head of the Directorate-General for Climate Action Task Force for Carbon Pricing and Carbon Markets, signaled future European demand for international carbon credits while stressing that quality requirements would be stringent.

“Additionality and permanence are not negotiable,” he said. “Quality, however, will be rewarded.”

The message to developers was clear: projects being developed for future international demand will need robust data, genuine additionality, strong community participation and demonstrable alignment with national and global climate goals.

Turning carbon projects into investable assets

The summit’s opening programme then moved directly from policy to capital and deal flow, with leaders from the African Development Bank (AfDB), Development Bank of Southern Africa (DBSA) and Kigali International Financial Centre (KIFC) examining the practical barriers preventing more investment from reaching African projects.

Policy certainty, early-stage project preparation, bankable pipelines, robust governance and appropriate financial risk-sharing were identified as critical to accelerating capital flows.

Dr Anthony Nyong, Director of Climate Change and Green Growth at the African Development Bank, emphasised that carbon markets should ultimately be viewed through the lens of African development.

“We don’t have carbon projects. We have development projects.”

Greg Fyfe, Chief Investment Officer at DBSA, highlighted the catalytic role development finance institutions can play by supporting project preparation, providing patient capital and absorbing risks private investors are unable to take.

The opening sessions underscored a decisive shift in the African carbon market conversation: from readiness to delivery, from fragmented projects to investable pipelines, and from selling credits to building markets capable of delivering lasting economic, social and climate value.

As CMAS 2026 continues in Kigali, attention now turns to connecting credible African projects with buyers and capital, unlocking transactions and ensuring Africa plays a leading role in shaping the next generation of global carbon markets.

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Business

Ivory Coast Details Investment Opportunities, Seeks Partners for $10B Energy Expansion

Published

on

Ivory Coast is targeting $10 billion in energy investment by 2030 across upstream, refining and infrastructure projects

CAPE TOWN, South Africa, October 15, 2026/APO Group/ –Ivory Coast is seeking more than $10 billion in energy investment by 2030, with the country’s state-owned Petroci Holding identifying new upstream developments, exploration acreage and gas infrastructure as priorities for incoming partners. The investment drive covers refining, petroleum storage and distribution, positioning the country to expand production and supply regional markets.


Karim Coulibaly, Deputy Managing Director of Petroci, outlined the opportunities during the Invest in Ivory Coast: Unlocking the Next Wave of Upstream and Investment panel at African Energy Week 2026 on October 14. He said the country was seeking partners able to contribute financing and technical expertise across the energy value chain.

“Our country offers proven resources, growing demand, access to regional markets and a national partner committed to delivery. We welcome partners that bring capital and expertise and will connect them to industries our region needs,” Coulibaly said.

Upstream opportunities include the Calao and Calao South developments, farm-in opportunities in blocks CI-523 and CI-525, and an operatorship opportunity in block CI-26. Petroci is also seeking investment in pipeline infrastructure, LNG facilities, gas processing, power generation, LPG storage and distribution, gas-to-industry partnerships, and integrated logistics.

The Baleine field remains central to the country’s production growth. Operated by Eni alongside Petroci and Vitol, the project’s third phase received final investment approval in May 2026. The planned $4 billion development targets peak production of 150,000 barrels of oil per day and 200 million cubic feet of gas daily.

We aim to strengthen supply security and position Ivory Coast as a regional petroleum logistics hub

Jean Michel, Managing Partner and CEO of KeysFinance Partners, said the investment proposition extends beyond resource development to the infrastructure and services needed to bring projects into operation.

“Our country is a grounded market where international expertise and local capabilities create competitive advantages. We have a number of opportunities across the entire value chain, including exploration, development, construction, operations, maintenance and logistics,” Michel said.

Petroleum storage and distribution projects are intended to strengthen domestic supply and expand cross-border trade. Ivory Coast’s state-owned Gestoci – responsible for managing national petroleum reserves and fuel storage infrastructure – is advancing 40,000-m3 depot projects in Odienné and San Pedro, alongside rehabilitation of the Bouaké depot, supporting a wider strategy to decentralize storage capacity and improve access to inland and neighboring markets.

“These projects will increase supply to our neighbors while delivering shorter supply routes and lower logistics costs across the region,” said André Noël Koné, Commercial Coordinator at Gestoci. “We aim to strengthen supply security and position Ivory Coast as a regional petroleum logistics hub.”

Refining is another major investment opportunity. A proposed second refinery in San Pedro, with a planned capacity of 170,000 barrels per day and estimated investment of $5 billion to $7 billion, would significantly expand national processing capacity. Existing refiner Société Ivoirienne de Raffinage (SIR) is also prioritizing capacity, fuel quality and environmental performance.

“The three priorities that are poised to shape SIR’s next growth cycle include quality and standards, capacity and demand, and transition and climate,” said Myriam Kouame, Director of Commercial and Economic Affairs at SIR. “We strive to deliver cleaner fuels while supporting growth and increasing local value.”

Olivia Eti, Policy Officer within the Office of the Ministry of Mines, Petroleum and Energy, linked the investment drive to the government’s wider economic strategy. “Our government has an ambition to make mining resources and energy a firm pillar of the country’s economy,” she said.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Trending

Exit mobile version