Business
Global advertising spend to top $1trn for first time this year
Published
2 years agoon
Projected 10.5% rise in global spend this year represents a 2.3 percentage point (pp) upgrade to WARC forecast, reflecting the uptake of AI-enabled media tools
North America to grow 8.6% this year to $348bn, APAC market worth $272bn but growth cools to just 2.0%, Europe forecast to rise 5.0% to $165bn, Latin America +6.2% to $32.1bn, Middle East largely unaffected by looming threat of regional conflict +4.2% to $12.6bn
US political spend set to reach $15.8bn this year; $3.6bn spent across social platforms with growth rapidly increasing since change of Democratic candidate
WARC Global Ad Spend Outlook 2024/25 – A Decade of Consolidation
22 August 2024 – A new study from WARC, the experts in marketing effectiveness, has found that global advertising spend is on course to grow 10.5% this year to a total of $1.07trn – the best performance in six years if the post-Covid recovery of 2021 (+27.9% year-on-year) is disregarded.
Ad spend growth is also anticipated next year (+7.2%) and in 2026 (+7.0%), culminating in a global ad market worth $1.23trn. Global ad investment has more than doubled over the last decade, and has grown 2.8x faster than global economic output since 2014. Just three companies – Meta, Amazon and Alphabet – account for more than 70% of this incremental spend. This trifecta is expected to attract 43.6% of all advertising spend this year, rising to a share over 46% by 2026.
WARC’s latest global projections are based on data aggregated from 100 markets. New for this edition, WARC is now leveraging an advanced neural network machine learning model which projects advertising investment patterns based on over two million data points spanning macroeconomic data, media owner revenue, marketing expenses from the world’s largest advertisers, media consumption trends and media cost inflation. It is believed to be one of the most comprehensive advertising market models available to the industry today.
The new projections show that ‘pureplay’ (i.e. online only) internet companies are set to record a 14.0% rise in advertising revenue this year, reaching a total of $735.7bn. In total, almost nine in every ten (88.5%) incremental dollars spent on advertising this year will go to online-only businesses, with half (52.9%) being paid to Alphabet, Amazon and Meta. Taken together, pureplay platforms are set to account for over 70% of all advertising spend worldwide next year.
Retail media (+21.3%), social media (+14.2%) and search (+12.1%) are set to lead digital growth in 2024, with these three sectors alone accounting for over 85% of online spend and almost three in every five (58.7%) incremental dollars spent on advertising worldwide this year. All are benefiting from the increased adoption of AI-driven ad services and growing appreciation of first party data.
James McDonald, Director of Data, Intelligence and Forecasting, WARC, and author of the research says: “The global ad market has doubled in size over the last decade, with advertising investment growing almost three times faster than economic output since 2014. Three companies – Alphabet, Amazon and Meta – have been the largest beneficiaries from this period of expansion, attracting seven in ten incremental ad dollars over the last ten years.
“With retail media expected to lead ad spend growth over the coming years, and with new, diverse players emerging in ad selling – from Uber to Chase – we are once again seeing the value of first party data in targeting the right person with the right message at the right time. Such data, combined with new AI enhancements, will constitute the fabric of the advertising industry for the next decade and beyond.”
Key findings outlined in WARC’s Global Ad Spend Outlook 2024/25 are:
MEDIA TRENDS: Global ad spend is forecast to rise 10.5% this year to a total of $1.07trn, and then 7.2% in 2025 and 7.0% in 2026; social, retail media and CTV to lead growth
At $241.8bn in 2024, social media is the largest single advertising channel measured in WARC’s study, having overtaken search (excl. retail media) for the first time last year. It accounts for 22.6% of all global ad spend this year and is forecast to rise to a share of 23.6% by the end of 2026.
Within social, Meta is the largest individual player, commanding 62.6% of the market this year. Its share is being eroded however, most notably by Douyin and TikTok owner Bytedance, which now draws a fifth (20.1%) of all social spend, up from a share of just 9.3% five years ago. TikTok is on course to account for over half of its parent-company’s advertising revenue for the first time next year with estimated ad billings over $28bn, though uncertainty remains around the platform’s future in the US – its largest market by far with 170m monthly active users.
The main social platforms have reported a fillip from new, AI-enabled services during the first half of 2024, a trend that is set to underpin the advertising industry at large over the coming years. Over half of all AI-enabled spend – defined as involving some form of recommendation algorithm, natural language processing or search optimisation – today occurs in the social media sector.
Search advertising (excluding retail media) accounts for 21.8% of global advertising spend, at a forecast total of $223.8bn this year. Its share has consistently grown since WARC began monitoring the sector in 2013, though it is set to plateau in 2026 as more purchase journeys begin in retail media environments and social commerce begins to realise its potential outside of Asia. Another potential headwind may be the rise of AI-driven search, and uncertainty around what the ad experience will look like for consumers more familiar with text-based search experiences.
Google accounts for more than four-fifths (84.0%) of the global search market, with its paid search revenue set to top $200bn for the first time next year. Google’s share rises to over 90% if China is excluded, a position of dominance which this month led a US judge to rule the company in breach of antitrust laws.
Retail media is expected to account for 14.3% of global ad spend this year – a total of $152.6bn – which is double the share recorded in 2019 before the pandemic contributed to an exceptional growth spurt. Indeed, retail media is expected to be the fastest-growing channel over at least the next three years.
Amazon is the dominant global player, with anticipated ad revenue (excluding Twitch and Prime Video) of $55.9bn equivalent to more than a third (36.6%) of all retail media spend and over two-thirds excluding China this year. While competition is heating up, such billings eclipse the near $4bn Walmart is due to net in 2024 and the $1bn ad business Uber is building, while Amazon is also due to have surpassed Alibaba by ad revenue for the first time this year.
CTV is on course to be worth $35.3bn to advertisers this year, roughly a quarter of the size of the linear TV market. Growth is rapid; CTV spend is expected to rise 19.6% and is set to account for two-thirds of all growth in the video (linear + CTV) market this year, and all growth in 2025. By 2026, CTV is projected to account for almost a quarter (23.9%) of all video ad spend, at $46.3bn.
Netflix is the largest streaming provider globally, with 277.6m subscribers worldwide in Q2 2024. However, its global advertising business is unlikely to grow too far beyond $1bn this year. YouTube’s ad income – which we do not yet classify as CTV – is expected to rise 14.3% to $36.0bn this year. Further, YouTube’s ad revenue is set to top $45bn globally by 2026, almost as much as the entirety of the global CTV industry at that time.
Legacy media, encompassing print publishing, broadcast radio, linear TV, cinema and out of home (OOH), now collectively account for a quarter (25.3%) of total advertising spend, having recorded a dip in share in each of the last 15 years.
Advertising spend on legacy media is expected to total $270.5bn this year, representing a 1.5% rise from 2023. Much of this growth can be attributed to US political spending; with this removed legacy media are, collectively, set to record a 0.5% decline in advertiser investment in 2024.
Linear TV spend is expected to grow by 1.9% this year, its best performance since 2014 if the post-Covid recovery year of 2021 (+12.7%) were excluded. The market is flat (+0.1%), however, excluding US political spend. Out of home (+7.2%) and cinema (+6.1%) will see some growth this year, though radio (-2.3%) is expected to record its third consecutive year of decline. Newsbrands (-3.3%) and magazine brands (-3.4%) are also due to see losses across print and online editions.
PRODUCT SECTOR TRENDS: Technology & Electronics (+13.2%), Alcoholic Drinks (+12.2%) and Clothing & Accessories (+11.1%) the fastest-growing consumer sectors next year. US political spend is expected to reach $15.8bn this year; over a fifth spent on social.
Advertising spend during the 2024 US presidential election is on course to top $15bn for the first time, with an expected total of $15.8bn up by over 40% on the previous cycle in 2020. Spend had been lagging the 2020 total earlier this year, but the surprise decision to change the Democratic candidate has led to an influx in spending in order to reposition the new ticket of Kamala Harris and Tim Walz. This shift is perhaps most pronounced online: political spending on social media is tracking 27.4% higher in Q3 2024 versus Q2 2024, with social spending by both main parties on course to reach $3.6bn this year.
Retail – the largest of the 19 categories monitored by WARC – is anticipated to record a 2.5% dip in global spend this year. Our definition of this sector is broad however, ranging from quick service retail (QSR) to grocery to department stores to online retailers, such as Temu. The latter is expected to continue investing heavily in advertising, particularly in Europe this year, but it is an exception – the longer tail of retailers are facing business pressures from soft consumer demand.
Technology & Electronics – the third-largest product sector monitored by WARC – is expected to post the fastest growth this year, with incremental spend of $17.0bn worldwide. The sector had recorded declines in advertising spend in both 2022 and 2023, as central banks raised interest rates sharply in an attempt to stymie inflation, exposing over-leveraged tech startups in particular.
Technology & Electronics (+13.2%), Alcoholic Drinks (+12.2%) and Clothing & Accessories (+11.1%) are forecast to lead ad spend growth among consumer-facing products in 2025, though Business & Industrial, the second-largest category, is expected to be the fastest-growing category overall next year (+18.2%), as budgets unlock during a period of comparatively favourable economic and trading conditions.
The Nicotine category is also growing rapidly, albeit from a low base; it is the smallest of the 19 product categories monitored by WARC at $13.0bn in 2024. Spend is set to grow 56% over the three years to 2026 – reaching a total of $17.2bn – driven almost entirely by vape products which skew heavily towards online advertising.
REGIONAL TRENDS: North America to grow 8.6% this year to $348bn, APAC growth cools to just 2.0% owing to stronger dollar, Europe is forecast to rise 5.0% to $164.9bn, while Middle East ad markets are largely unaffected by looming threat of regional conflict
North America is on track to be the fastest-growing region this year – inflated by the US presidential elections – with ad spend rising 8.6% to a total of $347.5bn. US ad spend is expected to grow 8.9% this year (+4.0% excluding political spend, more than double the 1.4% growth rate recorded in 2023) to a total of $330.8bn. A further rise, of 3.6%, is forecast next year, by when the US ad market should be worth over $342bn. The Canadian ad market is due to grow 7.5% to CAD23.3bn ($16.8bn) this year.
Latin America (+6.2% to $32.1bn in 2024) then follows, with its largest market, Brazil, forecast to record local currency growth of 9.6% this year to a total of BRL85.7bn ($14.8bn) – an acceleration from the 7.5% rise recorded last year. Our forecasts suggest that online advertising will account for over half (50.4%) of the Brazilian ad market for the first time this year.
APAC’s (+2.0% to $272.0bn this year) largest market – China – is projected to see ad market growth of 6.4% this year to RMB1.32trn ($181.2bn), an easing from the 9.3% rise recorded in 2023 as consumer demand remains soft and economic expansion lags stubbornly behind the target. Pureplay internet will account for over 86% of the Chinese ad market in 2024, though social media (+10.5%) and retail media (+8.2%) will expand at a slower rate this year than last.
When measured in local currency – so as to exclude the distorting effect of exchange rate fluctuations – we see that India will be the fastest growing key market this year, with advertiser spend rising 11.9% to INR1.08trn ($12.8bn).
Japan – the fourth-largest ad market in the world – is forecast to grow by 5.2% this year to JPY5.83trn ($36.9bn), though this equates to a 6.3% decline when measured in US dollars due to the Yen falling to a decade-long low. Australia’s ad market is expanding by 2.0%, a modest but welcome change of fortunes following flat (+0.3%) growth in 2023, while Indonesia is expected to achieve 7.8% growth this year.
Advertising spend across Europe is forecast to rise 5.0% this year to $164.9bn. The UK, the largest European market by spend, is expected to post an 8.0% rise to £38.5bn ($47.5bn) in 2024 per market data from the AA/WARC Expenditure Report. On the European mainland, France (+8.0%), Italy (+5.4%) and Germany (+4.0%) are all expected to see healthy gains this year, with the former in particular benefiting from increased advertising activity around the Paris Olympics and Paralympics in the third quarter.
Brand spend in the Middle East and Africa is currently on course to rise by 4.2% to $12.6bn this year, though fortunes are mixed. African spend is expected to be flat (+0.2%), following a 15.7% decline in 2023 and 1.4% dip in 2022. South Africa, the region’s largest market, is expected to see its ad market grow 6.0% this year but this translates to a 1.1% increase when measured in dollars owing to a weak Rand by historical measures. Ad spend in the Middle East is set to rise 8.1% this year but that is subject to change should conflict spread beyond Gaza to the wider region.
A complimentary article by WARC’s James McDonald, author of the report, is available to read here. WARC subscribers can read the article and access additional data here.
You may like
-
Hong Kong sets out strategies to enhance the appeal and add value to the city’s tourism industry
-
Former DAMAC Senior Vice President Paulo J. Cruz Appointed Founding CEO of African Collaboration Group (ACG) to Spearhead Sports and Entertainment District Development Across Africa
-
Africa Makes its Case for a Bigger Role on the Global Stage
-
South Africa’s water challenges are reshaping how businesses plan for resilience
-
Afreximbank, Ghana Infrastructure Investment Fund (GIIF) and Ghana’s 24-Hour Economy Authority launch project preparation partnership to accelerate 24H+ projects
-
Afreximbank and Development Bank of Southern Africa establish a Joint Project Preparation Facility to advance bankable projects in Southern Africa
Business
Hong Kong sets out strategies to enhance the appeal and add value to the city’s tourism industry
Published
12 hours agoon
September 21, 2026
HONG KONG SAR – Media OutReach Newswire – 21 September 2026 – Enhancing the city’s appeal as a destination for tourism and major sports and cultural events was a strong focus of the First Five-Year Plan for Economic and Social Development of the Hong Kong Special Administrative Region (HKSAR) (2026-2030) and the 2026 Policy Address, announced by Hong Kong’s Chief Executive John Lee last week (September 16).
Mr Lee unveiled measures to support the integrated development of culture, sports and tourism which will help develop Hong Kong as an East-meets-West Centre for International Cultural Exchange. These included enriching the supply of high-quality tourism products, while bolstering infrastructure and ancillary facilities as well as deepening engagement with markets in the Chinese Mainland and around the world.
“Hong Kong is blessed with a unique cultural vision, shaped by both Chinese and foreign influences,” Mr Lee said. “We will continue to engage and collaborate with Mainland and overseas culture, arts and creative sectors to consolidate Hong Kong’s role as a hub for the exchange, collaboration and promotion of culture, arts and creativity. We will also host international cultural and arts exhibitions and performances to attract visitors to Hong Kong.”
To support Hong Kong’s film industry and promote “Film + Tourism”, the Support Unit for Non‑local Film Productions will be set up to provide one‑stop services for Mainland and overseas film crews filming in Hong Kong, attracting the production of more quality films to promote Hong Kong.
Mr Lee noted that the Kai Tak Sports Park has substantially expanded Hong Kong’s capacity to host international mega events, with more than 170 sessions of international and local sports and cultural entertainment mega events having been held there so far, attracting over 2.6 million spectators.
Meanwhile, the HKSAR Government will explore the redevelopment of Victoria Park Centre Court and other ancillary facilities into an iconic all‑weather, multi‑purpose venue for holding larger‑scale and higher‑level sports events, as well as performance activities.
Hong Kong’s Secretary for Culture, Sports and Tourism, Rosanna Law, highlighted the growing trend of multi-destination tourism. Ms Law said that Hong Kong welcomed around 36.67 million visitor arrivals in the first eight months of 2026, representing a year-on-year increase of about 11 per cent.
“The proportion of overseas visitors travelling onwards to the Chinese Mainland via Hong Kong has continued to rise, exceeding 20% in the first half of 2026,” Ms Law said.
The HKSAR Government will continue to capitalise on measures introduced by the Central Government to facilitate visits by foreign travellers to the Chinese Mainland, deepen collaboration with Mainland provinces and municipalities, and explore with the country additional immigration facilitation arrangements for international visitors. The Hong Kong Tourism Board (HKTB) will promote multi destination travel itineraries to overseas visitors, partner with airlines to roll out relevant tourism products and promotional offers, and intensify publicity overseas.
It will take forward “+ Tourism” joint initiatives, integrating various events with tourism to raise their appeal, aiming to extend visitor stays in Hong Kong and generate value‑adding momentum. Such joint initiatives would integrate tourism with mega events, ecology, heritage, finance and industrial brands.
On developing the yacht economy, Mr Lee said that a variety of new yacht berth projects are now moving ahead, including the tender for the composite development project in Aberdeen comprising a marina, recreational facilities and residential development scheduled for the first half of 2027, and the yacht bay project under the Airport City “SKYTOPIA”.
“In addition, starting from May, Hong Kong and Macao yachts may navigate in nine Guangdong-Hong Kong-Macao Greater Bay Area cities, with the requirement for guarantee exempted and under temporary ship nationality registration,” Mr Lee said. “The first northbound travel of yachts from Hong Kong set sail in June. The Marine Department will soon sign a memorandum of understanding with the Guangdong Maritime Safety Administration for the implementation of southbound travel for yachts from Guangdong, adding impetus to cross‑boundary leisure consumption.”
To further enhance the city’s appeal as a Muslim‑friendly destination, the HKTB will extend the Hong Kong Restaurants Halal Certification Funding Scheme to the end of 2027, encouraging the industry to provide more Muslim‑friendly food options.
Business
Former DAMAC Senior Vice President Paulo J. Cruz Appointed Founding CEO of African Collaboration Group (ACG) to Spearhead Sports and Entertainment District Development Across Africa
Published
12 hours agoon
September 21, 2026
Paulo J. Cruz will lead the development and expansion of a pan-African platform for the origination and structuring of large-scale sports and entertainment district ecosystems
Mr Cruz joins ACG from DAMAC Group, one of the largest privately held real estate developers in the Middle East, where he served as Senior Vice President from 2022 to 2026. In 2025, the Group reported close to USD 10 billion in property sales. His tenure at DAMAC further deepened an already distinguished career spanning infrastructure origination, urbanisation strategy, and large-scale real estate development across Africa, the Middle East, and Europe.
Over the course of his 28-year career, Mr Cruz has originated or structured projects ranging from USD 50 million to in excess of USD 5 billion, stewarding initiatives from early-stage concept through feasibility analysis, financial structuring, and investor alignment to bankable delivery stages. His professional footprint encompasses senior roles at BP, one of the world’s foremost energy companies; BlackIvy Group, a US-backed infrastructure investment platform; Movares, a leading European engineering consultancy; and Cushman & Wakefield, a globally recognised real estate advisory firm.
Prior to DAMAC, Mr Cruz served as Group Chief Executive Officer of LandAfrique, a pan-African development platform focused on industrial parks, infrastructure, housing and power projects across Sub-Saharan Africa, further solidifying his reputation as one of the continent’s most experienced development executives.
Infrastructure is the prerequisite for the industrialisation of sport in Africa
As Founding CEO of ACG, Mr Cruz will lead the development and expansion of a pan-African origination platform, working in close partnership with sovereign governments, development finance institutions (DFIs), private investors, sport and entertainment principals, and leading academic institutions to structure district-level projects that are both investable and deliverable at scale.
ACG operates as a specialised origination and collaboration platform engineered to transform concepts into credible, bankable sport and entertainment district ecosystems — architectures capable of attracting institutional capital and generating long-term, multi-dimensional economic impact at a national and continental scale.
ACG’s flagship initiative, Victory District™, provides a proprietary district development framework designed to originate integrated, mixed-use sport and entertainment destinations that transcend conventional single-venue models. The framework prioritises asset utilisation optimisation, long-term sustainability, expanded revenue diversification beyond matchday economics, structured employment and youth opportunity creation, talent development pathways, and institutional-grade operations and maintenance standards.
Mr Cruz’s appointment follows the establishment of ACG’s Advisory Board, comprising internationally recognised leaders from global sport governance, finance, infrastructure and development institutions — including Fatma Samoura, Former Secretary General of FIFA; Kenny Jean-Marie, Former Chief Member Associations Officer of FIFA; Herbert Mensah, President of Rugby Africa and Executive Board Member of World Rugby; and Jan Alessie, Co-Founder and Managing Director of the World Football Summit — as well as a Research & Impact Advisory Panel of leading scholars focused on the economics, governance and societal impact of sport. The full list of Advisory Board and Research & Impact Advisory Panel members can be consulted here: https://apo-opa.co/4xMb5ry.
“Paulo brings an exceptional combination of origination expertise, institutional credibility, and continental experience that is virtually unparalleled in this space. His demonstrated ability to transform ambitious development concepts into financially structured, bankable projects positions him as the ideal leader to guide ACG as we build a platform capable of catalysing transformative investment and accelerating the realisation of financially sustainable sport and entertainment districts across Africa,” said Nicolas Pompigne-Mognard (www.Pompigne-Mognard.com), Founder and Executive Chairman of ACG.
A prominent thought leader and keynote speaker at leading international platforms — including the Africa Property Investment Summit (API Summit), the Africa Real Estate Conference & Expo (ARCE), the African Union for Housing Finance Annual Conference, and the West Africa Property Investment Summit — Mr Cruz was honoured as “Person of the Month” by Sustainable Investments and Alliances for Africa (SIA).
“Infrastructure is the prerequisite for the industrialisation of sport in Africa — without it, the entire value chain remains theoretical. Athletes need places to train, compete and develop. Sport governing bodies need venues that meet international standards. Broadcasters, sponsors and event organisers need facilities capable of generating commercial value. Every revenue stream in the sport economy ultimately depends on infrastructure existing and its respective operation. But how that infrastructure is originated determines whether it becomes an economic engine or a fiscal burden. Across Africa, too many sport facilities have been built in isolation — a stadium delivered for a single event, then left to deteriorate at a fraction of its capacity, draining public finances rather than generating returns. ACG exists to change that equation,” said Paulo J. Cruz, Founding Chief Executive Officer of African Collaborations Group.
Distributed by APO Group on behalf of African Collaborations Group (ACG).
Business
Africa Makes its Case for a Bigger Role on the Global Stage
Published
13 hours agoon
September 21, 2026
GABI’s Unstoppable Africa 2026 brings global leaders together on Africa’s push to capture more value from its resources, accelerate investment and strengthen its influence in global trade and decision-making
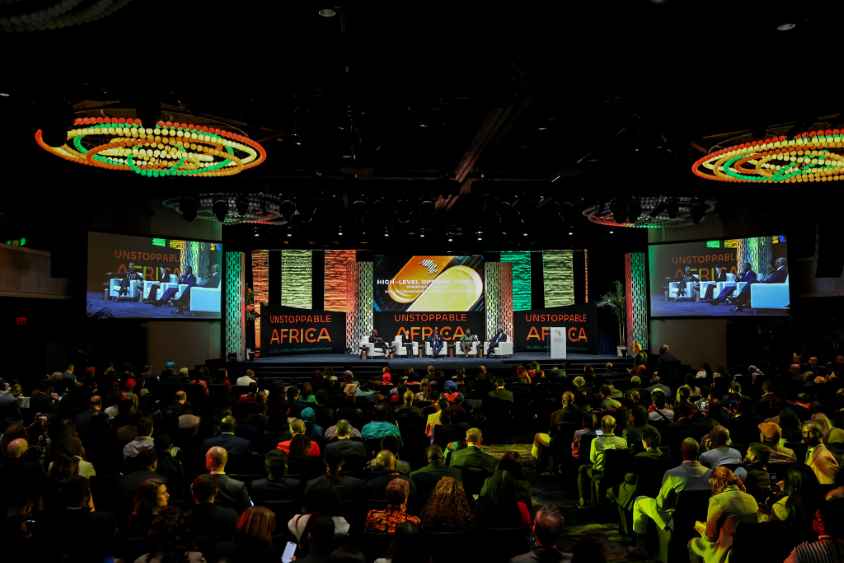
The fifth edition of the Global Africa Business Initiative’s (GABI) flagship convening drew senior leaders from across business, government, and global institutions to the Marriott Marquis in Times Square, including UN Secretary-General H.E. António Guterres; H.E. Mahmoud Ali Youssouf, Chairperson of the African Union Commission; and Massad Boulos, Senior Advisor to the President of the United States on Arab and African Affairs.
The UN Secretary-General called for action to give Africa a greater role on the global stage, including a permanent presence on the United Nations Security Council: “Africa needs a permanent presence on the United Nations Security Council, where it can contribute to dialogue and action for the whole globe.” He stressed that Africa’s growing influence in global markets must translate into a stronger voice in international affairs. Guterres also urged reforms to better reflect the needs of developing countries, particularly in Africa, and for the continent’s natural resources, including critical minerals, to generate more local value and decent jobs rather than simply being exported.
With critical minerals, trade, energy, and investment dominating the first day, Unstoppable Africa reflected a wider shift in Africa’s economic story: from supplying the global economy to building more of the businesses, industries, and value chains that can capture the opportunity.
H.E. Mahmoud Ali Youssouf, Chairperson of the African Union Commission, said Africa’s 1.5 billion people and growing market create a significant opportunity, but the continent must accelerate the development of African value chains and remove barriers to trade to drive industrial transformation. He identified affordable energy, better infrastructure, access to finance, skills, technology, and clear standards as critical requirements for Africa to turn its market potential into faster economic growth.
Africa needs a permanent presence on the United Nations Security Council, where it can contribute to dialogue and action for the whole globe
The private sector took center stage, as African and global business leaders articulated what it will take to turn Africa’s resources, markets, and talent into productive economic capacity. The Leaders Panel brought together Samaila Zubairu, President and CEO of the Africa Finance Corporation; Aliko Dangote, Founder and Chairman of the Dangote Group; Mandy DeFilippo, CEO of Americas, Europe, Middle East and Africa at Standard Chartered; Nonkululeko Nyembezi, Chairperson of Standard Bank Group; Nolitha Fakude, Chairperson of Anglo American South Africa; and Tidjane Thiam, General Partner at Allied Critical Minerals Fund.
Leaders stressed the need to move beyond exporting raw materials, including critical minerals and crude oil, by developing local processing, manufacturing, and value chains that create jobs and retain more economic value on the continent.
One of the highlights announced yesterday was that the US$300 million Nigeria Distributed Renewable Energy (DRE) Fund has reached its first close, securing its initial capital commitments and moving into operation. Co-managed by the Nigeria Sovereign Investment Authority (NSIA) and Africa50, the fund will provide equity financing to local clean-energy developers, supporting decentralized solutions including solar mini-grids, solar home systems, commercial and industrial power solutions, and energy storage. Aligned with Mission 300, which aims to connect 300 million Africans to electricity by 2030, the fund is designed to mobilize private investment and expand reliable energy access for Nigerian homes and businesses.
Energy was another major focus. Anna Bjerde, Managing Director of Operations at the World Bank Group, and Damilola Ogunbiyi, CEO and Special Representative of the UN Secretary-General for Sustainable Energy for All, joined discussions on how innovative finance could unlock investment in Africa’s power infrastructure and accelerate access to reliable energy.
Healthcare also featured within the wider economic conversation. Roche reaffirmed its commitment to advancing breast cancer care through its Africa Breast Cancer Ambition (ABCA), which aims to help 80% of women diagnosed with breast cancer in Africa survive for at least five years by 2030.
Unstoppable Africa 2026 continues today, September 21st, with further sessions focused on digital transformation, investment, creative industries, sport, and Africa’s role in the global economy.
Everyone is invited to watch the event live on Unstoppable Africa YouTube channel at https://apo-opa.co/4xoGXlz
Distributed by APO Group on behalf of Global Africa Business Initiative.
Trending
-
Business5 days agoHong Kong’s First Five-Year Plan sets out long-term vision for development
-
Business5 days agoAfreximbank extends US$10-million facility to Azania Bank to support Small and Medium-sized Enterprises (SMEs) in Tanzania
-
Business5 days agoInternational Trade Centre (ITC) and DHL renew partnership to help small businesses trade
-
Business5 days agoAfreximbank and ZEP-RE deepen partnership to build trade, insurance and risk management expertise across Africa
-
Business5 days agoEmirates Skywards doubles the Miles on Emirates and flydubai flights
-
Business5 days agoHong Kong’s 2026 Policy Address: A Strategic Vision for a Bright New Era
-
Business4 days agoAfreximbank and Development Bank of Southern Africa establish a Joint Project Preparation Facility to advance bankable projects in Southern Africa
-
Business4 days agoHong Kong sets out strategic vision for developing the Northern Metropolis and creating a global talent hub