Connect with us
Anglostratits

Business

Binance sets the global standard for compliance in digital assets and goes beyond it
Published

on

Binance has built its compliance programme to a standard that goes beyond what is expected of traditional financial institutions in many markets

OUAGADOUGOU, Burkina Faso, September 14, 2026/APO Group/ –As digital assets become part of everyday finance across  West Africa, Binance (www.Binance.com) is setting out its commitment to compliance, security and user protection.


Who is Binance?

Binance is the world’s largest platform for buying, selling and holding digital assets such as Bitcoin,  Ethereum and stablecoins. Founded in 2017, Binance serves more than 320 million users across 100+  regions, including markets across Africa.

Why compliance matters

Digital assets move fast and across borders. That means the platforms holding them need strong  rules not just to meet legal requirements, but to keep users safe and earn their trust .

Binance has built its compliance programme to a standard that goes beyond what is expected of  traditional financial institutions in many markets. Every user must verify their identity before they  can trade or withdraw. Every transaction is monitored for signs of fraud or money laundering.  Suspicious activity is flagged, investigated and reported to the relevant authorities.

In Burkina Faso, we want people to understand who we are, how we protect their assets and why our standards are built to go beyond what is expected

A globally aligned standard

Binance operates under a regulatory framework licensed by the Abu Dhabi Global Market (ADGM)  Financial Services Regulatory Authority, one of the most respected financial regulators in the world.  This framework covers exchange operations, custody of user assets and clearing and settlement, with separate regulated entities for each function.

That means Binance’s compliance standards – covering governance, risk management, anti-money-laundering controls, customer protection and asset custody – are held to the same level of scrutiny as a fully regulated financial institution, not just a technology company.

Going beyond the traditional financial sector

Many traditional financial institutions are not required to publicly prove they hold the assets they claim to hold. Binance does. Through its Proof of Reserves system, Binance publishes regular, independently verifiable reports showing that user assets are backed one-to-one or better. Users can check for themselves that their balances are included, using cryptographic tools that protect their privacy.

Binance also maintains the Secure Asset Fund for Users (SAFU) , an emergency reserve held in a public wallet and designed to protect users in the event of a security incident. Few platforms in the digital asset industry,  and few institutions in traditional finance,  offer this level of visible, user-facing protection.

What this means for Burkina Faso

As digital finance grows in Burkina Faso and across the region, users deserve to know that the platform they use is held to the highest global standards. Binance is already operating to those standards, not because regulation requires it today but because keeping users safe is the foundation of trust.

“We believe compliance is not a box to tick. It is a continuous commitment to doing the right thing for users, regulators and the communities we serve,” said Samukele Mkhize, Compliance Lead Binance Africa. “In Burkina Faso, we want people to understand who we are, how we protect their assets and why our standards are built to go beyond what is expected.”

Distributed by APO Group on behalf of Binance.


Business

World’s largest Electric vehicle (EV) manufacturer Yadea partners with leading energy and mobility player Spiro to accelerate electric mobility across Africa
Published

on

Electric vehicle

The partnership comes as Spiro accelerates its next phase of growth and expansion across Africa following its latest $270 million funding round, which included investment from NewTrails Capital, a Chinese fund

DUBAI, United Arab Emirates, September 14, 2026/APO Group/ —

  • This strategic partnership will combine Yadea’s global leadership in electric vehicle manufacturing, technology and product development with Spiro’s electric mobility ecosystem, battery-swapping infrastructure and market presence.
  •  The companies commit to scaling a commercially sustainable and technologically integrated electric mobility ecosystem that will serve millions of riders, businesses and fleet operators across Africa, through three main areas of collaboration.

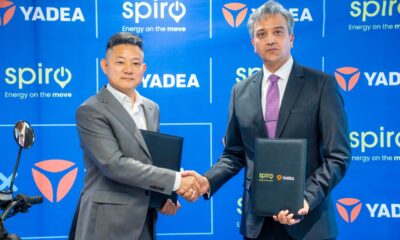
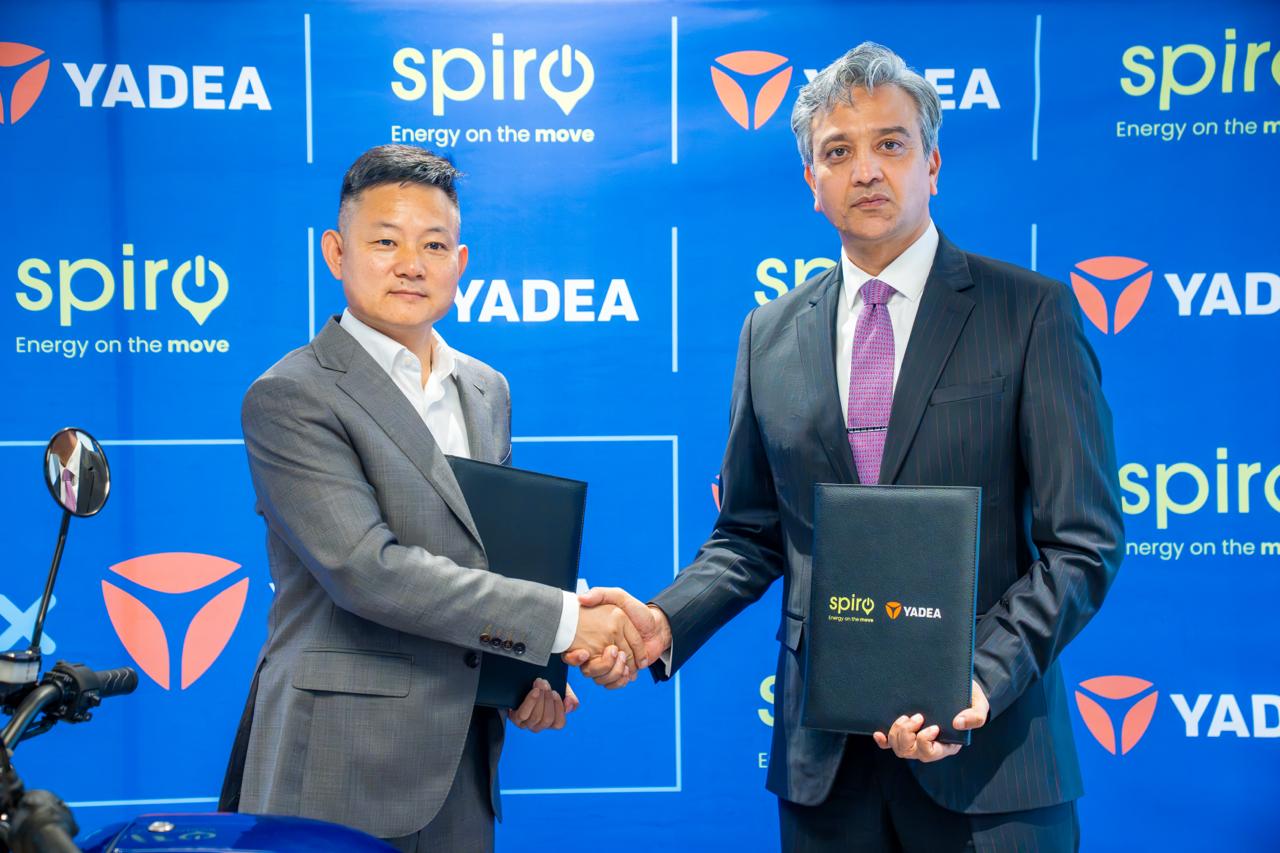
Spiro (www.Spironet.com), Africa’s leading electric mobility company, has signed a partnership with Yadea, the world’s leading manufacturer of electric two-wheelers, to scale accessible and sustainable electric transport across Africa.


Our strategic partnership with Yadea is a major endorsement of our execution to date

The strategic partnership combines Yadea’s global manufacturing and R&D capabilities with Spiro’s operational network and battery-swapping ecosystem across seven countries. Together, the companies aim to build a scalable, commercially sustainable EV framework serving millions of commercial fleet operators, delivery services, logistics providers, and daily commuters in Africa’s fastest-growing mobility markets.

Under the agreement, Yadea will supply electric two-wheelers and related EV products tailored to Spiro’s expanding regional markets, while Spiro will integrate the vehicles into its proprietary battery-swapping and energy infrastructure. The companies will also co-develop customized two-wheeler platforms engineered specifically for local road conditions and commercial utility across Africa.

This partnership deepens the China-Africa connection, pairing Yadea’s manufacturing scale with Spiro’s battery-swapping network and unique knowledge of African market dynamics to accelerate the continent’s transition to affordable electric transport.

“When we launched Spiro, our mission was to lay the energy and mobility foundation for Africa’s green transition. Our strategic partnership with Yadea is a major endorsement of our execution to date and opens fantastic opportunities to jointly pioneer the next era of electric mobility in emerging markets”, stated Gagan Gupta, Founder of Spiro and Chairman of Equitane.

Anant Badjatya, CEO of Spiro, said: “Africa’s shift to electric mobility is accelerating and this partnership helps us meet that demand at scale. By bringing together Yadea’s manufacturing strength with Spiro’s electric mobility ecosystem and operating experience across Africa, we are compressing the timeline to clean transport — helping thousands more riders switch to affordable EVs faster and multiplying our climate impact across the continent.”

Wang Jiazhong, Senior Vice President of Yadea Technology Group, stated: “Africa represents a massive frontier for zero-emission transport. Our mission to reduce carbon emissions has reached a powerful milestone through this partnership with Spiro. Together, we are combining global innovation with local infrastructure to deliver scalable and sustainable mobility solutions that serve millions of riders and transform Africa’s urban transit.”

Founded in China, Yadea is the world’s leading manufacturer of electric two-wheelers, with more than 100 million vehicles sold worldwide in over 100 countries and 10 exclusive production facilities globally. A strong innovator with more than 2,000 patents registered in electric vehicle technology, Yadea covers a comprehensive range of urban micro-mobility solutions.

The partnership comes as Spiro accelerates its next phase of growth and expansion across Africa following its latest $270 million funding round, which included investment from NewTrails Capital, a Chinese fund. The company is building an integrated electric mobility ecosystem combining electric motorcycles with an extensive battery-swapping network, enabling riders to exchange depleted batteries for fully charged ones in minutes.

Distributed by APO Group on behalf of Spiro.


Continue Reading

Business

Pan-African Payment and Settlement System (PAPSS) targets accelerated adoption and transaction growth as network expands across Africa
Published

on

During 2026 alone, around 10 additional countries have joined the PAPSS ecosystem, with further expansion expected before the end of the year

LAGOS, Nigeria, Egypt, September 11, 2026/APO Group/ –The Pan-African Payment and Settlement System (PAPSS) is preparing to accelerate adoption and transaction growth across Africa as it enters the next phase of its strategy, following significant expansion of its network and strong growth in payment volumes and values.

Speaking at a media briefing in Lagos, Mr Mike Ogbalu III, Chief Executive Officer of PAPSS, said the platform now operates in more than 30 African countries across all five regions of the continent. It connects 24 national and regional central banks, more than 200 commercial banks and payments service providers, and 16 switches. Through strategic partnerships, PAPSS also provides a termination footprint covering more than 300 financial institutions.


During 2026 alone, around 10 additional countries have joined the PAPSS ecosystem, with further expansion expected before the end of the year.

Mr Ogbalu said: “The first phase of PAPSS has been about building, connecting and establishing trust. We have built the infrastructure, expanded our network across Africa and demonstrated that PAPSS can deliver tangible benefits. As we move into our next phase from 2027, our focus will increasingly shift towards activating that network, deepening adoption and taking transaction growth to scale.”

Usage of PAPSS has accelerated significantly. Between comparable periods in 2025 and 2026, transaction volumes across the network increased by approximately 1,000 per cent, while transaction values increased by approximately 120 per cent.

The growth we are seeing demonstrates that the infrastructure is working and that demand is increasing as more institutions and markets participate

Nigeria remains a significant contributor to that growth, recording an approximately 1,100 per cent increase in transaction volumes and a 125 per cent increase in transaction values over the same period.

PAPSS transactions have also demonstrated cost savings of between 92 and 95 per cent per transaction, a 99.99 per cent reduction in processing time and up to 80 per cent reduction in foreign exchange requirements.

Mr Ogbalu added: “The growth we are seeing demonstrates that the infrastructure is working and that demand is increasing as more institutions and markets participate. The next opportunity is to make these benefits available at much greater scale by working more closely with banks, fintechs, switches and other partners to bring PAPSS into the channels businesses and individuals use every day.”

PAPSS enables cross-border payments through participating financial institutions, including transactions using African currencies, helping connect payment ecosystems that have historically operated within national and regional boundaries.

As part of its next phase, PAPSS will focus on deeper market activation, greater customer awareness, development of priority payment corridors and wider availability of its services through participating financial institutions.

PAPSS currently provides three major solutions: the PAPSS Instant Payment System, the PAPSS African Currency Marketplace and PAPSSCARD. New solutions are also being piloted and are expected to be announced later in 2026.

The next phase of PAPSS’s growth will be discussed further at PAPSS COWRY 2026, its annual payments conference, taking place on 26 and 27 November in Addis Ababa, Ethiopia, and co-hosted with the National Bank of Ethiopia.

Mr Ogbalu concluded: “We have built the network, we have demonstrated the impact, and we are seeing usage accelerate. Our next phase is about taking all three to scale and ensuring that payments increasingly enable, rather than limit, the ability of African businesses and individuals to participate in opportunities across the continent.”

Distributed by APO Group on behalf of Afreximbank.


Continue Reading

Business

Angola’s Angolan National Agency for Petroleum, Gas and Biofuels (ANPG) Signs New Deepwater Deals at Angola Oil & Gas (AOG) 2026
Published

on

Angola

Angola’s national concessionaire formalizes new risk-service contracts and block entries across the Kwanza and Congo Basins while advancing further exploration and emissions-reduction initiatives

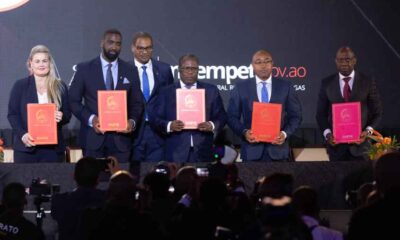
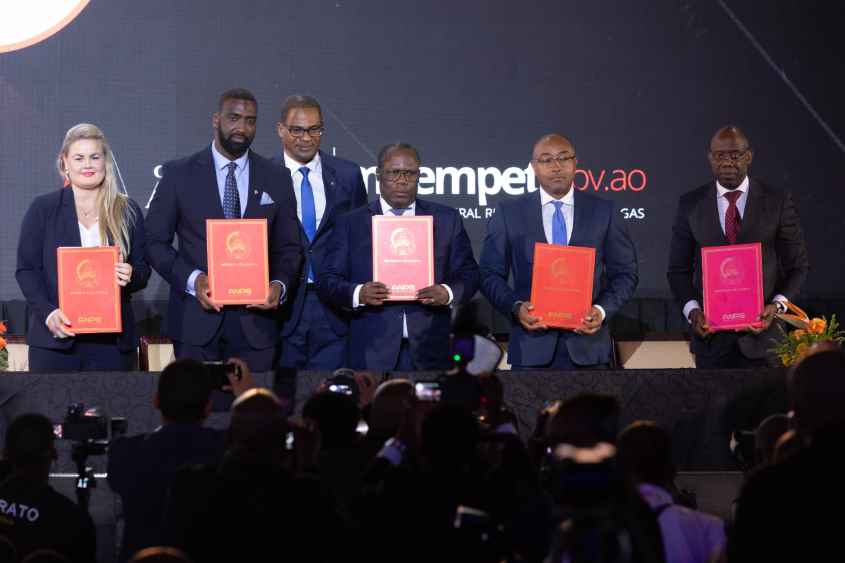
LUANDA, Angola, September 11, 2026/APO Group/ –Angola’s national concessionaire, the Angolan National Agency for Petroleum, Gas and Biofuels (ANPG), formalized a series of offshore entries, risk-service contracts and other agreements with international oil companies at Angola Oil & Gas 2026 on Wednesday, advancing exploration across the Kwanza and Congo Basins.


The first signing, overseen by ANPG Director of Negotiations Hélder Iombo, covered Risk Service Contracts for deepwater Blocks 19, 34 and 35 with Shell, Equinor and Sonangol E&P. The contracts establish terms for the exploration, appraisal, development and production of liquid and gaseous hydrocarbons.

Each contract provides for an initial exploration period of up to five years and a 30-year production period for each approved commercial discovery. Work commitments include seismic data reprocessing and the drilling of at least one exploration well.

The agreements build on a November 2025 pact covering 17 deepwater and ultra-deepwater blocks across Angola’s Kwanza and Congo Basins, advancing several concessions into formal exploration.

ANPG also signed Heads of Terms with Shell, QatarEnergy and Sonangol covering Blocks 8 and 22 in the Kwanza Basin. The agreement sets the framework for exploration, appraisal, development and production, including minimum work commitments, exploration periods, bonuses, contributions, penalties and applicable fiscal and contractual terms.

In the Congo Basin, ANPG signed a Risk Service Contract for Block 33/24 with Chevron, Shell and Sonangol. The agreement provides for a five-year exploration period and a 30-year production period for each commercial discovery. The work program includes reprocessing 2,000 square-kilometers of additional 3D seismic data, followed by at least one exploration well if the project advances to the next phase.

Separately, ANPG signed Risk Service Agreements for Blocks 17, 27, 32 and 21 in the Congo Basin with TotalEnergies as operator alongside ExxonMobil and Sonangol. ANPG and TotalEnergies also signed an agreement setting the terms and conditions for Block 32, supporting an extension of the existing operation and further investment.

Alongside the upstream agreements, ANPG and TotalEnergies signed a Memorandum of Understanding focused on reducing emissions from oil and gas production, improving methane measurement and exploring opportunities to monetize emissions.

The initiative builds on Sonangol and TotalEnergies joining the Oil and Gas Decarbonization Charter in 2023. Under the MoU, the companies will share technical experience and assess technologies including TotalEnergies’ AUSEA drones, which were deployed in 2022 to detect, measure and monitor methane emissions at a Block 3 field. The companies will also work to develop national expertise in greenhouse-gas management and assess international climate funds that could support decarbonization projects.

The initiative also aligns with Sonangol’s recent decision to join the UN-backed Oil and Gas Methane Partnership 2.0, of which TotalEnergies is already a member.

In a separate agreement, ANPG, the Moxico Provincial Government, Chevron and the Instituto Nacional de Gestão Ambiental (INGA) established indicative terms for assessing, structuring and preparing land access for a project in Moxico Province.

The initiative will begin with a 20-hectare pilot phase lasting two to three years, with potential expansion to 20,000 hectares based on its results. The project is intended to link emissions reduction with job creation, economic development and sustainable land use.

Distributed by APO Group on behalf of Energy Capital & Power.


Continue Reading

Trending