Connect with us

Business

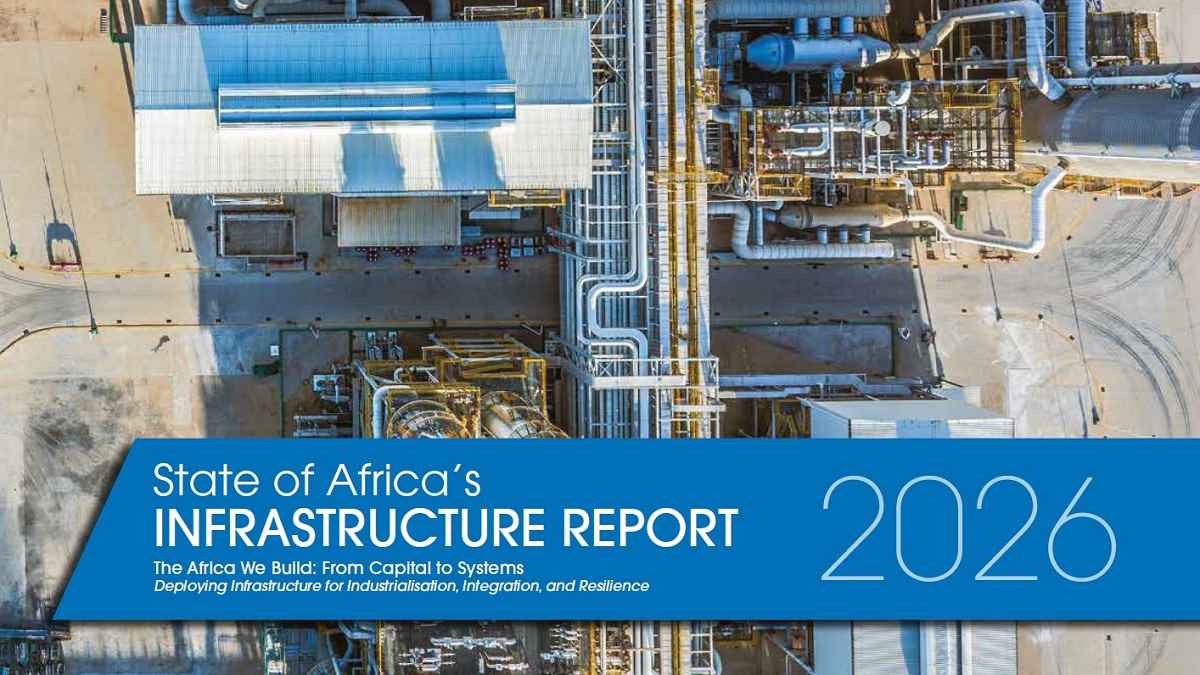
Africa Strengthens Foundations to Lead Its Own Financing as Domestic Pools Surpass External Flows, Africa Finance Corporation (AFC) Report Shows

Published

on

Africa

AFC’s State of Africa’s Infrastructure Report 2026 argues that Africa’s next development breakthrough will come from deploying domestic capital into infrastructure, industry and integrated systems at scale

NAIROBI, Kenya, April 23, 2026/APO Group/ —
  • Africa’s development challenge is increasingly shifting from capital raising to productive capital deployment in infrastructure and industry, according to AFC’s State of Africa’s Infrastructure Report 2026
  • Non-bank domestic capital pools now exceed US$2 trillion, surpassing ~US$1.7 trillion in cumulative external flows to Africa (2014–2024)
  • Official development assistance fell from US$83.8 billion in 2020 to US$73.5 billion in 2023, with further declines expected for 2025–2026
  • Sovereign issuance dropped from over US$29 billion in 2018 to US$4–6 billion annually in 2022–2023, with only limited recovery through 2024–2025
  • Domestic pension and insurance assets crossed US$1 trillion for first time
  • Central bank reserves at US$530 billion in 2025, from US$480 billion in 2024
  • Gold now represents ~17% of reserves, up from less than 10% in 2022–2023
  • Africa’s biggest infrastructure opportunity lies in integrated systems—connecting energy, transport, industry and digital layers into demand‑anchored ecosystems that improve bankability and enable scale


Africa’s domestic capital base has reached a scale that now exceeds external financing flows over the past decade, marking a turning point in how the continent funds its growth and industrialisation, according to the Africa Finance Corporation’s (www.AfricaFC.org) State of Africa’s Infrastructure Report 2026.

SAIR 2026 finds that cumulative external flows to Africa totalled approximately US$1.7 trillion between 2014 and 2024, while Africa’s non-bank domestic capital pools exceed US$2 trillion. The implication is clear: African capital now has a stronger foundation to play a significantly larger role in financing the continent’s development.

Launched at The Africa We Build Summit in Nairobi, co-hosted by AFC and H.E. Dr William Samoei Ruto, President of the Republic of Kenya, the SAIR 2026 report argues that the overarching development priority has shifted from capital mobilisation to intermediation—converting savings into infrastructure, industry, and productive investment at scale.

“The constraint is no longer capital—it is intermediation,” Samaila Zubairu, President & CEO of AFC, said at the The Africa We Build Summit today. “We have the savings, but not yet the systems to channel them into infrastructure and industry at scale. Closing that gap is now Africa’s most important economic task. The next phase of Africa’s infrastructure story must move beyond standalone assets towards integrated systems.”

Local Capital on the Rise

Driving the increase in domestic institutional capital, pension and insurance assets have surpassed US$1 trillion for the first time. Public development bank assets stand at US$276 billion, and sovereign wealth funds at US$164 billion, while central bank reserves increased from US$480 billion in 2024 to US$530 billion in 2025.

This increase has been supported in part by stronger commodity dynamics and rising gold accumulation. Gold now represents approximately 17% of Africa’s total reserves, up from less than 10% in 2022–2023, while physical holdings rose from 663 tonnes in 2022 to an estimated 738 tonnes in 2025.

Despite its increased scale, domestic capital remains largely concentrated in short-term, low-risk assets—particularly government securities—reflecting limited investable pipelines, regulatory incentives favouring liquidity, and insufficient risk-sharing mechanisms. The result is a persistent gap between available savings and long-term productive investment.

Africa is not capital-poor—it is capital-rich but system-poor

External Financing Recedes

At the same time, external financing is becoming less reliable, reinforcing the case for a domestic capital-led development model. Official development assistance to Africa fell from US$83.8 billion in 2020 to US$73.5 billion in 2023 and is projected to decline further. The OECD estimates global official development assistance fell 23.1% in 2025, the largest annual contraction on record.

Sovereign issuance remains well below pre-2019 levels, falling from over US$29 billion in 2018 to US$4–6 billion annually in 2022–2023, while foreign direct investment has remained concentrated at roughly US$45–55 billion annually, insufficient to meet the continent’s broad investment needs.

As a result, external capital is increasingly complementary, rather than foundational , to Africa’s development model.

From Assets to Integrated Systems

The biggest potential for capital deployment lies in demand-driven integrated infrastructure, according to SAIR 2026. In transport and logistics, corridors deliver the greatest value when designed as production ecosystems rather than transit routes—linking ports, rail, roads, logistics, storage, and trade facilitation to industrial demand. A continental backbone is already taking shape; the opportunity now is to improve performance, execution, and coordination.

This is particularly evident in East Africa. Mombasa—one of Africa’s busiest ports—handles more than 45 million tonnes of cargo annually, while rail investments are extending connectivity inland, including along the Naivasha–Kisumu corridor. In aviation, SAIR 2026 identifies air transport as the most immediate and scalable lever for integration. Across Kenya, Rwanda, and Ethiopia, aviation contributes a combined US$5.5 billion to GDP and supports around one million jobs, demonstrating how connectivity can rapidly translate into trade and growth.

Similarly, in energy, the priority is no longer incremental capacity additions alone, but integrated systems combining generation, transmission, storage, fuels, and industrial demand. Cross-border infrastructure such as the Ethiopia–Kenya interconnector shows how regional systems can move power to where it is needed most and improve system-wide efficiency.

Resilience Gap

Recent shocks—from Russia–Ukraine to the 2026 Gulf crisis—underscore the cost of fragmented systems and the urgency of building domestic processing, storage, and supply-chain resilience. The continent continues to import over 70% of its refined fuel and faces an estimated US$230 billion annual import bill across essential goods—including fuel, food, plastics, steel, and fertiliser, according to SAIR 2026.

In digital infrastructure, while connectivity has expanded rapidly, the next opportunity lies in building the “missing middle”—terrestrial backbone networks, metro fibre, data centres, Internet Exchange Points, and enterprise platforms that convert connectivity into productivity, services exports, and job creation.

Across all sectors and African countries, the report’s conclusion is consistent: the development challenge is increasingly institutional and systemic. Capital exists, and infrastructure assets are expanding. The next breakthrough will come from linking finance, energy, transport, industry, and digital systems into coherent ecosystems capable of supporting growth at scale.

“Africa is not capital-poor—it is capital-rich but system-poor,” said Zubairu. “The priority must be to build the institutions, instruments, and project pipelines required to deploy that capital into infrastructure and industry at scale.”

Distributed by APO Group on behalf of Africa Finance Corporation (AFC).

Business

Strategic Architect of African Convention Bureaus Rick Taylor Joins African Collaborations Group (ACG) Advisory Board to Advance Sport and Entertainment Districts Across Africa

Published

on

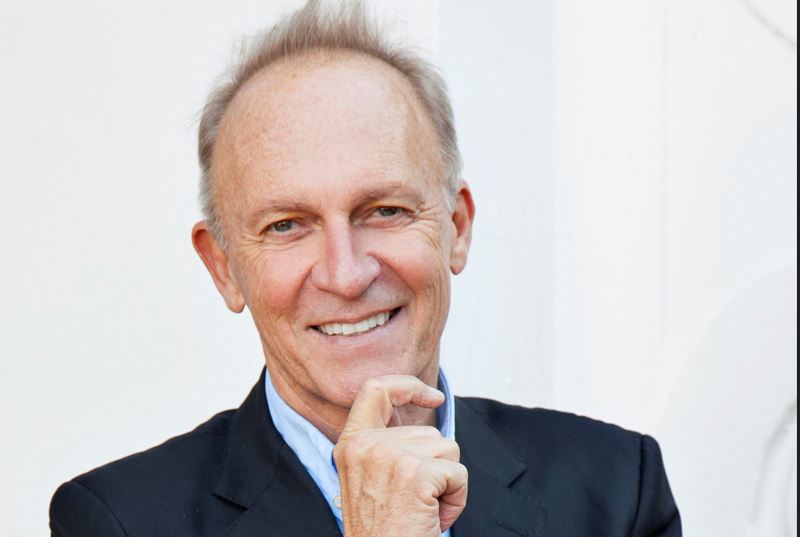
Rick Taylor is one of Africa’s most experienced strategists in destination development and the business tourism sector

LONDON, United Kingdom, October 26, 2026/APO Group/ –African Collaborations Group (ACG) (www.ACGafrica.com), the leading strategic project origination and collaboration platform focused on the industrialisation of sport in Africa through the origination of bankable sport and entertainment district ecosystems, today announced the appointment of Rick Taylor to its Advisory Board.


Rick Taylor is one of Africa’s most experienced tourism strategists, with more than three decades of expertise in destination development and business events, also known as MICE (Meetings, Incentives, Conferences, Events and Exhibitions). As Founder and Chief Executive Officer of The Business Tourism Company, a Cape Town-based international consultancy, he has led more than 100 tourism advisory, strategy and training projects worldwide and has been the strategic architect of national destination strategies and Convention Bureau projects across Africa, including in South Africa, Namibia, Rwanda, Kenya, Tanzania, Ethiopia, Uganda, Senegal, Cameroon, Zambia, Togo and Mozambique.

Rick was the architect of Africa’s first Convention Bureau in Cape Town, which has maintained the #1 position in Africa in the International Congress and Convention Association (ICCA) city ranking for more than two decades. Since then, he has devoted his career to positioning business events as a strategic pillar of tourism, investment and socio-economic development across the continent.

The global business events sector has now surpassed pre-pandemic levels, reaching an estimated USD 1.5 trillion, yet Africa hosts only around 3% of the world’s association meetings. Rick has spent his career addressing this structural gap by helping countries build the strategies, institutions, infrastructure and international positioning required to compete for a greater share of the global business events economy.

His presence on our Advisory Board significantly strengthens ACG’s capacity to originate projects that combine these dimensions from the outset

A defining feature of Rick’s approach is what he calls “Lalibela thinking” — a 50- to 100-year perspective that sees MICE not simply as an events industry, but as long-term economic infrastructure capable of driving investment, tourism, job creation, skills development and poverty alleviation. His work has helped shape business events infrastructure, convention bureaus and national MICE strategies across Africa.

His appointment to the ACG Advisory Board reflects a core ACG conviction: that large-scale sport and entertainment districts must be conceived from the outset as integrated economic ecosystems spanning sport, entertainment, hospitality, tourism and business events. Convention Centres, conference facilities and other business events infrastructure are essential components of such districts. They can generate high-value activity on non-match and non-concert days, strengthen year-round hotel and hospitality demand, and connect the district to the wider tourism and business travel economy of its host country.

Rick therefore brings to ACG a rare combination of strategic and practical expertise: deep knowledge of African destination development; pan-continental relationships with tourism ministries, national tourism organisations and other public-sector stakeholders; hands-on experience in establishing Convention Bureaus and business events infrastructure; and a long-term perspective on the role of business events in African socio-economic development. These capabilities are directly relevant to ACG’s work in originating and structuring large-scale sport and entertainment district projects across the continent.

“Rick Taylor is one of the most respected voices in African business tourism, and his career has literally built the Convention Bureau architecture that powers business events across the continent. His appointment reflects a foundational conviction at ACG: that sport and entertainment districts are not stadiums and concert halls standing alone, but integrated ecosystems that generate value across sport, entertainment, hospitality and business events. Sport, entertainment and convention infrastructure is district infrastructure. His presence on our Advisory Board significantly strengthens ACG’s capacity to originate projects that combine these dimensions from the outset,” said Nicolas Pompigne-Mognard (www.Pompigne-Mognard.com), Founder and Executive Chairman of ACG.

The ACG Advisory Board provides strategic guidance as ACG originates and structures large-scale sport and entertainment district projects across the continent, aligning governments, development finance institutions (DFIs), investors, sport bodies and infrastructure partners to support the development of financially sustainable, mixed-use district ecosystems.

Africa’s sport economy is projected to reach $20 billion by 2035, yet the continent continues to lack the integrated district ecosystems required to support large-scale development. ACG addresses this gap by originating bankable sport and entertainment district projects, moving beyond single-venue development models towards mixed-use, revenue-generating and financially sustainable district ecosystems.

Through its collaborative model, ACG convenes governments, PPP authorities and regulators, development finance institutions, private investors, developers, designers and engineers, legal and transaction advisors, operators, sport federations and leagues, event promoters, media and broadcast partners, academic institutions and host communities, creating structured pathways from concept to feasibility, bankability and delivery.

Distributed by APO Group on behalf of African Collaborations Group (ACG).


Continue Reading

Business

Moody’s affirms Islamic Corporation for the Insurance of Investment and Export Credit (ICIEC)’s Aa3 Insurance Financial Strength Rating with Stable Outlook

Published

on

Moody’s cited ICIEC’s strengthening standalone credit profile, including its role as a leading multilateral provider of Shariah-compliant export credit and investment insurance and reinsurance solutions

JEDDAH, Saudi Arabia, October 25, 2026/APO Group/ –The Islamic Corporation for the Insurance of Investment and Export Credit (ICIEC) (http://ICIEC.IsDB.org), a Shariah-based multilateral insurer and member of the Islamic Development Bank Group, is pleased to announce that Moody’s Ratings has affirmed the Corporation’s Aa3 Insurance Financial Strength Rating (IFSR) with a Stable Outlook, reflecting the agency’s ongoing confidence in the Corporation’s strong financial fundamentals and strategic importance as a member of the Islamic Development Bank (IsDB) Group.


This affirmation is a strong endorsement of ICIEC’s financial resilience and our ability to manage risks effectively

Moody’s cited ICIEC’s strengthening standalone credit profile, including its role as a leading multilateral provider of Shariah-compliant export credit and investment insurance and reinsurance solutions. The agency highlighted improved underwriting performance supported by enhanced risk management, strong asset quality and liquidity, and strong capital adequacy. The Corporation’s preferred creditor status among its Member Countries further reinforces its financial strength and institutional standing.

The rating also benefits from the strong institutional and shareholder support of the IsDB and sovereign shareholders, including Kingdom of Saudi Arabia.

Commenting on the rating affirmation, Dr. Khalid Khalafalla, Chief Executive Officer of ICIEC, stated: “This affirmation is a strong endorsement of ICIEC’s financial resilience and our ability to manage risks effectively in an increasingly complex global environment. It strengthens our position as a trusted multilateral partner, enabling us to expand our reach, mobilise investment and deliver meaningful development impact across our Member Countries through innovative Shariah-compliant insurance solutions.”

The Stable Outlook primarily reflects expected ongoing shareholder support, alongside expectations of continued risk management improvements and strong financial fundamentals as ICIEC expands and diversifies its operations while maintaining prudent underwriting discipline. Moody’s also identified ICIEC’s exposure to geopolitical risks and its smaller operational scale relative to peers as moderating factors.

Distributed by APO Group on behalf of Islamic Corporation for the Insurance of Investment and Export Credit (ICIEC).

Email:
ICIEC-Communication@isdb.org

Follow us on:
X: https://apo-opa.co/4soX4yD
Facebook: https://apo-opa.co/47Dx8pC
LinkedIn: https://apo-opa.co/4svXyTW
YouTube: https://apo-opa.co/4spZ2Pw
Instagram: https://apo-opa.co/4kcQsRV

About The Islamic Corporation for the Insurance of Investment and Export Credit (ICIEC):
As a member of ‘AAA’ rated Islamic Development Bank (IsDB), ICIEC commenced operations in 1994 to strengthen economic relations between OIC Member States and promote intra-OIC trade and investments by providing risk mitigation tools and financial solutions. The Corporation is the only Islamic multilateral insurer in the world. It has led from the front to deliver a comprehensive suite of solutions to companies and parties in its 51 Member States. ICIEC, for the 19th consecutive year, maintained an “Aa3” insurance financial strength credit rating from Moody’s, ranking the Corporation among the top of the Credit and Political Risk Insurance (CPRI) Industry. Additionally, S&P has reaffirmed ICIEC “AA-“ long-term Issuer Credit and Financial Strength Rating for the third year with Stable Outlook.  ICIEC’s resilience is underpinned by its sound underwriting, global reinsurance network, and strong risk management policies. Cumulatively, ICIEC has insured more than USD 139 billion in trade and investment. ICIEC activities are directed to several sectors such as energy, manufacturing, infrastructure, healthcare, and agriculture.

For more information; visit: http://ICIEC.IsDB.org


Continue Reading

Business

Invictus Investment Enters Into Agreement With Helios Investment Partners for Minority Stake in Merec Industries

Published

on

The new partnership will support these plans by combining Invictus Investment’s expertise across the agro-food value chain with Helios’ track record of investing in and supporting market-leading businesses across Africa

We welcome Helios, one of Africa’s leading private equity investors, as our partner in the expansion of Merec

DUBAI, United Arab Emirates, October 23, 2026/APO Group/ —
  • Helios to acquire a significant minority stake in Merec Industries, Mozambique’s largest flour milling company
  • Partnership combines Invictus Investment’s sector knowledge and operational capabilities with Helios’ extensive experience across Africa to support Merec Industries’ growth in Mozambique and the wider region
  • Transaction expected to close by the end of 2026, subject to customary closing conditions, including regulatory approvals

Invictus Investment (ADX: INVICTUS) (https://InvictusInvestment.ae), a leading holding company specialised in agro-food commodities across the Middle East and Africa, and Helios Investment Partners (“Helios”), a leading Africa-focused private investment firm, today announced that Helios Fund V (“Helios V”) has entered into an agreement to acquire up to a 49% interest in Stratton Africa Holdings Limited, the Mauritius-incorporated holding company of Merec Industries (“Merec”), from Invictus Investment.


The transaction is expected to close by the end of 2026, subject to customary closing conditions, including regulatory approvals, after which Invictus Investment will remain the majority shareholder.

Founded in 1998, Merec is Mozambique’s largest flour milling company, processing wheat and corn into an integrated product portfolio spanning flour, pasta, biscuits and animal feed. Its mills, production facilities and silos are strategically located in each of Mozambique’s three principal port regions: Beira, Maputo and Nacala – making it the only miller with manufacturing facilities in all three. Merec also owns a grain terminal at the port of Maputo. This footprint supports a nationwide distribution network serving wholesalers, retailers, bakeries, feed producers and distributors, underlining Merec’s important role in the production and supply of essential food products across Mozambique.

Invictus Investment acquired Merec in January 2025 through the purchase of its holding company, Stratton Africa Holdings Limited, as part of its strategy to expand its agro-food business in high-potential African markets and strengthen its capabilities across the value chain. Since the acquisition, Merec’s operating performance has improved significantly, and this has prompted a more ambitious growth strategy to expand the business beyond its core operations into new food categories in Mozambique and across the wider Southern African Development Community (“SADC”) region.

The new partnership will support these plans by combining Invictus Investment’s expertise across the agro-food value chain with Helios’ track record of investing in and supporting market-leading businesses across Africa. Together, the shareholders will also work on furthering Merec’s governance framework, leadership capabilities, ESG practices and broader development impact.

Commenting on the announcement, Amir Daoud Abdellatif, CEO of Invictus Investment, said: “We welcome Helios, one of Africa’s leading private equity investors, as our partner in the expansion of Merec. With its strong focus on high-growth sectors across the continent, Helios’ regional expertise will be instrumental in accelerating Merec’s next phase of growth. Since Invictus Investment’s acquisition of Merec, its position as Mozambique’s largest flour milling company has been strengthened and consolidated, and now, our shared ambition with Helios is to build on the business’s contribution to food security and local employment in Mozambique and develop it into a regional food platform for Southern Africa. This partnership aligns perfectly with our strategic approach to acquisitions, which has always been to build strong businesses alongside high-calibre partners that support our long-term vision of building a fully integrated agro-food enterprise.”

Tope Lawani, Co-Founder and Managing Partner of Helios Investment Partners, added: “Merec has built a distinctive position in Mozambique, with a nationwide footprint, strong brands and an important role in the country’s staple foods market. The consumer non-discretionary sector is a key strategic focus for Helios, and we bring a proven track record of investing in and scaling resilient businesses that serve essential consumer needs across Africa. We see significant opportunity to build on Merec’s strengths and are pleased to partner with Invictus Investment and the management team to support the company’s next phase of growth.”

Akin Gump Strauss Hauer & Feld is acting as legal counsel to Helios, with GDA Advogados as Mozambican counsel. Freshfields is acting as legal counsel to Invictus Investment.


*Please refer to heliosinvestment.com/news and invictusinvestment.ae/investor-relations/ for more information.


Distributed by APO Group on behalf of Invictus Investment Company PLC.


Continue Reading

Trending

Exit mobile version