Connect with us
Anglostratits

Business

Declining addressability, brand safety and ad fraud are set to define programmatic advertising over the next year

Published

on

programmatic advertising
  • More than half (60%) of advertisers and agencies cite brand safety as top programmatic concern
  • New survey-led research by WARC and NewtonX explores major trends in programmatic

14 August 2024 – WARC has today released The Future of Programmatic 2024, a report covering the major trends shaping programmatic advertising over the coming 12 months, together with practical guidance for advertisers evolving their programmatic and ad tech capabilities.

Programmatic advertising is digital advertising that is bought, sold and placed using automated technologies and algorithms. The report highlights key trends across five different areas: programmatic priorities and concerns, signal loss and cookie deprecation, supply chain transparency, sustainability, and spending intentions.

Findings are based on an exclusive survey of 100 programmatic experts, conducted in July 2024 by WARC in partnership with B2B market research company, NewtonX, and complemented by expert commentary and external research.

Paul Stringer, Managing Editor Research and Insights, WARC, says: “Our Future of Programmatic report arrives in the wake of the announcement from Google that third-party cookies will no longer be fully phased out from the advertising ecosystem. While it represents a reversal of sorts, this should not encourage complacency. The industry still needs to evolve to meet the demands of a privacy-first ecosystem.

“Declining addressability, brand safety and ad fraud, continue to concern marketers, and addressing these concerns becomes even more important as increasing volumes of spend are transacted programmatically each year.”

Key challenges outlined in WARC’s Future of Programmatic 2024 report are:

Brand safety tops list of programmatic concerns

Accounting for more than 70% of digital spend, programmatic channels play a critical role in helping advertisers achieve their wider marketing and business objectives.

Whilst two-thirds of advertisers and agencies surveyed are somewhat satisfied with the contribution of programmatic advertising to driving business outcomes, there is a recognition that there is room for improvement.

Much of the current dissatisfaction is rooted in concerns around brand safety. Recent reports have shown advertisers are spending millions of dollars on low-quality ad placements that violate brand safety standards.

More than half (60%) of the advertisers and agencies surveyed highlighted this issue as one of their biggest causes for concern, with 56% selecting improved advertising verification capabilities as a top priority.

Hannah Rook, Head of Intelligence and Insights, MediaBrands Magna Group, says: “Advertisers and agencies need to take a more proactive and comprehensive approach to brand safety, expanding their placement criteria to make better decisions and ensure their ads appear in appropriate and relevant environments.”

Advertisers are underprepared for a cookie-diminished world

Google will no longer be withdrawing cookies from the digital advertising ecosystem, but will nonetheless play a diminished role in the future.

Many advertisers are still struggling to adapt to this new world, despite concerns about the impact of signal loss on various areas including targeting, data access, audience segmentation and measurement. Only a quarter (25%) of survey respondents agree that advertisers are making adequate progress.

Consistent with other research, advertisers are doubling down on the collection of first-party data. More than three quarters (76%) of respondents are implementing first-party data strategies, with more than half (57%) highlighting this as the most promising solution.

Wayne Blodwell, Co-Founder and CEO, Impact Media, says: “Google’s decision to keep cookies has not changed the direction of travel for the industry. Advertisers should continue leaning into smart, cookie-free techniques like attention and econometrics to prepare for a privacy-first world.”

The industry is failing to take action on transparency

Across the programmatic advertising supply chain, ad fraud and wastage are rife. According to the ANA’s programmatic study, just 36 cents of every dollar spent on programmatic advertising reaches the consumer, and a quarter of the $88 billion spent on open web programmatic is wasted on low-quality and fraudulent ad impressions.

However, a year on from the report less than half (49%) of advertisers and agencies have established direct contracts, or taken the necessary steps to verify or audit the quality of ad impressions.

Collective action is required to urgently address these issues and clean up the ‘murky’ media supply chain.

Emissions reduction is not a priority at most (59%) companies

The programmatic advertising industry produces more than 215,000 metric tons of carbon emissions in a single month across five leading economies, according to Scope3.

To help address the climate crisis, marketers need to take more responsibility for reducing the carbon footprint of activities related to advertising. This includes programmatic, which generates significant emissions through its notoriously complex supply chain.

Nearly two-thirds (59%) of agencies and advertisers surveyed for the report say that reducing emissions generated by programmatic advertising is not a priority for their organisation. Less than a third (31%) said they had adopted a framework or set of methodologies to measure the carbon emissions from their digital advertising. Another third (34%) have taken no action at all to reduce the carbon impact of their programmatic advertising campaigns.

More than half (52%) of those surveyed cite a lack of industry-wide standards as a clear barrier to emissions reduction. Nearly half (48%) highlight a lack of knowledge / skills around reducing the carbon footprint of advertising activities.

Mark Andrews, Senior Consultant, ID Comms, says: “Some advertisers are using their media agencies to forecast carbon emissions on their media plans. This is educating planners and buyers and helps media teams think about carbon emissions as well as considering how practical decisions at the planning stage could lower emissions, without negatively impacting the effectiveness of media planning/buying.”

Open web investment decreases as walled garden spend grows

Despite evidence suggesting that the open web remains the arena in which audiences spend most of their time, investment in walled gardens appears to be growing. WARC forecasts predict that just five platforms will take over half of global advertising spend this year. Three-quarters of survey respondents (76%) say they are spending 40% or less of their budgets on open web advertising.

Advertisers and agencies are opting to spend more on programmatic direct deals (e.g. programmatic guaranteed, preferred deals) at the expense of traditional real-time bidding. More than half (56%) of respondents purchase display inventory using programmatic methods. Retail media inventory also features high on the list of channels transacted programmatically. Social and gaming are anticipated to receive largest increases in programmatic investment.

Read a sample report of The Future of Programmatic here. WARC subscribers can read the report in full. A podcast will be available from 27 August.

The report is part of WARC Strategy’s Evolution of Marketing, a content programme of in-depth forward-looking reports focusing on the future of the marketing discipline by drawing on the latest evidence, emerging trends, technologies, media, social influences and other drivers of change.
Business

African Energy Week (AEW) 2026 Technical Sessions Put Technology Behind Africa’s Next Energy Projects in Focus

Published

on

African Energy Chamber

Day 2 technical sessions at African Energy Week 2026 will examine frontier exploration, major gas developments, project economics and the technologies supporting Africa’s expanding oil, gas and LNG sectors

CAPE TOWN, South Africa, September 22, 2026/APO Group/ –African Energy Week (AEW) 2026’s Day 2 Technical Stages will put the technology and technical expertise behind Africa’s next wave of energy projects in focus, with sessions covering subsurface interpretation, deepwater exploration, gas development, project economics, digitalization, offshore operations and infrastructure.


The program will unfold across two exhibition-hall stages, with the Drill Room focusing on practical applications across exploration, gas development, offshore operations and LNG, while the Innovation Hub will examine frontier exploration, energy markets, digital technologies and infrastructure. Together, the sessions connect project-level technologies with the wider investment and development challenges facing Africa’s energy industry.

The day opens with GeoEnergy Petroleum Director Maged Fahim, who will examine how legacy and newly acquired subsurface datasets can be integrated with modern technologies to identify additional upstream opportunities. TGS Principal Exploration Advisor Felicia Winter will then focus on Angola’s deepwater basins, examining how modern seismic acquisition and imaging can be used to reinterpret existing data and evaluate frontier plays.

The discussions come as Angola seeks to build on renewed offshore activity. TotalEnergies announced in September that it plans to invest $10 billion in Angola over the next five years, including in exploration, while advancing its $6 billion Kaminho deepwater development.

Gas development will take center stage through two presentations by TotalEnergies. Alexandre Depiesse, GPI Venus, will address appraisal strategies and commercial viability for Orange Basin discoveries, while Mozambique LNG Operations and Project Director Nicolas Cambefort will examine development and optimisation of the Rovuma Basin gas resources. Mozambique LNG, a 13.1-million-ton-per-year project in Area 1 led by TotalEnergies, resumed activities in January 2026 following the lifting of force majeure, putting development of Mozambique’s major offshore gas resources back into focus.

AEW 2026 reflects the practical challenges facing Africa’s energy industry as projects move from resource potential toward development and production

The Republic of Congo National Showcase will provide another perspective on Africa’s expanding LNG industry. The country’s Congo LNG project reached a new stage in February 2026 with the start of commercial production from its second phase. The addition of the Nguya FLNG unit brought total liquefaction capacity to 3 million tons per year, expanding Congo’s ability to monetize its offshore gas resources.

The program will then broaden from individual projects to the continent-wide investment outlook with the launch of The State of African Energy 2027. AEC Senior Vice President Verner Ayukegba and S&P Global Energy Executive Director Max Pietzsch will present the outlook, covering upstream oil and gas, LNG, downstream markets, power, renewables and critical minerals against changing demand, trade flows and energy security requirements.

Project decision-making will remain under examination as S&P Global Energy Technical Research Analyst Tasnika Goorhoo presents “From Limited Data to Better Decisions: How Benchmarking Strengthens Upstream Project Outcomes.” The session will examine how comparative project data can help operators assess performance, costs and development outcomes.

NOV Vice President Mats Anderson will address offshore optimization through high-speed downhole connectivity and real-time distributed measurements, examining how faster access to downhole information can improve operational visibility and decision-making.

Infrastructure will also feature prominently, with Kenyon International West Africa CEO Victor Ekpenyong examining asset integrity and pipeline infrastructure through the company’s CACTUS and FlexSteel technologies. Honeywell Technologies Africa will close the technology-focused sessions with its end-to-end LNG offering, while SLB, InSwitch, the Petroleum Directorate of Sierra Leone and PETROSEN will bring additional perspectives on technology, digitalization and energy services.

“AEW 2026 reflects the practical challenges facing Africa’s energy industry as projects move from resource potential toward development and production,” said NJ Ayuk, Executive Chairman of the AEC. “From subsurface interpretation and deepwater exploration to LNG development, project benchmarking, digitalization and infrastructure, these technical sessions highlight the expertise and technologies needed to develop Africa’s resources efficiently and create lasting value across the energy value chain.”

AEW 2026 takes place from October 12–16 in Cape Town, bringing together governments, investors, operators and technology providers to discuss investment, project development and the future of Africa’s energy sector.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Business

Rising power costs put energy strategy at the centre of industrial competitiveness

Published

on

South Africa

C&I Energy + Storage Summit Johannesburg to focus on the procurement, cost and investment decisions facing South Africa’s large energy users

JOHANNESBURG, South Africa, September 22, 2026/APO Group/ –The cost of electricity is no longer only an energy issue for South African businesses. It is increasingly a question of competitiveness, investment and long-term operational resilience.

Recent figures show the pressure on large power users. Business Day reported on 7 September that South Africa’s mining and industrial majors paid Eskom R115 billion for electricity in the 2025/26 financial year. According to Eskom’s annual report, industrial electricity demand fell by more than 22% over the same period as high power costs weighed on energy-intensive operations.


At the same time, major businesses are moving to alternative supply. Reuters reported on 26 August that South African mining companies are accelerating investment in renewable energy to cut costs, diversify supply and meet decarbonisation targets.

For commercial and industrial energy users, the question is no longer simply how to secure power. It is how to buy it, what to invest in, and which energy strategy makes the strongest commercial sense.

Energy procurement is becoming more complex

Businesses are now weighing several procurement options at once. Should they sign a long-term PPA? Buy through an electricity trader? Wheel renewable power across the grid? Invest in behind-the-meter generation? Add battery storage? Each option carries different implications for cost, risk, contracting and long-term flexibility.

These decisions will take centre stage at the C&I Energy + Storage Summit Johannesburg, taking place on 28–29 October 2026 at The Maslow Hotel, Sandton. The programme is built around the practical challenges facing energy buyers today, with a focus on real projects, commercial models and implementation rather than technology in isolation.

A programme built around the buyer’s decisions

The summit closes with the C&I Decision Clinic: Ask the Experts, a masterclass where attendees submit real project challenges in advance and receive practical, anonymised responses from experts. Questions on the table include whether to build onsite PV or sign a wheeled PPA, how much battery storage makes commercial sense, what a bankable project preparation pack should contain, and what financiers require before term sheet stage.

It follows The C&I Energy Playbook: Five decisions business leaders need to make now, a closing panel in which the moderators of key summit sessions distil the programme into the priorities C&I businesses should act on.

Other sessions address the questions buyers are asking now:

  • Energy storage beyond backup power: unlocking commercial value examines peak shaving, demand charge management, energy arbitrage and hybrid PV-plus-storage business models, along with the operational realities of dispatch, degradation and warranties.
  • Making public-private engagement work for you unpacks how wheeling agreements are structured in practice, where interface risks arise, and how businesses can engage utilities and municipalities early.
  • Reducing energy costs without building new generation is a case-study-led workshop on energy efficiency, operational optimisation, demand response and digital energy management.
  • Projects Spotlight gives energy users the floor to share the strategies they have implemented, the lessons learned and the outcomes achieved.

The programme opens with the keynote panel Threats and opportunities in South Africa’s industrial future, bringing together policymakers, industrial leaders, financiers, and energy and water experts.

Bringing energy buyers into the conversation

The summit’s Hosted Buyer Programme is designed for qualified end-user energy buyers across sectors including mining, manufacturing, property, agriculture and other energy-intensive industries. Hosted buyers take part in the full programme and receive curated engagement with solution providers across energy procurement, storage deployment and project development.

Four events, one venue

The summit is co-located with the EIUG Conference, Water Security Africa and the Data Centre Summit, bringing the energy, water and digital infrastructure communities together in Sandton. It is brought to you by Enlit Africa, with ESI Africa as host media, and is accredited by the SAIEE.

Qualified commercial and industrial energy users can apply for the Hosted Buyer Programme at https://apo-opa.co/4yPnXOg, and bring their project questions to the Decision Clinic.

Full programme: https://apo-opa.co/4xK2ANv


Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Events

Beyond the carbon credit: Who sets the terms for Africa’s carbon markets?

Published

on

From project ownership and verification to pricing and benefit-sharing, CMAS 2026 will bring African market leaders and global decision-makers together to examine who creates and captures value

KIGALI, Rwanda, September 22, 2026/APO Group/ –A carbon credit may be traded as a single unit, but its value is shaped long before it reaches a buyer. Decisions about project ownership, finance, data, verification and benefit-sharing determine who participates, who carries the risk and who ultimately benefits. As new regulations and international partnerships expand market access, these questions are becoming increasingly important across Africa.


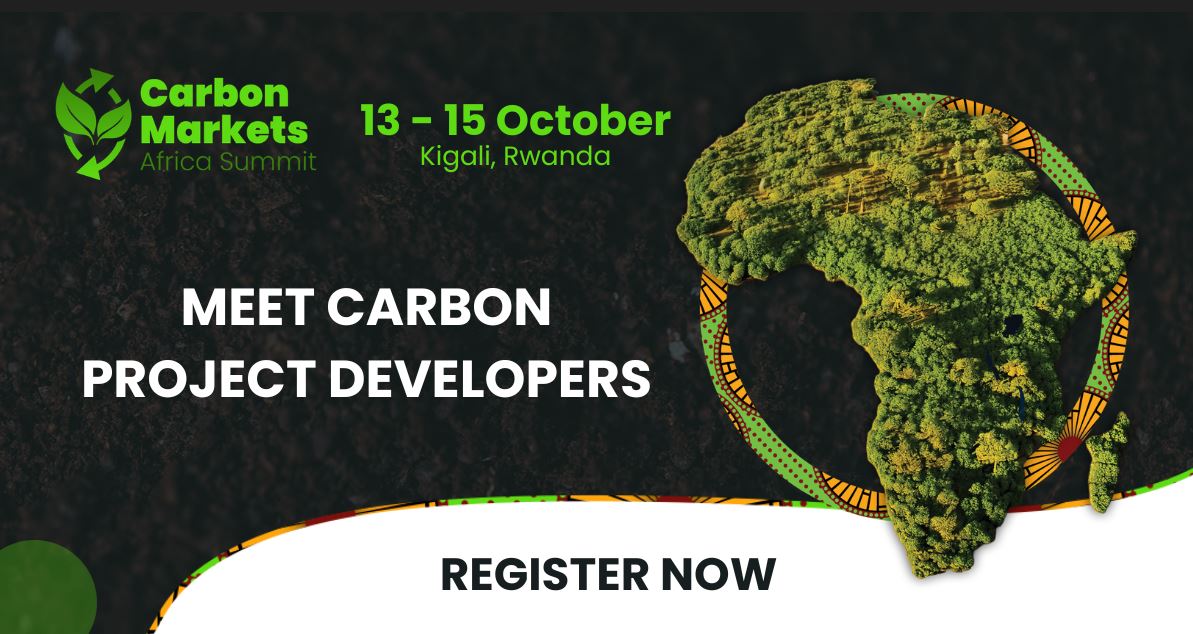
They will be central to the Carbon Markets Africa Summit (CMAS) 2026, taking place from 13 to 15 October at the Kigali Convention Centre in Rwanda. The summit will convene African governments, project developers, investors, buyers and technical experts involved in decisions across the carbon-market value chain.

Countries are approaching these decisions from different regulatory, economic and environmental positions. While recent developments in East Africa demonstrate growing market activity, questions concerning international requirements, technical capacity, investment and benefit-sharing are relevant across Africa.

Ousmane Fall SARR, Coordinator of the West African Alliance on Carbon Markets and Climate Finance, says:

“African countries are developing carbon markets from different starting points. Stronger African expertise and regional cooperation will be important if the continent is to contribute to the standards and market practices that determine how its projects compete, attract investment and create value.”

Against this continental backdrop, East Africa provides a timely example of how the market is developing. In January 2026, Rwanda and Singapore invited applications for carbon-credit projects under their bilateral Implementation Agreement, aligned with Article 6 of the Paris Agreement. Credits from authorised projects may be used by eligible Singapore-based carbon tax-liable companies to offset up to 5% of their taxable emissions, subject to both governments’ requirements.

African countries are developing carbon markets from different starting points

Across the continent, carbon market frameworks are rapidly taking shape. Kenya and Uganda are strengthening regulatory oversight, regional partnerships are helping governments build market capacity and infrastructure, and South Africa is advancing reforms to modernise its carbon-credit ecosystem and attract investment. Together, these developments are bringing greater focus to questions of authorisation, project ownership, verification, pricing and access to international buyers, while also raising expectations that carbon finance should deliver sustainable economic and development value beyond the credit itself.

Emmanuelle Nicholls, Portfolio Director for CMAS, says:

“A carbon credit may be the final product, but behind it are decisions about ownership, data, risk, pricing and who ultimately benefits. The conversations in Kigali will examine what credible participation looks like across the full carbon-market value chain.”

These decisions have consequences beyond individual transactions. Carbon finance is increasingly connected to conservation, agriculture, soil restoration, food security, clean energy and waste management. Its success will therefore also be judged by whether projects produce credible environmental outcomes and lasting benefits for African economies and communities.

A practical example comes from the Chinko Conservation Area in the Central African Republic, where revenue from the Chinko Carbon Project is channelled through a community fund that supports locally selected initiatives, including the expansion of a medical centre in Agoumar. At CMAS 2026, African Parks and Welthungerhilfe, both Bronze Sponsors, will share perspectives on how carbon finance can support conservation, climate resilience, food systems and community development, while highlighting broader questions around project governance, impact and the distribution of value.

From project-level impact to market-wide structures, these questions will underpin discussions at CMAS 2026. The programme will address government authorisation, buyer requirements, pricing and offtake, investment risk, early-stage finance, registries and African measurement, reporting and verification capacity. It will connect the question of who sets the terms with the practical requirements for building credible, investment-ready projects and transactions.

CMAS 2026 is hosted by the Ministry of Environment of Rwanda, with UNDP and the African Development Bank as host organisations, the Development Bank of Southern Africa as host partner and AUDA-NEPAD as strategic institutional partner.

Taking place ahead of COP31, CMAS will focus attention on the decisions behind every carbon credit and what they mean for African governments, projects, investors and communities.

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Trending