Connect with us
Anglostratits

Business

Senegal: African Development Bank agrees loan of nearly €87 million for Agropole Nord

Published

on

African Development Bank

The Bank’s contribution accounts for 30.7% of the estimated €283.05 million total project cost

ABIDJAN, Ivory Coast, November 22, 2023/APO Group/ — 

Meeting in Abidjan on Wednesday 22 November 2023, the Board of Directors of the African Development Bank Group (www.AfDB.org) approved a €86.89 million loan to Senegal to develop an agribusiness processing zone in the north of the country.

The Bank’s contribution accounts for 30.7% of the estimated €283.05 million total project cost. The Islamic Development Bank (21.2%), the West African Development Bank (15.9%), Sponsor Dette (19.3%) and Sponsor Equity (7.7%) are the other contributors to the implementation of ‘Projet Agropole Nord’, in English, ‘Agricultural Hub North Project’.

The project is intended to improve industrial processing capacities for agricultural, forestry, pastoral, fisheries products and related services, while also sustainably increasing household incomes and food security. The Senegalese Government is contributing 5.2% of the project cost.

The project is one of five integrated and competitive agricultural hubs created by the Senegalese Government under its Plan for an Emerging Senegal for 2025. It comes after an earlier Board approval of the Agropole Sud (Southern Agropole) and Agropole Centre (Central Agropole) projects to cover the regions of Kolda, Sédhiou and Ziguinchor, in southern Senegal, and the regions of Diourbel, Fatick, Kaffrine and Kaolack, in the centre of the country. The project will be implemented by the Senegalese Ministry of Industrial Development and of Small and Medium Industries, with the objective of boosting exports and strengthening entrepreneurship.  

The project will foster the emergence of three agribusiness development hubs and will facilitate the networking of stakeholders in the value chains

“The project will foster the emergence of three agribusiness development hubs and will facilitate the networking of stakeholders in the value chains,” said Mohamed Chérif,  the African Development Bank’s Country Representative in Senegal. “It will serve as a multi-sector platform for the incubation and integration of technologies, equipment and services to support small and medium-sized enterprises, industries and professional agricultural organizations. These hubs will help reduce the factors of migration-related fragility and climate change that can be seen in the project area.”

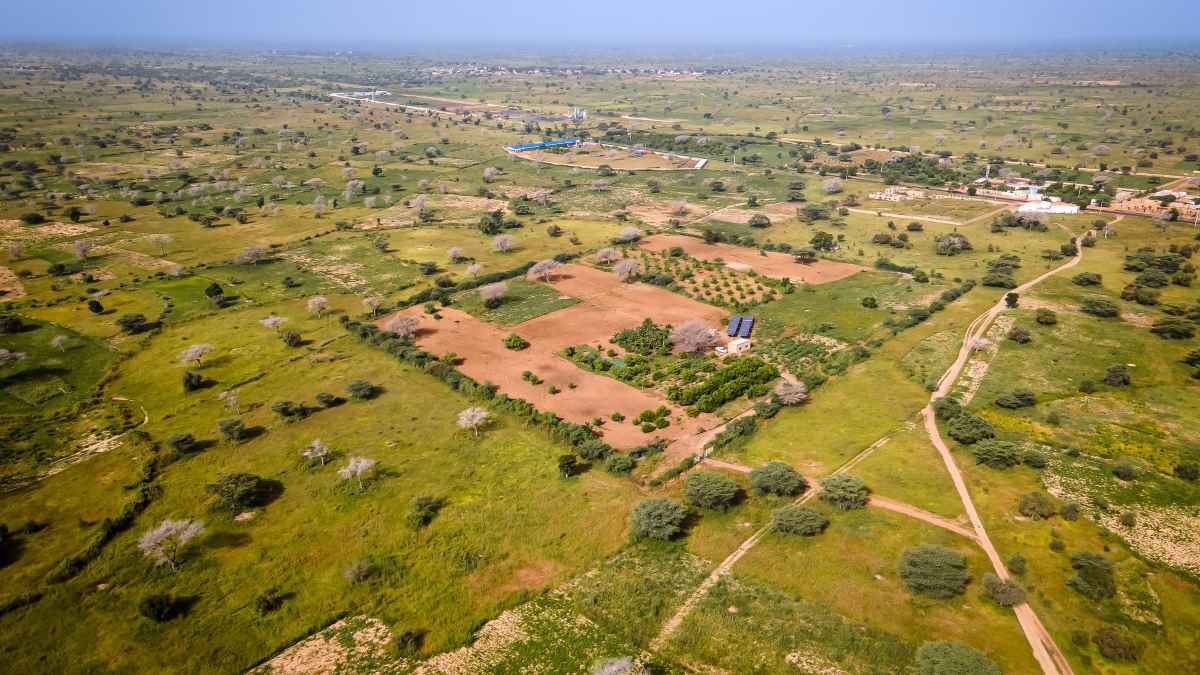
The project intervention area covers the regions of Louga, Matam and Saint-Louis, with a combined population of some 2.8 million people. It has significant agricultural, forestry, pastoral and fisheries potential and provides more than 80% of national rice production, 90% of its industrial tomato production and 50% of its onion production. With a sea coast, the River Senegal and Lake Guiers, the Saint-Louis region produces 122,000 tonnes of fish per year. It is also home to several private investments in the Senegal river valley.

During its implementation, the project will support the emergence of three agribusiness hubs through three agribusiness parks in the localities of Ogo, Bokhol and Dahra, each measuring some 130 to 150 hectares, along with 14 aggregation and services centres, all of which will facilitate the networking of value chain stakeholders.

In terms of expected outcomes, Agropole Nord will enable the processing and marketing of some 2.12 million tonnes of agricultural products from its fifth year of operation. In addition to its financial and economic impact, the project is expected to lead to the creation of 129,800 direct jobs in the agricultural, forestry, pastoral and fisheries sectors and 298,800 indirect jobs in related services.

As of 31 October 2023, the African Development Bank Group’s active portfolio in Senegal comprised 35 projects with a total commitment of 1,380 billion FCFA.

Distributed by APO Group on behalf of African Development Bank Group (AfDB).
Business

African Energy Leaders Call for Action on South-South Oil and Gas Partnerships

Published

on

African Energy Chamber

At AEW 2026, industry representatives from Africa and the Caribbean say joint ventures, enforceable local-content rules and regional financing are needed to turn petroleum resources into domestic industrial growth

CAPE TOWN, South Africa, October 17, 2026/APO Group/ –African and Caribbean energy leaders called for stronger cross-border investment, technology transfer and enforceable local-content requirements to ensure emerging oil and gas producers capture more value from their resources during the session South-South Energy Partnership: Advancing Africa’s Oil and Gas Future in 2026 at African Energy Week (AEW) 2026 in Cape Town.


Ndapwilapo Selma Shimutwikeni, CEO, RichAfrica Consultancy, said partnerships could accelerate skills development.

“From a business perspective, we need to build partnerships that encourage joint ventures between experienced countries and emerging countries like Namibia,” she said. “We need to look beyond just oil production and actually look at the entire value chain.”

Building on Shimutwikeni’s remarks, Gilbert Yevi, Lead Consultant, Grenada Hydrocarbon Technical Working Group, called for partnerships that share risks and benefits rather than simply replace one source of financing with another.

We want cooperation and a collaboration in risk sharing, skill sharing, and sharing in the benefits

“We want cooperation and a collaboration in risk sharing, skill sharing, and sharing in the benefits,” he said.

Yevi also advocated regional training centers to pool expertise and help emerging producers access established industry capabilities.

Expanding on the topic of local content, Eric Williams, Principal Consultant and President, Royal Triangle Energy Solutions, said policies must be linked to a broader national development strategy, using petroleum resources to build domestic industries rather than focusing solely on exports.

“The Trinidad model is about using the molecules to develop the country,” he said, arguing that this vision should shape negotiations with upstream investors and the terms of petroleum contracts.

Omar Farouk Ibrahim, Regional Chair for Africa, World Energy Council, said national sovereignty concerns continued to limit practical regional cooperation, despite public commitments to collaboration.

“The first question they ask is: ‘Will the industry be in my territory?’ If it’s not, why should I? And for as long as we have this mentality, believe me, this cooperation and collaboration we’re talking about will just be theory,” he said.

Across the discussion, speakers emphasized that cooperation must translate into financing, enforceable commitments and local capabilities that endure beyond individual projects.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Business

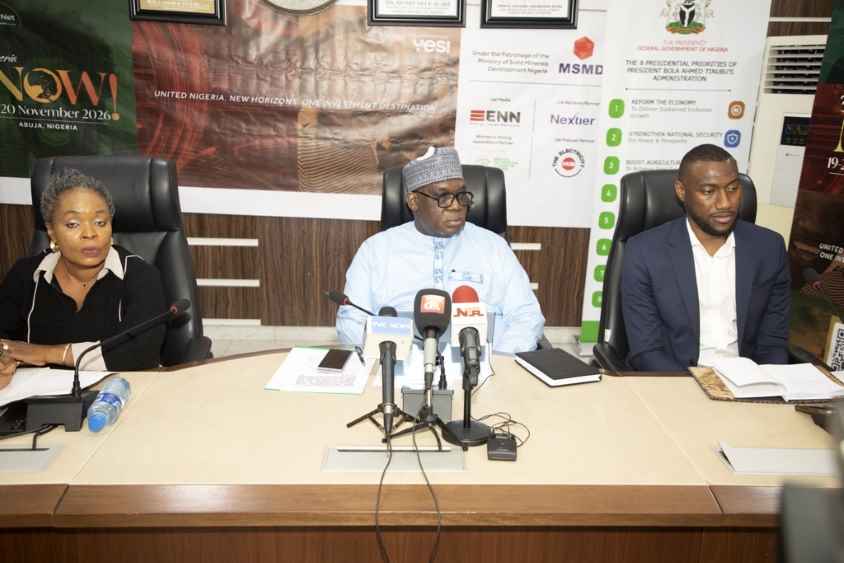
Nigeria NOW! opens its project boardrooms to global investors in Abuja

Published

on

Nigeria

With Nigeria’s annual mining revenue up more than tenfold to above N70bn, Nigeria NOW! brings global investors to Abuja on 19 and 20 November, where the Minister of Solid Minerals Development is Chief Host

First and foremost all international investors coming to Abuja should understand that Nigeria is ready and open for business

LONDON, United Kingdom, October 21, 2026/APO Group/ –Platinum group metals, gold, nickel, copper, lithium and rare earth elements lie together in one mineral province in Kaduna State, which the Minister of Solid Minerals Development announced in June as world-class and the Nigerian Geological Survey Agency has verified. The Ministry opens its doors to global investors at Nigeria NOW!, held at the Bola Ahmed Tinubu International Conference Centre in Abuja on 19 and 20 November.


Processing is following the discoveries, as lithium facilities of $600m in Nasarawa State and $200m near Abuja sit alongside a $400m rare earth processing project in Nasarawa, and mining lease applicants must now submit value-addition plans. Annual mining revenue has risen from about N6bn before the current administration to more than N70bn by the end of 2025.

The routes to export markets are moving too, as the Federal Executive Council has approved deep seaports at Bakassi and Ondo as public-private partnerships, with the Bakassi port alone valued at $2.27bn.

With a month to go, investors and developers travelling to Abuja will meet these projects at close quarters. In investor boardrooms, the Government of Nigeria will review specific projects in depth, from large-scale infrastructure to multilateral programmes such as Mission 300.

Speaking to Energy News Network in September, Tunde Arisekola, Senior Advisor, Geological and Minerals Information at the African Minerals Development Centre, who joins the minerals session on the first day, said that “first and foremost all international investors coming to Abuja should understand that Nigeria is ready and open for business”. In the same interview he described Nigeria’s economy as “stable, safe, peaceful and welcoming to all international investors”.

The programme opens with a welcome from the Chief Host, H.E. Dr Oladele Henry Alake, Minister of Solid Minerals Development, followed by sessions on how the Ministry of Power will drive capacity into Nigeria’s industrial hubs and on the policies opening the minerals sector to foreign investment, including domestic processing and value addition. The second day turns to the pipeline of transport and port infrastructure and the $1bn Domestic Green Bond, and closes with an investors’ clinic on the 2025 Tax Act.

Lagos State Government, a Nigeria NOW! partner, now regulates its own electricity market after NERC transferred oversight to the Lagos State Electricity Regulatory Commission. Hon. Biodun Ogunleye, Lagos State Commissioner for Energy and Mineral Resources, told Energy News Network that “capital follows bankable cashflows”. The state’s job, he said, is “to create both the infrastructure plan and the commercial architecture that makes that plan financeable”.

On Friday 20 November, YES! Nigeria runs alongside the main programme under the theme “Empowering Today’s Entrepreneurs, Building Tomorrow’s Industrialists”. Abuja University and Philomath University are partners, and the Youth Sustainable Development Network is Community Partner. Its opening session hands the stage to young Nigerians already at work in the sector, among them Damilola Hamid Balogun of YSDN and Emmanuel Terwase of Boost Power.

Nigeria NOW! is held under the patronage of the Minister of Solid Minerals Development, with the Lagos State Government, the Nigerian Indigenous Women in Mining & Natural Resources Organisation, Women in Mining, Nextier and The Electricity Hub as partners.

Distributed by APO Group on behalf of EnergyNet Ltd..


Continue Reading

Business

Global Islamic finance industry assets to reach US$10.5 trillion by 2030 as adoption broadens

Published

on

Global Islamic finance

The report draws on the Islamic Finance Development Indicator (IFDI), a global benchmark that assesses the development of the Islamic finance industry across 140 countries through five key areas, Financial Performance, Governance, Sustainability, Awareness, and Knowledge

For ICD, these developments reinforce the importance of ensuring that Islamic finance serves as a practical instrument for inclusive and sustainable economic transformation

KUALA LUMPUR, Malaysia, October 21, 2026/APO Group/ –LSEG, in collaboration with the Islamic Corporation for the Development of the Private Sector (ICD) (www.ICD-ps.org), the private sector arm of the Islamic Development Bank (IsDB) Group, today announced the results of the 2026 edition of the Islamic Finance Development Report at the Kuala Lumpur Islamic Finance Forum (KLIFF) in Malaysia.


Key findings of the report include:

  • The global Islamic finance industry maintained a strong growth trajectory in 2025, with total assets reaching US$6.5 trillion, up 9% year-on-year. Growth was supported by the continued expansion in Islamic banking, record sukuk issuance, strong Islamic fund performance, and new regulatory frameworks.
  • Malaysia, Saudi Arabia, the United Arab Emirates, Indonesia, and Pakistan retained their positions as the world’s most developed Islamic finance markets. These countries continued to benefit from comprehensive regulation, strong institutional development, active financial markets, and well-established knowledge ecosystems.
  • Several markets recorded notable gains in performance, including Türkiye, Tanzania, Kenya, Benin, Azerbaijan, and Uzbekistan, highlighting the growing momentum across both established and emerging Islamic finance markets.

The report also identified several structural trends that are shaping the industry’s development. Regulatory reforms and stronger market infrastructure are supporting growth beyond core markets, particularly across Africa and Central Asia. Sustainability guidelines are increasingly prioritised, although activity remains concentrated in developed markets. Digitalisation is also advancing, with FinTech, open banking, and tokenised sukuk influencing financing, issuance, and settlement while widening access to financial products. However, talent development is lagging industry expansion, emphasising the need for stronger specialist education.

Khalid Khalafalla, Acting Chief Executive Officer of ICD, said: “For ICD, these developments reinforce the importance of ensuring that Islamic finance serves as a practical instrument for inclusive and sustainable economic transformation. ICD remains committed to advancing private-sector development across its member countries through targeted financing and the promotion of Islamic financial solutions.”

Mustafa Adil, Head of Islamic Finance, LSEG, added: “Looking ahead, global Islamic finance assets are projected to exceed US$10.5 trillion by 2030, supported by continued Islamic banking expansion, growing sukuk issuance momentum, emerging-market adoption and demand for sustainable and digital financial solutions.”

The report draws on the Islamic Finance Development Indicator (IFDI), a global benchmark that assesses the development of the Islamic finance industry across 140 countries through five key areas, Financial Performance, Governance, Sustainability, Awareness, and Knowledge. It provides a holistic view of the global Islamic finance landscape, measuring progress in alignment with Islamic principles and supporting stakeholders in identifying opportunities for growth and reform.

Read full report: Link (https://apo-opa.co/3TTw9yq)

Distributed by APO Group on behalf of Islamic Corporation for the Development of the Private Sector (ICD).


Continue Reading

Trending