Connect with us

Business

Rand Merchant Bank (RMB): African Risk is not Fairly Priced – Governments Should Take Advantage (By Miranda Abraham)

Published

on

Rand Merchant Bank

African banks and investors are desperate for assets and are very comfortable assessing and understanding sub investment grade African risk

JOHANNESBURG, South Africa, October 31, 2023/APO Group/ — 

By Miranda Abraham, Head of Loan Syndications at RMB in London (www.RMB.co.za)

Yield-chasing investors have poured money into the continent but an emerging, recent challenge for Africa is that in a now higher interest rate environment, investors don’t need to come to Africa to find higher returns.

Even US treasuries are now yielding far more attractive yields than just a month ago: 3-month government bonds offer 5.32% and while 2-year bonds offer a yield above 5%. Yields have risen in part in response to Fitch’s recent downgrade of the US from AAA to AA+, echoing S&P’s move in 2011.

African bond issuers, spooked by the high-interest rate environment and refusing to issue bonds above the psychological barrier of double-digit yields for Sub-Saharan African bonds, continue to wait it out on the sidelines.

But with interest rates continuing to climb, the wait-and-see strategy is no longer looking like a sensible approach. Issuers are running out of cash and the more stable and resilient syndicated loan market – with its heavily relationship-driven pricing, is increasingly proving to be an alluring alternative to the bond market.

African governments should therefore bring forward planned borrowing before the capital shifts away, as it is already starting to do, and the cost of borrowing rises further still.

The syndicated loan market is dominated by relationship banks, who will consciously and willingly price a loan at very low yields, in order to secure a lead mandate and lock in the ancillary opportunities and revenues that come with being a core relationship bank. 

Banks do this knowing that they will also be able to persuade other relationship banks to join the deal as well. This is why syndicated loans always tend to price at a subsidized level when compared to bonds – where investors are more agnostic and definitely less loyal – focusing instead on the relative value of opportunities across the market.

However, while bond prices have skyrocketed, the loan market has hardly moved in terms of pricing. Yes, base rates are higher, resulting in higher all-in costs for borrowers, but on an all-in basis, when compared to bonds, issuing a syndicated loan is definitely the cheaper option for borrowers.

But why have African issuers managed to price debt at such attractive levels for so long?

There are three main reasons:

In order to attract their investment into Africa, pricing on these credit enhanced deals has to be highly attractive

  • Finite supply: There is a limited supply of investable assets in Africa and those banks with an African focus are eager to support their key clients and to get exposure to the African market, which is seen as having strong growth potential. 
  • Difficulties in assessing risk: It can be difficult to assess the credit risk of African borrowers. This is because there is less historical data available, and the political, legal and regulatory environment is often complex. Joining a syndicated loan or bond that has been oversubscribed and so carries the stamp of endorsement from the market can be an attractive solution to this challenge.
  • Those issuers that are active in the loan market tend to bring with them an array of other ancillary opportunities (e.g. IPO, Eurobond, and Advisory mandates), in a region where businesses that are succeeding are usually experiencing high growth.

So finite supply leads to fierce competition for these prestigious African clients and the fact that these credits are complex and difficult to understand exacerbates the problem. 

As a result of these factors, African risk is often not being priced fairly. South Africa is a good example of how African risk can be underpriced. Despite losing its investment grade rating in 2017, South African corporates and State-Owned Enterprises (SOEs) continue to price their debt like they are in Western Europe. This is because there is a limited pool of opportunities for those banks that prefer to lend in ZAR to invest in.  

Relationship pricing works for the banks because they are able to use the revenues from ancillary business to subsidize their commitment to the loan, but for regular investors (who are typically looking on an asset play basis) they can end up being short-changed. This means that investors may be taking on more risk than they realise, for a relatively low return.

However, instead of adjusting pricing upwards, the imbalance is being addressed another way – by adjusting risk.

Reducing the risk keeps pricing low and so address issuers concerns around paying double-digit yields.

Risk mitigation tools (in the form of ECA wraps, DFI guarantees or insurance wraps) are being embedded into loans and so while pricing remains low, investors improve their returns through adjusting the risk.

These type of credit risk mitigated deals, result in investment grade ratings, but with a substantial African premium. In the EUR 1bn Bank of Industry deal, BOI/AFC pays a yield of about 200bps versus an average yield of 75ps for an A3 rated credit in Europe. It is the only way for many international and European banks – who typically shy away from low BB or single B African risk – to fill their African buckets. 

These investors have a whole world of investment opportunities available to them, from AAA through to single B risk, usually across the globe, so they can pick and choose their deals.  Consequently, in order to attract their investment into Africa, pricing on these credit enhanced deals has to be highly attractive relative to other similarly opportunities globally.

However for those emerging market investors or African banks focused on Africa, their return hurdle requirements mean that the credit enhanced deals do not work for them. 

Instead, they are obliged to find African opportunities that represent real, uncovered African risk.  However, the market paralysis created by a difficult credit environment, combined with the fact that a large proportion of those deals that do come to market include some form of credit enhancement, means that the pool of deals offering pure, uncovered African risk is now much smaller.

And this is where supply and demand dynamics take over. 

African banks and investors are desperate for assets and are very comfortable assessing and understanding sub investment grade African risk. However this dynamic of fewer deals but strong investor demand has led to plentiful pent up liquidity down the credit curve.

Ironically, once African investors get over the hurdle of higher return requirements (often driven by higher cost of funding) there is such relief that pricing works from a returns perspective, that they can then end up effectively under-pricing the actual credit risk. So we end up with BB- loans paying only 450bps versus BB average bond yields of 12%.

Investors in Africa are a finite pool who know and understand African risk. They deserve to be fairly compensated for the risk they take.  

Distributed by APO Group on behalf of Rand Merchant Bank.

Business

AFRICLOUD Opens Lagos Region and Local-Currency Payments in African Markets

Published

on

The company’s third African region keeps Nigerian workloads in Nigeria, and customers from Abidjan to Nairobi can now pay in the currency they earn, without an international card
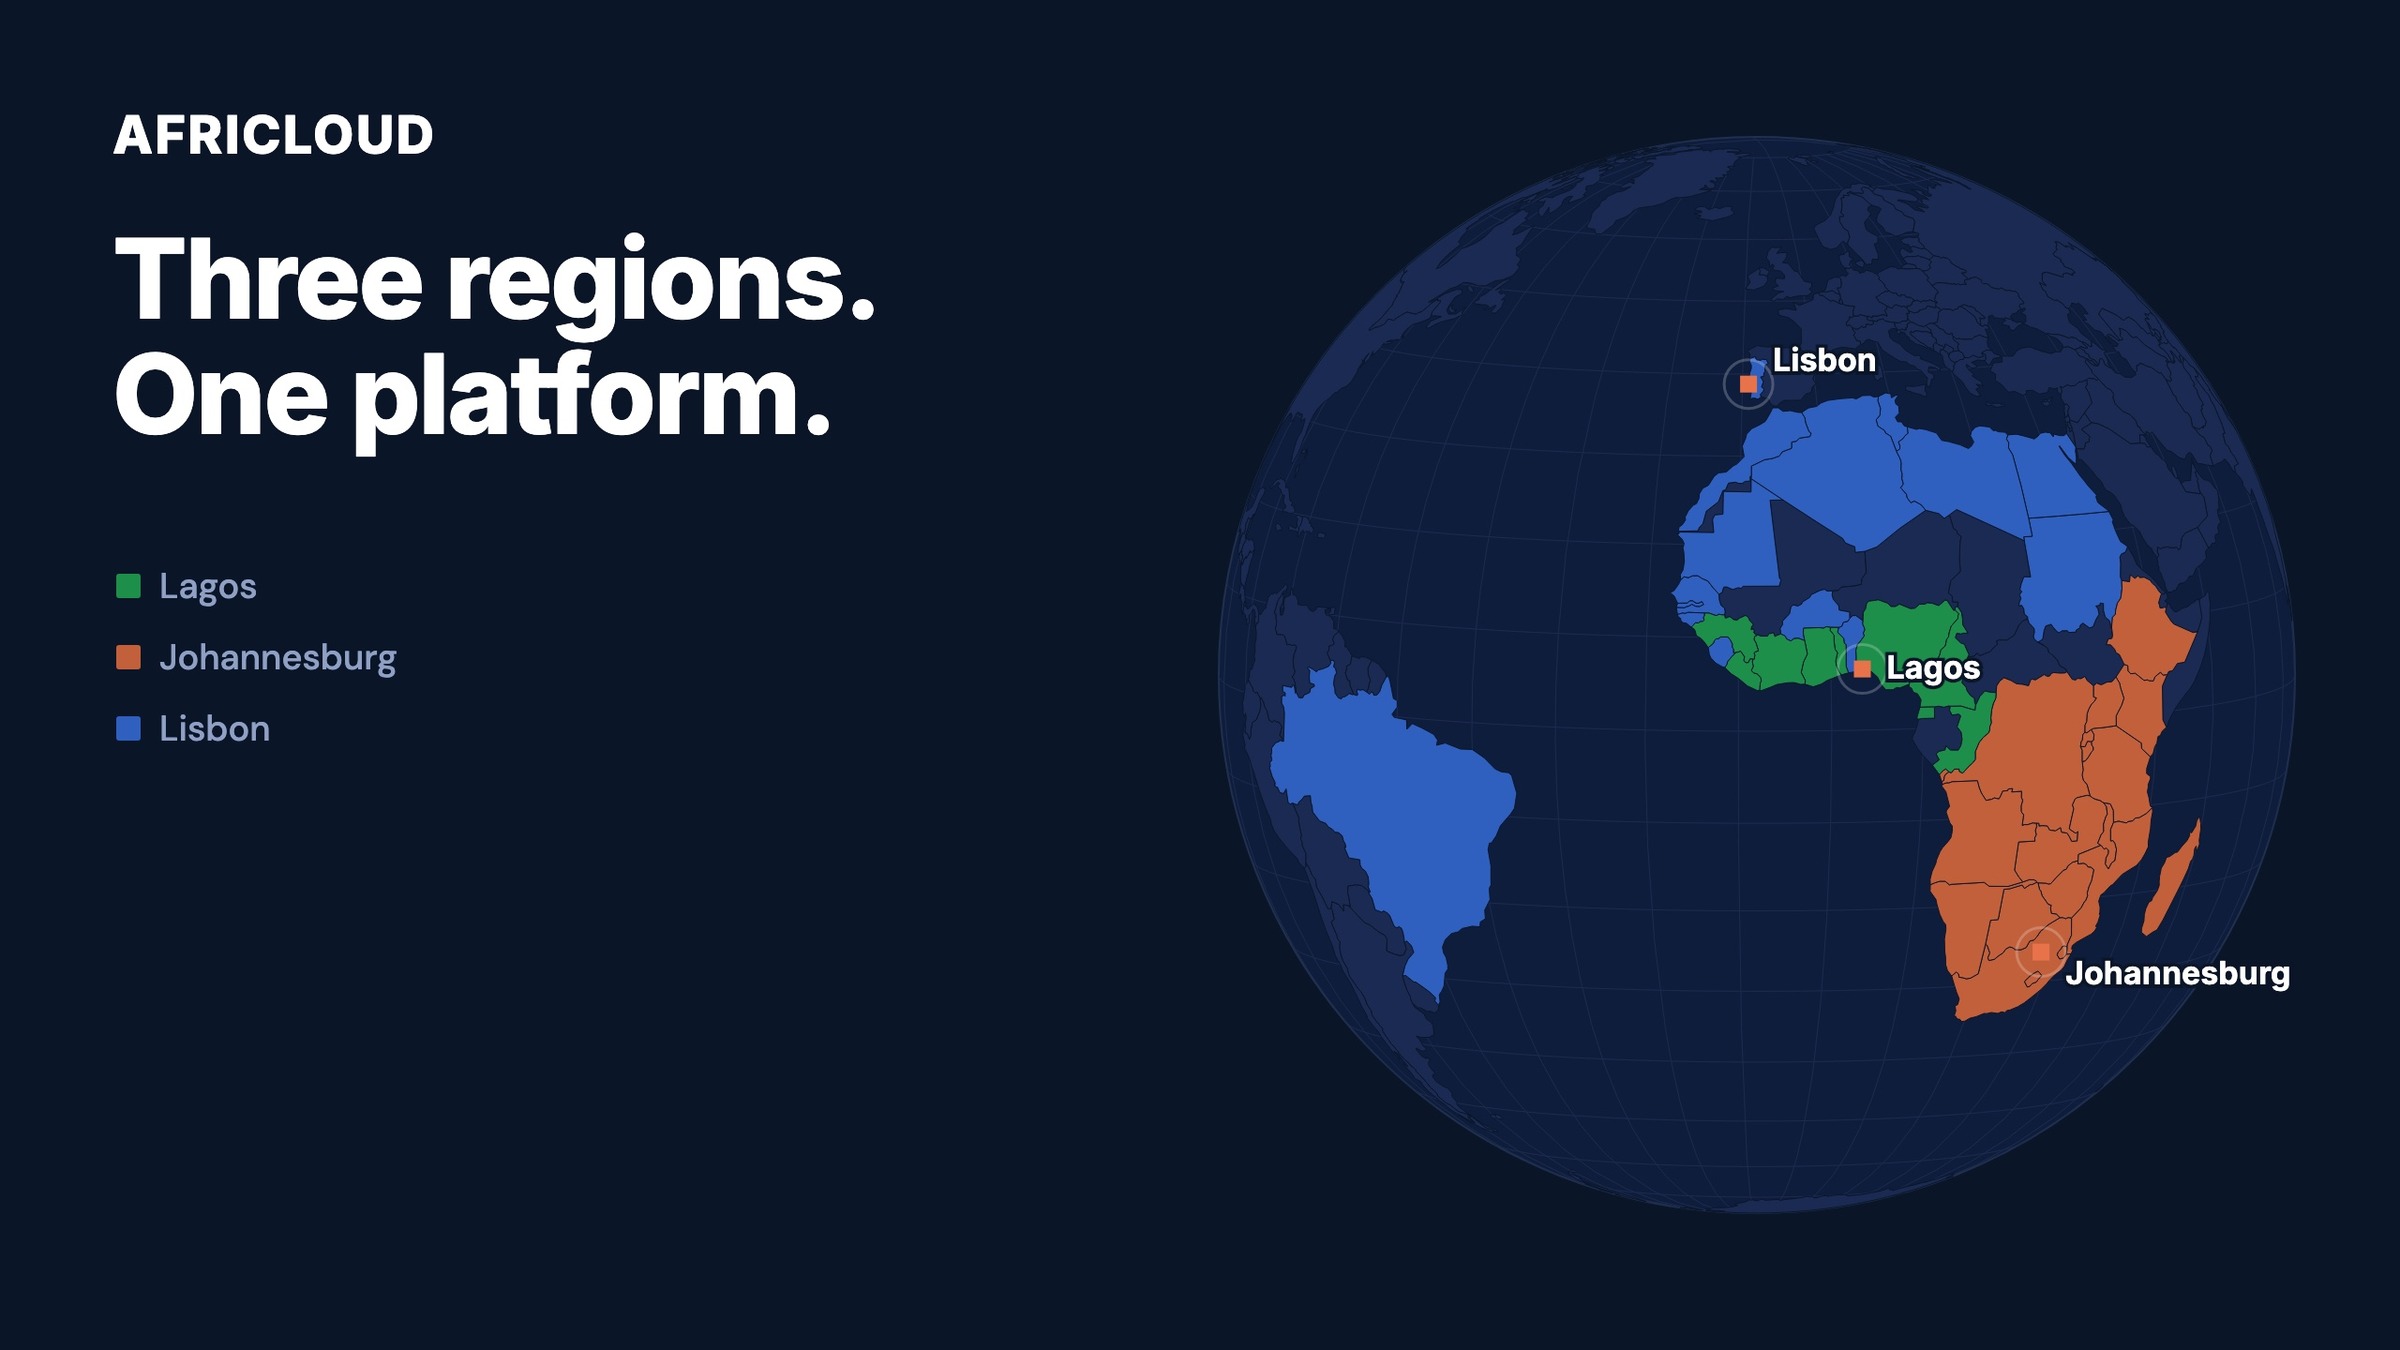
MIAMI BEACH, United States of America, September 23, 2026/APO Group/ –AFRICLOUD (https://AFRICLOUD.com), a cloud infrastructure company, has opened its third African region in Lagos and now accepts payment in local currency across West, Central, East and Southern Africa. Businesses across the continent can run servers in Nigeria, South Africa or Portugal from one account, and pay for them the way they already pay for everything else.


Download document (1): https://apo-opa.co/4Ardfz9

Download document (2): https://apo-opa.co/46FWH8Y

Buying cloud infrastructure in Africa has meant living with three compromises: traffic that leaves the continent and comes back, payment in dollars behind a card many businesses do not hold, and data sitting under somebody else’s law.

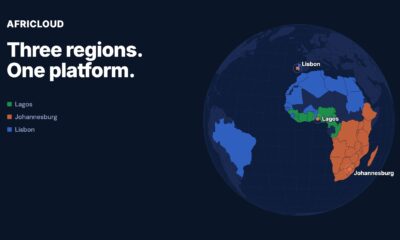
Lagos answers the first. Compute and storage for Nigerian customers stay in Nigeria, and the region also serves Accra, Abidjan, Lome, Douala and Ouagadougou. Traffic from landlocked West Africa that once reached comparable infrastructure by way of Europe now stays on terrestrial West African fibre. Johannesburg serves Southern and East Africa. Lisbon serves North Africa and Europe, and reaches Brazil over a direct subsea route. Across the three regions, AFRICLOUD’s own continent-wide measurements place 42 of the 53 African countries measured within a best-case round trip of 70 milliseconds, countries home to about 1.28 billion people.

A company in Accra or Abidjan now reaches West African infrastructure without leaving the region, and pays for it in the currency it earns

Payment answers the second. Customers across West, Central, East and Southern Africa pay in their own currency, including the naira, the cedi, the shilling and the CFA francs, by local card, bank transfer, USSD or mobile money, with no international card needed. Mobile money is live in twelve African countries, and cards, PayPal and more than 300 cryptocurrencies are accepted everywhere. The GSMA reports that 74 per cent of the world’s mobile money activity by transaction count took place in Africa in 2024.

Residency answers the third. Nigerian data runs under the Nigeria Data Protection Act, South African data under POPIA and European workloads under EU law, chosen server by server from the same dashboard.

“African businesses have been asked to choose between infrastructure that is close, infrastructure they can actually pay for, and infrastructure that keeps their data under their own law,” said Oluniyi Ajao, Founder of AFRICLOUD. “Removing that choice is the reason we built this.”

“Lagos is the piece that completes the map,” he said. “A company in Accra or Abidjan now reaches West African infrastructure without leaving the region, and pays for it in the currency it earns.”

All three regions run the same platform: AMD EPYC processors with all-NVMe storage, IPv4 and IPv6 on every server, and a new server online in about two minutes. Dedicated Servers are built to order in all three regions. Support is available around the clock by chat and email.

Cloud Servers are available now at https://AFRICLOUD.com.

Distributed by APO Group on behalf of AFRICLOUD LLC.


Continue Reading

Business

Hong Kong outlines strategies for deepening development of the Guangdong-Hong Kong-Macao Greater Bay Area and enhancing green transformation

Published

on

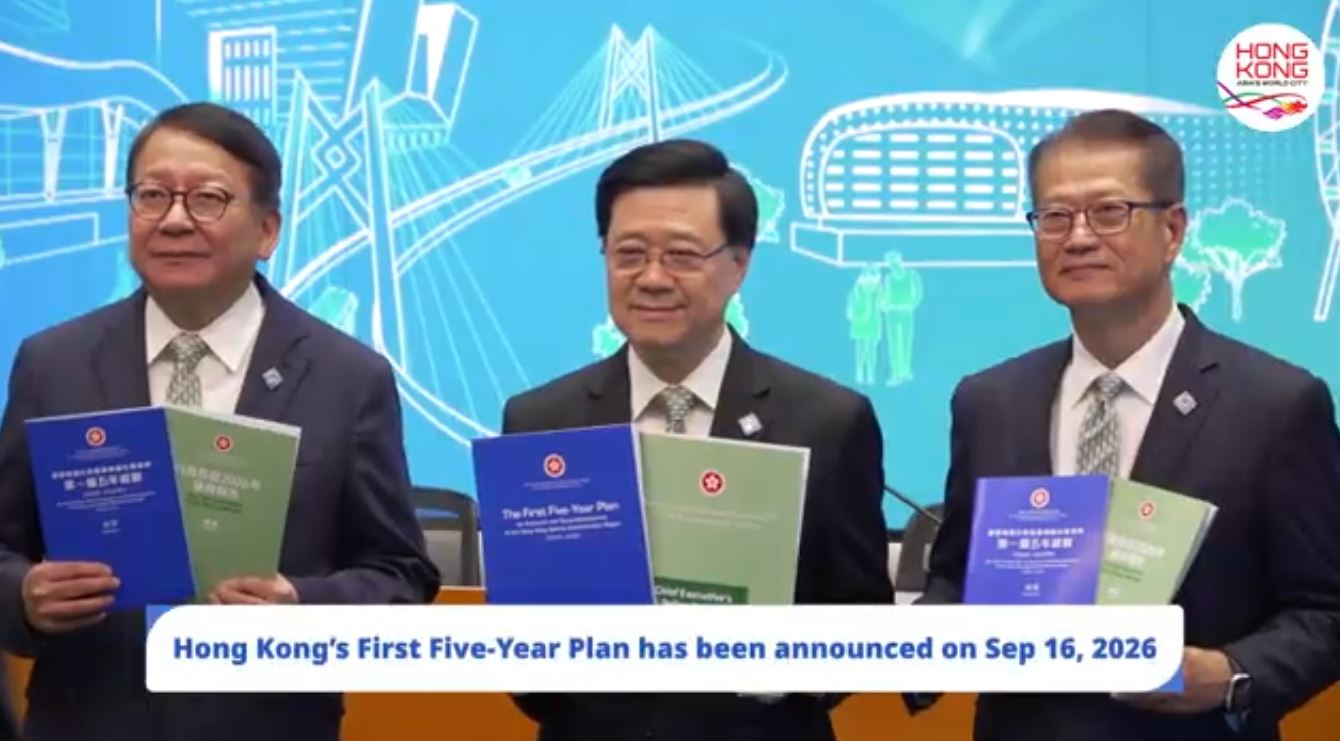
HONG KONG SAR – Media OutReach Newswire – 22 September 2026 – Hong Kong’s Chief Executive John Lee announced the First Five-Year Plan for Economic and Social Development of the Hong Kong Special Administrative Region (HKSAR) (2026-2030) and his fifth Policy Address on September 16, rolling out measures to further sharpen Hong Kong’s edge amid global competition, consolidate development of the Guangdong-Hong Kong-Macao Greater Bay Area (GBA) and promote green transformation.

Initiatives aim to support high-quality development of the GBA, align rules and mechanisms within the region, and promote cross-boundary collaboration.


“The HKSAR Government will continue its efforts in fostering synergistic development of the GBA,” said Mr Lee. “We will strengthen co‑operation in technological innovation, promote ‘hard connectivity’ in infrastructure, foster ‘soft connectivity’ by deepening the alignment of rules and mechanisms, and achieve ‘connectivity of hearts’ among residents of the three places.”

The HKSAR Government will continue to actively participate in the development of the various major co-operation platforms, including Qianhai of Shenzhen, Nansha of Guangzhou, Hengqin of Zhuhai and the Hetao Shenzhen-Hong Kong Co-operation Zone, to promote mutual benefits.

In terms of “hard connectivity” the HKSAR Government will support Nansha in its role as a high‑standard gateway for opening up, including encouraging the trade to participate in Nansha’s infrastructure development.

“To promote the co‑ordinated development of rail transit in Guangdong, Hong Kong and Macao, we are pressing ahead with the Northern Link Project and the Hong Kong‑Shenzhen Western Rail Link (Hung Shui Kiu‑Qianhai), with target commissioning in 2034 and 2035 respectively, to fully connect the rail transit networks of Hong Kong and Shenzhen,” Mr Lee said.

Regarding “soft connectivity”, Mr Lee said the HKSAR Government will set up a Task Force to explore ways to advance the alignment of rules and mechanisms within the GBA.

To achieve “Connectivity of Hearts” among residents across the GBA, Hong Kong will strengthen co-operation between its higher education institutions and those in other GBA cities by establishing cross‑disciplinary partnerships, facilitating scientific research, knowledge transfer, and commercialisation, with a view to promoting high‑level research.

Hong Kong’s Secretary for Constitutional and Mainland Affairs, Janice Tse, noted that the First Five-Year Plan clearly states that Hong Kong will participate in the development of the GBA into an international first‑class bay area and a world‑class city cluster with global influence.

“Hong Kong will forge closer alignment and synergy with the nine GBA cities in Guangdong Province and Macao, making full use of our respective advantages to jointly promote the high-quality development of the GBA,” Miss Tse said.

To foster financial development in the GBA, Hong Kong will continue to capitalise on institutional innovation, financial infrastructure upgrading and enhanced regulatory alignment to encourage the orderly flow of financial elements among GBA cities.

The Hong Kong Exchanges and Clearing Limited’s Core Climate, in collaboration with the Guangzhou Power Exchange Centre, is working towards the pilot trading of national renewable‑energy, green electricity certificates in Hong Kong in 2026.

“On connecting the Chinese Mainland and the world, the HKSAR Government will continue to support green technology development through the HK$400 million (aboutUS$51 million) Green Tech Fund, leveraging Hong Kong’s function as a springboard for green technology and assisting national green technologies and products in going global,” said Hong Kong’sSecretary for Environment and Ecology, Tse Chin-wan. “On the development of hydrogen energy, we have participated in drafting national hydrogen energy standards with a view to helping these standards align with international practice.”

To meet the country’s “dual carbon” targets and fulfil Hong Kong’s commitment to achieving carbon neutrality before 2050, the HKSAR Government steered the establishment of a production base for sustainable aviation fuel (SAF) in Dongguan, leveraging the leading position of Hong Kong enterprises in the international SAF industry.

“By combining technology strengths with industrial foundation, Hong Kong and Guangdong will jointly develop a globally influential green industry,” Mr Lee said.

The HKSAR Government will take forward the construction of an SAF blending facility in Hong Kong to build an end‑to‑end SAF value chain and reduce logistics costs to make SAF prices more competitive. The target is to achieve an SAF consumption ratio of 1% to 3% for flights departing from Hong Kong International Airport in 2030.

Hong Kong’s Five-Year Plan promotes the integrated development of culture, sports, and tourism, to develop the GBA into a cultured bay area.

Under the strategic framework of the Agreement on Strengthening of Sports Cooperation and Promotion of Integrated Development, Hong Kong will deepen co-operation, and strive to co‑organise important regional and international single‑sport events. It will also strengthen cultural exchanges, pass on Cantonese opera and the characteristics of Lingnan culture, and promote the sales and cross‑boundary exhibition of Hong Kong publications.


Continue Reading

Business

Alamein Africa Forum to bring together key political and business leaders

Published

on

The forum is to become the continent’s premier gathering where political power meets entrepreneurial prowess, bridging the established engines of African growth with the new sectors defining its future

CAIRO, Egypt, September 22, 2026/APO Group/ –The inaugural Alamein Africa Forum (https://AlameinForum.com/) will take place from October 2-4 in the historic city of Alamein on Egypt’s Mediterranean coast in parallel with the 2026 African Union mid-year summit.

Established in response to a mandate from the African Union, which called for a permanent African Business Forum to convene biennially in Egypt, the inaugural edition will bring together Heads of State and official delegations as well as some key actors in business and finance.


The forum is to become the continent’s premier gathering where political power meets entrepreneurial prowess, bridging the established engines of African growth with the new sectors defining its future.

The Alamein Africa Forum will serve as a pan-African platform bringing together the private sector, investment and financial institutions

The Presidents of Algeria, Angola, Burundi, Chad, Equatorial Guinea, Ghana, Libya, Senegal, Somalia, and South Africa are expected in Alamein as well as President Al Sisi, President of the Arab Republic of Egypt who is the host of this year’s AU Mid-Year Summit. Business leaders from across the continent have confirmed their participation including Ralph Mupita, MTN; Idrissa Nassa, Coris Bank; Mohamed El Ketani, Attijariwafa Bank; Hichem Eloumi, Groupe Shakira; Wale Tinubu, Oando; and many more. Aliko Dangote, Africa’s biggest industrialist is also expected to attend, with the organisers hoping to set up a Business Advisory Council to help advance private sector priorities and investment throughout the continent.

Bringing together leaders in politics, business and policy from across the continent, the Alamein Africa Forum will provide a unique opportunity to shape Africa’s growth agenda by aligning policy and investment priorities, mobilising partnerships for implementation and strengthening financing and investment pathways. The private sector must become an integral part of Agenda 2063, the AU’s strategic 50 year masterplan to transform the continent.

Co-organised by the Government of Egypt, Afreximbank, the African Union and AUDA-NEPAD, the Forum brings together Africa’s most influential decision-makers in an unprecedented alliance of public and private sector leadership.

Speaking on the imperative of the summit at a joint press conference by the government of Egypt and Afreximbank on Thursday, September 17 2026, Dr. Badr Abdelatty, Minister of Foreign Affairs, International Cooperation, and Expatriates Abroad said (https://apo-opa.co/4ygiQag): “The Alamein Africa Forum will serve as a pan-African platform bringing together the private sector, investment and financial institutions, and representatives of various productive and service sectors, to strengthen direct links between companies and markets and decision making at the highest level.”

Continuing, he noted that the Alamein Africa Forum is part of a series of high-level African events that Egypt will host in early October, stressing that holding the forum reflects Egypt’s commitment to advancing continental economic cooperation

In his own comments, Dr. George Elombi, President and Chairman of the Board of Directors of Afreximbank described (https://apo-opa.co/4ygiQag) the Alamein Africa Forum as a pan-African platform for promoting intra-African trade and investment and connecting the business community and financial institutions with priority projects and investment opportunities in the continent.

Distributed by APO Group on behalf of Alamein Africa Forum.


Continue Reading

Trending

Exit mobile version