Connect with us

Business

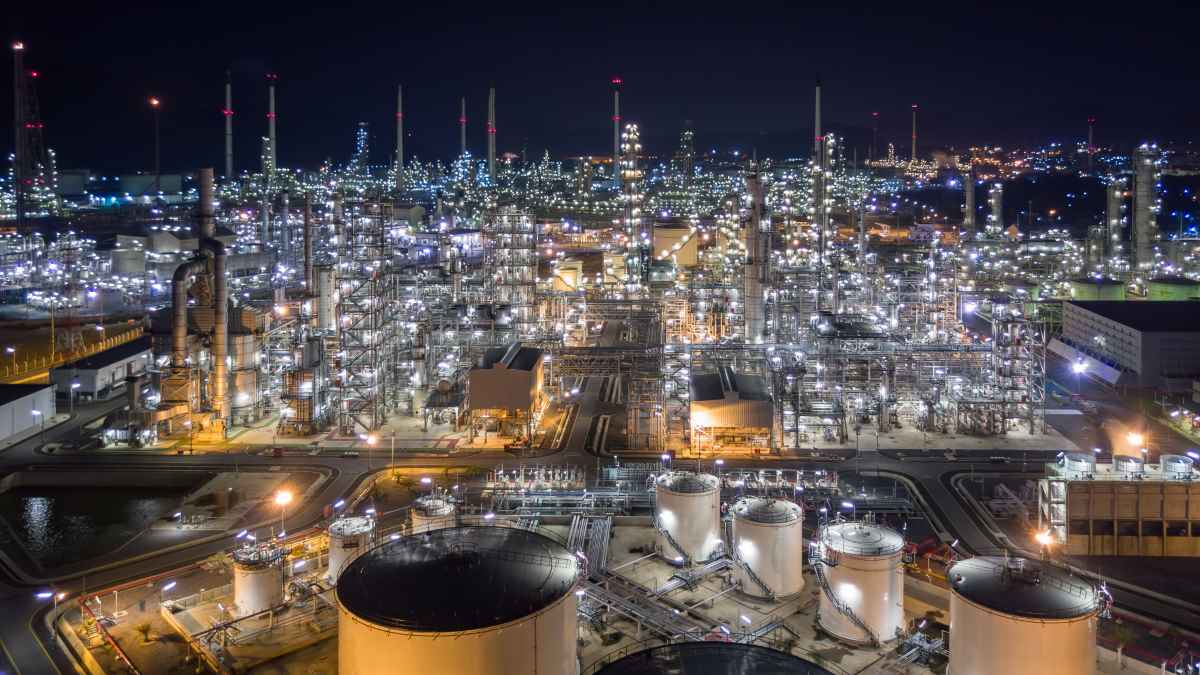
The Invest in African Energy (IAE) Forum to Connect African Energy Projects with Saudi, United Arab Emirates (UAE) Buyers

Published

on

Invest in African Energy

Gulf countries have shown rising interest in helping Africa to develop its oil and gas resources and build much-needed infrastructure

PARIS, France, February 22, 2024/APO Group/ — 

Over the past twelve months, the Middle East’s oil and gas heavyweights – Saudi Arabia, the United Arab Emirates (UAE) and Qatar – have accelerated their involvement across Africa’s energy value chain. Beginning with diplomatic visits turning into tangible cooperation agreements and planned investment campaigns, Gulf countries have cemented their interest in competing for Africa’s untapped hydrocarbon resources, which make up around 13% of natural gas reserves and 7% of oil reserves globally.

The Invest in African Energy (IAE) 2024 forum – taking place in Paris on May 14-15 – will bring together Africa’s top energy projects to pitch to global buyers for partnership and investment. The forum serves as a pivotal platform for Gulf energy companies and developers to access the latest data and project specifications directly from African energy ministers and authorities, with a view to unlocking mutually beneficial partnerships and new energy finance.    

Saudi Arabia

With plans to invest up to $25 billion in Africa by 2030 through its Public Investment Fund, Saudi Arabia is positioning itself as a long-term partner to the continent and leading integrated developments across Africa’s oil and gas value chain. Over 50 projects worth more than $500 million were signed between Saudi Arabia and African nations in November 2023, with investments directed primarily to energy, mining and infrastructure sectors. Deals included energy cooperation agreements with Senegal, Chad, Rwanda and Ethiopia, as well as a financing agreement with Mozambique for the construction of public infrastructure.

In Nigeria, Saudi Arabia has pledged to invest in the revitalization of Nigeria’s oil refineries and provide financial support to strengthen downstream capacity. In January, the two countries launched the National Human Capacity Training Program for the Adoption of Liquefied Petroleum Gas (LPG), which is set to lead to the joint-development of micro-distribution points for LPG through Nigeria’s Edo State. Meanwhile, the Kingdom is engaging in talks with South Africa to construct a refinery and alleviate domestic fuel shortages.

UAE

While Saudi Arabia may be leading diversified investment across Africa, the UAE is not far behind. Last December, the UAE signed an agreement with Morocco for the development of the Africa-Atlantic gas pipeline, transporting Nigerian gas to North Africa, then on to Europe. Through its Abu Dhabi sovereign wealth fund, the country will help mobilize financing for the pipeline, which could also connect emerging gas players like Senegal and Mauritania to new markets. Seeking expansion into Africa’s gas industry, Abu Dhabi National Oil Company is said to be in discussions to acquire Galp’s 10% interest in Mozambique’s Rovuma LNG project, set to monetize three gas reservoirs in the Area 4 block of the Rovuma Basin to produce 18 million tons of LNG per year.

The UAE’s growing role on the continent also transcends direct investments, enabling African countries to tap into international financial markets. Positioned as a strategic trade center within easy reach of the Middle East, Asia, Europe and Africa, Dubai is well-connected to both global sources of capital and emerging markets that are seeking investment.

Qatar

Qatar is also ramping up its activities on the continent through upstream exploration. In April 2023, state-owned QatarEnergy acquired a 40% interest in the offshore Block C-10 in Mauritania – home to the Walata, Banda and Tevet oil discoveries – in partnership with Shell and Mauritania’s national oil company SMH. With over 28.3 billion cubic meters of proven gas reserves, Mauritania could become the third-largest gas exporter in Africa, following Nigeria and Algeria. The acquisition not only affirms the prospectivity of Mauritania’s offshore oil and gas acreage, but also Qatar’s interest in expanding its exploration footprint on the continent.

QatarEnergy has been playing an active role in the continent’s latest hydrocarbon discoveries – notably, offshore Namibia, where the company holds stakes in three exploration licenses. Its PEL 39 – in which it carries a 45% interest, in partnership with Shell (45%) and the National Petroleum Corporation of Namibia (10%) – has yielded four consecutive discoveries between February 2022 and July 2023. These discoveries – Graff-1, La Rona-1, Jonker-1X and Lesedi-1X – are now transforming Namibia into one of the foremost hydrocarbon markets on the continent, with further testing and appraisal work currently underway.

Distributed by APO Group on behalf of Energy Capital & Power.

Business

African Energy Week (AEW) 2026 Technical Sessions Put Technology Behind Africa’s Next Energy Projects in Focus

Published

on

Day 2 technical sessions at African Energy Week 2026 will examine frontier exploration, major gas developments, project economics and the technologies supporting Africa’s expanding oil, gas and LNG sectors

CAPE TOWN, South Africa, September 22, 2026/APO Group/ –African Energy Week (AEW) 2026’s Day 2 Technical Stages will put the technology and technical expertise behind Africa’s next wave of energy projects in focus, with sessions covering subsurface interpretation, deepwater exploration, gas development, project economics, digitalization, offshore operations and infrastructure.


The program will unfold across two exhibition-hall stages, with the Drill Room focusing on practical applications across exploration, gas development, offshore operations and LNG, while the Innovation Hub will examine frontier exploration, energy markets, digital technologies and infrastructure. Together, the sessions connect project-level technologies with the wider investment and development challenges facing Africa’s energy industry.

The day opens with GeoEnergy Petroleum Director Maged Fahim, who will examine how legacy and newly acquired subsurface datasets can be integrated with modern technologies to identify additional upstream opportunities. TGS Principal Exploration Advisor Felicia Winter will then focus on Angola’s deepwater basins, examining how modern seismic acquisition and imaging can be used to reinterpret existing data and evaluate frontier plays.

The discussions come as Angola seeks to build on renewed offshore activity. TotalEnergies announced in September that it plans to invest $10 billion in Angola over the next five years, including in exploration, while advancing its $6 billion Kaminho deepwater development.

Gas development will take center stage through two presentations by TotalEnergies. Alexandre Depiesse, GPI Venus, will address appraisal strategies and commercial viability for Orange Basin discoveries, while Mozambique LNG Operations and Project Director Nicolas Cambefort will examine development and optimisation of the Rovuma Basin gas resources. Mozambique LNG, a 13.1-million-ton-per-year project in Area 1 led by TotalEnergies, resumed activities in January 2026 following the lifting of force majeure, putting development of Mozambique’s major offshore gas resources back into focus.

AEW 2026 reflects the practical challenges facing Africa’s energy industry as projects move from resource potential toward development and production

The Republic of Congo National Showcase will provide another perspective on Africa’s expanding LNG industry. The country’s Congo LNG project reached a new stage in February 2026 with the start of commercial production from its second phase. The addition of the Nguya FLNG unit brought total liquefaction capacity to 3 million tons per year, expanding Congo’s ability to monetize its offshore gas resources.

The program will then broaden from individual projects to the continent-wide investment outlook with the launch of The State of African Energy 2027. AEC Senior Vice President Verner Ayukegba and S&P Global Energy Executive Director Max Pietzsch will present the outlook, covering upstream oil and gas, LNG, downstream markets, power, renewables and critical minerals against changing demand, trade flows and energy security requirements.

Project decision-making will remain under examination as S&P Global Energy Technical Research Analyst Tasnika Goorhoo presents “From Limited Data to Better Decisions: How Benchmarking Strengthens Upstream Project Outcomes.” The session will examine how comparative project data can help operators assess performance, costs and development outcomes.

NOV Vice President Mats Anderson will address offshore optimization through high-speed downhole connectivity and real-time distributed measurements, examining how faster access to downhole information can improve operational visibility and decision-making.

Infrastructure will also feature prominently, with Kenyon International West Africa CEO Victor Ekpenyong examining asset integrity and pipeline infrastructure through the company’s CACTUS and FlexSteel technologies. Honeywell Technologies Africa will close the technology-focused sessions with its end-to-end LNG offering, while SLB, InSwitch, the Petroleum Directorate of Sierra Leone and PETROSEN will bring additional perspectives on technology, digitalization and energy services.

“AEW 2026 reflects the practical challenges facing Africa’s energy industry as projects move from resource potential toward development and production,” said NJ Ayuk, Executive Chairman of the AEC. “From subsurface interpretation and deepwater exploration to LNG development, project benchmarking, digitalization and infrastructure, these technical sessions highlight the expertise and technologies needed to develop Africa’s resources efficiently and create lasting value across the energy value chain.”

AEW 2026 takes place from October 12–16 in Cape Town, bringing together governments, investors, operators and technology providers to discuss investment, project development and the future of Africa’s energy sector.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Business

Rising power costs put energy strategy at the centre of industrial competitiveness

Published

on

C&I Energy + Storage Summit Johannesburg to focus on the procurement, cost and investment decisions facing South Africa’s large energy users

JOHANNESBURG, South Africa, September 22, 2026/APO Group/ –The cost of electricity is no longer only an energy issue for South African businesses. It is increasingly a question of competitiveness, investment and long-term operational resilience.

Recent figures show the pressure on large power users. Business Day reported on 7 September that South Africa’s mining and industrial majors paid Eskom R115 billion for electricity in the 2025/26 financial year. According to Eskom’s annual report, industrial electricity demand fell by more than 22% over the same period as high power costs weighed on energy-intensive operations.


At the same time, major businesses are moving to alternative supply. Reuters reported on 26 August that South African mining companies are accelerating investment in renewable energy to cut costs, diversify supply and meet decarbonisation targets.

For commercial and industrial energy users, the question is no longer simply how to secure power. It is how to buy it, what to invest in, and which energy strategy makes the strongest commercial sense.

Energy procurement is becoming more complex

Businesses are now weighing several procurement options at once. Should they sign a long-term PPA? Buy through an electricity trader? Wheel renewable power across the grid? Invest in behind-the-meter generation? Add battery storage? Each option carries different implications for cost, risk, contracting and long-term flexibility.

These decisions will take centre stage at the C&I Energy + Storage Summit Johannesburg, taking place on 28–29 October 2026 at The Maslow Hotel, Sandton. The programme is built around the practical challenges facing energy buyers today, with a focus on real projects, commercial models and implementation rather than technology in isolation.

A programme built around the buyer’s decisions

The summit closes with the C&I Decision Clinic: Ask the Experts, a masterclass where attendees submit real project challenges in advance and receive practical, anonymised responses from experts. Questions on the table include whether to build onsite PV or sign a wheeled PPA, how much battery storage makes commercial sense, what a bankable project preparation pack should contain, and what financiers require before term sheet stage.

It follows The C&I Energy Playbook: Five decisions business leaders need to make now, a closing panel in which the moderators of key summit sessions distil the programme into the priorities C&I businesses should act on.

Other sessions address the questions buyers are asking now:

  • Energy storage beyond backup power: unlocking commercial value examines peak shaving, demand charge management, energy arbitrage and hybrid PV-plus-storage business models, along with the operational realities of dispatch, degradation and warranties.
  • Making public-private engagement work for you unpacks how wheeling agreements are structured in practice, where interface risks arise, and how businesses can engage utilities and municipalities early.
  • Reducing energy costs without building new generation is a case-study-led workshop on energy efficiency, operational optimisation, demand response and digital energy management.
  • Projects Spotlight gives energy users the floor to share the strategies they have implemented, the lessons learned and the outcomes achieved.

The programme opens with the keynote panel Threats and opportunities in South Africa’s industrial future, bringing together policymakers, industrial leaders, financiers, and energy and water experts.

Bringing energy buyers into the conversation

The summit’s Hosted Buyer Programme is designed for qualified end-user energy buyers across sectors including mining, manufacturing, property, agriculture and other energy-intensive industries. Hosted buyers take part in the full programme and receive curated engagement with solution providers across energy procurement, storage deployment and project development.

Four events, one venue

The summit is co-located with the EIUG Conference, Water Security Africa and the Data Centre Summit, bringing the energy, water and digital infrastructure communities together in Sandton. It is brought to you by Enlit Africa, with ESI Africa as host media, and is accredited by the SAIEE.

Qualified commercial and industrial energy users can apply for the Hosted Buyer Programme at https://apo-opa.co/4yPnXOg, and bring their project questions to the Decision Clinic.

Full programme: https://apo-opa.co/4xK2ANv


Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Events

Beyond the carbon credit: Who sets the terms for Africa’s carbon markets?

Published

on

From project ownership and verification to pricing and benefit-sharing, CMAS 2026 will bring African market leaders and global decision-makers together to examine who creates and captures value

KIGALI, Rwanda, September 22, 2026/APO Group/ –A carbon credit may be traded as a single unit, but its value is shaped long before it reaches a buyer. Decisions about project ownership, finance, data, verification and benefit-sharing determine who participates, who carries the risk and who ultimately benefits. As new regulations and international partnerships expand market access, these questions are becoming increasingly important across Africa.


They will be central to the Carbon Markets Africa Summit (CMAS) 2026, taking place from 13 to 15 October at the Kigali Convention Centre in Rwanda. The summit will convene African governments, project developers, investors, buyers and technical experts involved in decisions across the carbon-market value chain.

Countries are approaching these decisions from different regulatory, economic and environmental positions. While recent developments in East Africa demonstrate growing market activity, questions concerning international requirements, technical capacity, investment and benefit-sharing are relevant across Africa.

Ousmane Fall SARR, Coordinator of the West African Alliance on Carbon Markets and Climate Finance, says:

“African countries are developing carbon markets from different starting points. Stronger African expertise and regional cooperation will be important if the continent is to contribute to the standards and market practices that determine how its projects compete, attract investment and create value.”

Against this continental backdrop, East Africa provides a timely example of how the market is developing. In January 2026, Rwanda and Singapore invited applications for carbon-credit projects under their bilateral Implementation Agreement, aligned with Article 6 of the Paris Agreement. Credits from authorised projects may be used by eligible Singapore-based carbon tax-liable companies to offset up to 5% of their taxable emissions, subject to both governments’ requirements.

African countries are developing carbon markets from different starting points

Across the continent, carbon market frameworks are rapidly taking shape. Kenya and Uganda are strengthening regulatory oversight, regional partnerships are helping governments build market capacity and infrastructure, and South Africa is advancing reforms to modernise its carbon-credit ecosystem and attract investment. Together, these developments are bringing greater focus to questions of authorisation, project ownership, verification, pricing and access to international buyers, while also raising expectations that carbon finance should deliver sustainable economic and development value beyond the credit itself.

Emmanuelle Nicholls, Portfolio Director for CMAS, says:

“A carbon credit may be the final product, but behind it are decisions about ownership, data, risk, pricing and who ultimately benefits. The conversations in Kigali will examine what credible participation looks like across the full carbon-market value chain.”

These decisions have consequences beyond individual transactions. Carbon finance is increasingly connected to conservation, agriculture, soil restoration, food security, clean energy and waste management. Its success will therefore also be judged by whether projects produce credible environmental outcomes and lasting benefits for African economies and communities.

A practical example comes from the Chinko Conservation Area in the Central African Republic, where revenue from the Chinko Carbon Project is channelled through a community fund that supports locally selected initiatives, including the expansion of a medical centre in Agoumar. At CMAS 2026, African Parks and Welthungerhilfe, both Bronze Sponsors, will share perspectives on how carbon finance can support conservation, climate resilience, food systems and community development, while highlighting broader questions around project governance, impact and the distribution of value.

From project-level impact to market-wide structures, these questions will underpin discussions at CMAS 2026. The programme will address government authorisation, buyer requirements, pricing and offtake, investment risk, early-stage finance, registries and African measurement, reporting and verification capacity. It will connect the question of who sets the terms with the practical requirements for building credible, investment-ready projects and transactions.

CMAS 2026 is hosted by the Ministry of Environment of Rwanda, with UNDP and the African Development Bank as host organisations, the Development Bank of Southern Africa as host partner and AUDA-NEPAD as strategic institutional partner.

Taking place ahead of COP31, CMAS will focus attention on the decisions behind every carbon credit and what they mean for African governments, projects, investors and communities.

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Trending

Exit mobile version