CAPE TOWN, South Africa, July 30, 2026/APO Group/ —
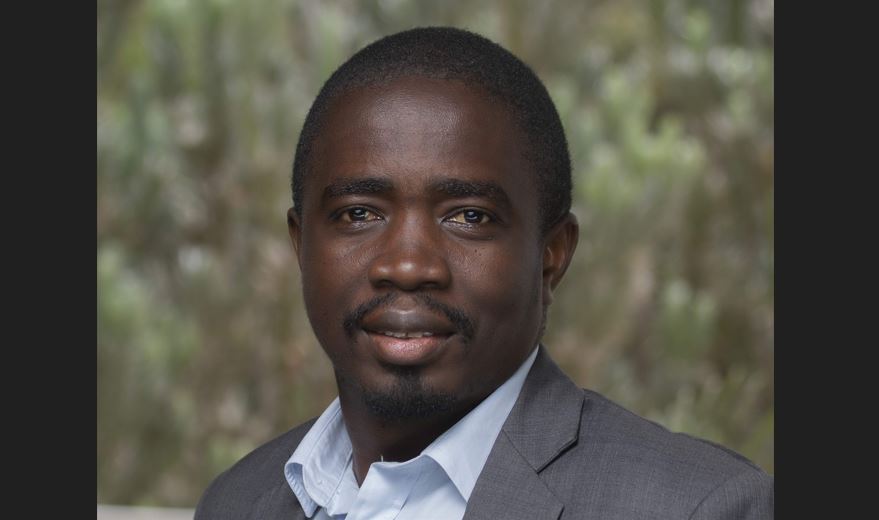
Exclusive interview with Kevin Munjal, Director, Development Impact at FSD Africa, which recently published a report on “Unlocking Africa’s Green Transition: Opportunities Towards a Green and Inclusive Workforce (https://apo-opa.co/4yMIbJt)” in partnership with Shell Foundation. It contains highly relevant insights for stakeholders working on Africa’s green transition and related human capital challenges.
Interview Summary:
Kevin Munjal, Director of Development Impact at FSD Africa, highlights the potential for up to 84.5 million green jobs in Africa by 2050 if capital flows to service-led value chains, regulations are enforced, and skills systems modernised. He stresses vocational training models with guaranteed income pathways, innovative financing that embeds workforce development into green infrastructure, and mobile-based social protection for informal workers.
Gender equity requires targeted interventions across both formal and informal economies. Clean cooking and waste recycling are identified as transformative sectors, while national strategies must reflect distinct labour market structures in Nigeria, South Africa and Kenya.
Let’s start with some background on you and the work that you do for FSD Africa. Where in Africa are you active?
My name is Kevin Munjal, I’m the Director of Development Impact at FSD Africa. FSD Africa is a specialist development agency deploying financial and non-financial instruments to strengthen Africa’s financial sector to enable the continent to mobilise sustainable capital at scale for financing of its development needs. We currently have a presence in over 30 countries.
As Director of Development Impact, I oversee the body of work that helps FSD Africa understand the effectiveness of its financial sector development strategies. Together with my team, we help craft and test hypotheses, generating data and insights that inform stronger programming.
I also oversee a growing portfolio of work on green skills and jobs, advocating for climate financing strategies that enable a just green transition in Africa.
The recently published FSD Africa report projects up to 84.5 million green jobs by 2050. What policy choices are most critical to ensure Africa reaches the high scenario outcome rather than falling short?
The gap between the low and high scenarios, 18 million jobs by 2050, comes down to three things: where capital is directed, whether regulations are enforced, and whether skills systems keep pace with deployment.
On capital, the high scenario requires finance to flow toward service-led value chains like clean cooking, solar home systems, waste recycling, e-mobility, rather than concentrating in utility-scale infrastructure. These service chains generate more jobs per dollar and reach more people.
On regulation, the gap between policy intent and market reality is enormous. Thirteen African countries have published e-mobility strategies, but very few have operational enforcement frameworks. Clean cooking targets appear in only 45% of African NDCs.
On skills, the training systems that exist are largely calibrated to legacy technologies. There are no national training programmes for IoT-enabled remote operations, battery management system governance, or carbon measurement and verification in any of the three countries we studied.
How can African governments and industry rapidly scale vocational training and skills systems to meet demand?
Africa’s renewable energy workforce is around 324,000 people—just 2% of the global total—despite the continent holding 60% of the world’s best solar resources. That gap cannot be closed through the formal TVET system alone, which is too slow to reform and too geographically fixed to reach the workers who need it most.
The most effective approaches we’ve seen share a common design principle: train for a specific job with a guaranteed income pathway. The Rural Electrification Agency’s NextGen model in Nigeria—bootcamp training paired with a nine-month paid internship—is a strong example. South Africa’s Grootbos Green Futures programme places 90% of its trainees into roles in the local restoration economy.
Beyond individual programmes, three instruments can scale quickly without new legislation. Recognition of prior learning, embedding green skills modules into existing qualifications rather than creating standalone credentials, and making industrial apprenticeships paid, which has been shown to dramatically improve female retention.
Less than 1% of climate finance currently goes to skills development. What innovative financing mechanisms could redirect capital towards workforce training?
Less than 1% of climate finance currently goes to skills development. While “Jobs created” is the standard metric for investors, it tells you nothing about whether those jobs are decent, skilled, or sustainable.
The first shift needed is to embed workforce development criteria directly into green infrastructure financing. If a DFI is deploying capital into a solar project, a defined share of that deployment should be earmarked for training. Gender inclusion criteria should also be part of the deal terms.
To move beyond grants, need to identify how the underlying assets of a green investment can innovatively finance the skilling of workers. For instance, can a portion of the carbon revenue generated by a green investment be used to finance skilling, In principle, more private finance needs to be directed to the skilling agenda if it is to be sustainable, hence the need to find financing models that can enable this.
The report warns that 86% of green jobs in 2030 will be informal. How can stakeholders extend social protection and career pathways to informal workers, especially women and youth?
By 2030, 86% of green jobs will be informal. That is not a problem to solve for, it is the structure of Africa’s green economy, and any serious strategy has to work within it rather than around it.
Three instruments matter most. Mobile-based social protection, linked to the digital payment platforms that African workers already use, can extend access to health insurance, accident cover, and pensions for self-employed green workers.
Our research is very clear that there is no single African green transition, and a continental template would miss the mark badly
Portable digital credentials, verified through employer records and accessible on basic mobile devices, allow workers to build a recognised skills profile that travels with them across employers and markets. For young people in particular, this converts informal experience into a career asset.
Finally, giving micro-distributors access to working capital and trade finance allows nano and micro-enterprises to build the enterprise performance records that financial institutions need to extend credit. This is how you move someone from a survivalist activity to a sustainable livelihood.
Staying with women, they are concentrated in lower value, commission-based roles. What targeted interventions could ensure gender equity and progression opportunities in the green economy?
Women are projected to hold 31% of green jobs by 2030 and 44% by 2050. That sounds positive until you look at where those jobs are concentrated—the lowest-value, most informal, commission-based roles, with no contract, no social protection, and no progression pathway.
The barriers are structural and well-documented. Safety and mobility issues prevent women from taking on remote or overnight technical assignments. Women’s care burdens conflict with the rigid schedules of higher-tier roles. Gaps in certification and field placement mean that women who complete technical training often cannot convert it into employment.
The most effective interventions address these simultaneously rather than one at a time.
In South Africa, where the green economy is highly formalised, the levers are procurement standards, worksite infrastructure and embedding these into financing conditionalities so they become institutional expectations rather than voluntary practice.
In Nigeria and Kenya, where growth is happening through informal channels, the priority is expanding women’s access to distribution roles and providing working capital for women-led enterprises through catalytic finance instruments.
Gender covenants in DFI financing, specifying targets by value chain and tracking women in technical and management roles, are the accountability mechanism that makes all of this stick.
Africa’s transition is mainly driven by service-led industries. In your view, which of these sectors are most transformative for inclusive job creation?
Clean cooking stands out. By 2030, it is projected to be the largest green value chain on the continent generating between 1.4 and 2.5 million jobs through micro-distributors, maintenance technicians, and community agents. By 2050, clean cooking employment is projected to grow more than tenfold. The majority of customers are women, which means effective distribution requires women as agents, and the sector is approaching gender parity in our high-scenario projections.
Waste recycling is the other sector I’d highlight. It has the highest accessibility rates for low-income workers, around 72%, and the regulatory frameworks to drive formalisation are already in place in South Africa, Kenya, and increasingly Nigeria. South Africa’s Extended Producer Responsibility regime has already created over 24,000 formal jobs since 2022.
The common thread in both sectors is that employment is driven by service delivery at scale with millions of household connections and collections, not a handful of large construction projects. That is precisely what makes them transformative: the jobs are distributed, the barriers to entry are low, and the potential to reach workers who have been structurally excluded from the formal economy is real.
The report highlights differences across Nigeria, South Africa and Kenya. How should national strategies be tailored to reflect these distinct labour market structures and enabling conditions?
Our research is very clear that there is no single African green transition, and a continental template would miss the mark badly.
Nigeria’s transition is 87% informal and dominated by nano-enterprises. Mandating formalisation will not work at the scale and speed the sector requires. The priority is improving job quality within informal systems—portable credentials, mobile social protection, quality standards within agent networks—while expanding the sectors where women are better represented, like climate-smart agriculture.
South Africa’s transition is 70% formal, shaped by regulated procurement frameworks and the most capitalised just transition plan on the continent. The challenge here is not reaching informal workers; it is reforming conditions within formal systems, particularly the occupational segregation that keeps women’s participation stagnant at around 25%, and ensuring that the shift from construction-phase to operations and maintenance roles translates into improved incomes.
Kenya occupies a middle ground—a renewable electricity system already operational, an emerging e-mobility sector anchored by the continent’s most mature mobile money infrastructure, and a devolved governance structure that requires green skills to be integrated at the county level if employment benefits are to reach workers where deployment is actually occurring.
FSD Africa is launching the Green Jobs Innovation Hub. What role do you envision this initiative playing in bridging the gap between investment in infrastructure and investment in human capital?
The hub is a direct response to the coordination failure that sits at the heart of this problem. Training institutions cannot invest in green skills without demand signals from employers. Employers cannot plan workforces without deployment pipelines. DFIs cannot condition financing on workforce outcomes without data on what those outcomes should look like. And governments cannot sequence skills expenditure without occupation-level employment projections. Everyone is waiting for someone else to move first.
The Green Jobs Innovation Hub is designed to break that deadlock by bringing these actors together around shared data, shared standards, and shared investment. Concretely, The Hub works to unlock financing models that close the workforce investment gap—ensuring that capital flows alongside green infrastructure investment.
Any final thoughts from your side?
The most important thing I want to emphasise is that Africa’s green transition is not primarily a story about solar panels and megawatts. It is a story about millions of micro-distributors, maintenance technicians, waste sorters, and community agents, people who are already doing this work, largely informally, largely without recognition, and largely without protection.
We also have the data now. We know which value chains will generate the most jobs, we know who those jobs will reach, and we know what is preventing more people from accessing better ones.
Therefore, we should stop separating the infrastructure conversation from the human capital conversation. They are the same investment. And until we finance them that way, we will keep building green infrastructure that imports its skills and perpetuates the same development challenges we’ve seen over the years.










 Business5 days ago
 Business5 days ago
 Uncategorized5 days ago
 Business2 days ago
 Business1 day ago
 Business2 days ago
 Energy1 day ago
 Business1 day ago