Connect with us

Business

Global advertising spend to surpass $1trn for first time this year

Published

on

WARC
Projected 10.7% rise in global spend this year equivalent to an additional $104bn in advertiser investment, the second-highest absolute rise on record

One in five dollars (22.1%) spent on ads outside of China is paid to Google; DOJ ruling now threatens $32.9bn of potential growth over the next two years

Advertisers are due to spend $299bn this holiday season, with online platforms such as Amazon ($16.9bn in holiday-season ad revenue) set to be the biggest beneficiaries

WARC Global Ad Spend Outlook 2024/25 – November 2024 update
27 November 2024 – A new study from WARC, the experts in marketing effectiveness, has found that global advertising spend is on course to grow 10.7% this year to a total of $1.08trn – the strongest growth rate in six years and the largest absolute rise on record if the post-Covid recovery of 2021 (+27.9% year-on-year) is disregarded. The new forecast, published today, represents a 0.2 percentage point (pp) upgrade on WARC’s last global forecast in August.  
 Ad spend growth is also anticipated next year (+7.6%) and in 2026 (+7.0%), culminating in a global advertising market worth $1.24trn. Global ad investment has more than doubled over the last decade and has grown 2.8x faster than global economic output since 2014.WARC’s latest global projections are based on data aggregated from 100 markets worldwide. New for this edition, WARC is leveraging a proprietary neural network which projects advertising investment patterns based on over two million data points, spanning macroeconomic data, media owner revenue, marketing expenses from the world’s largest advertisers, media consumption trends and media cost inflation. It is believed to be one of the most comprehensive advertising market models available to the industry today.While the headline growth rate is mostly being driven by online media, a good year for TV has also made a notable contribution. Linear TV spend is expected to end the year 1.9% higher, at $153.6bn, following two years of decline. TV has been boosted by political advertising – particularly in the US – during the fourth quarter and both the Paris Olympics and the Euro 2024 football tournament in the third. Linear TV now accounts for just 14.3% of global advertising spend, however, down from a peak of 41.3% in 2013.Building upon a solid performance for legacy media, pure play internet, which encompasses advertising revenue among online-only businesses such as Alphabet, Amazon and Meta, is poised to grow by 14.1% to a total of $741.4bn – over two thirds (68.8%) of all ad spend.Social media is the largest individual sector within pure play internet – and the largest advertising medium of all by extension – with a total of $252.7bn this year equivalent to 23.5% of the global ad market. Prospects for the social market have been revised upwards this year to +19.3%, owing mostly to stronger-than expected results for Facebook, Instagram and TikTok over the first nine months of the year.James McDonald, Director of Data, Intelligence and Forecasting, WARC, and author of the research says: “Our latest forecast anticipates $104bn in incremental advertising spend worldwide this year, the largest rise in history if the post-pandemic recovery year of 2021 were discounted.“Whether this boom will sustain remains unclear, however, as 2025 presents a sliding doors moment due to heightened regulatory pressures on Google and TikTok – together a quarter of the ad market outside of China. This, alongside an increasingly challenging geopolitical climate, may spell uncertain times ahead for the businesses that rely on advertising trade.“By leveraging WARC’s proprietary neural network, which delivers timely and precise insights based on over two million datapoints, practitioners can navigate these dynamic conditions and plan ahead for a rapidly evolving advertising landscape.”Key themes outlined in WARC’s Global Ad Spend Outlook 2024/25 Q4 update are:GOOGLE’S 90% SHARE OF SEARCH MARKET IS A MONOPOLY, DOJ RULESOne in five dollars (22.1%) spent on advertising outside of China is paid to Google for its search services. Further, at an expected $197.7bn in 2024 (+13.0% year-on-year), Google alone accounts for 90.1% of all search advertising (excluding China). These commanding shares are similar in the US, leading the Department of Justice (DOJ) to rule last week that Google has an effective monopoly on the search market.The court believes that Google also uses its search dominance to inflate the cost per click (up by approximately 7.5% this year) and maintain superior targeting, effectively blocking competitors from offering viable alternatives.Outcomes from the ruling range from Google ceasing payments to handset manufactures and others for default preference – at a cost of approximately $30bn per annum – to the selling off of its Chrome business to a third party.One potential suitor – Bing – still struggles with adoption and advertiser investment despite Microsoft’s $100bn investment, accounting for just 5.9% of search spend outside of China. Bing’s ad revenues are expected to be up just 5.1% this year – compared to a rise of 11.9% for total search and 13.0% for Google – to a total of $12.9bn.Apple already makes $5.1bn from search ads, mostly via its app store, per Omdia Advertising Intelligence estimates, and could create its own search engine given its financial and distribution resources. The device manufacturer may hesitate to proceed, however, due to the high costs associated with maintaining a search business aside a general strategic misalignment. A leftfield entrant – perhaps Elon Musk’s X on the lookout for new revenue streams after losing $5.9bn in ad revenue since its 2022 takeover – may materialise, but on the whole natural successors to Google remain unclear.With the ongoing uncertainty around the practicalities of the DOJ ruling, and the probability that Google will appeal it vigorously in the coming months, WARC is maintaining its growth forecast of +9.0% next year and +7.0% in 2026 for the company while the situation develops, leaving a potential $231bn ad business and $32.9bn of growth in the balance over the next two years.HOLIDAYS ARE COMINGAdvertisers the world over are expected to spend $299.2bn during the final quarter of the year, well over half of which will be spent during the holiday season. This represents a 10.2% rise from the previous year, up marginally (+0.2pp) from our August forecast.The fourth quarter is crucial for retailers, typically accounting for over 30% of annual ad spend within the sector which represents the intense battle for consumer salience and share of wallet each year. Retailers will spend $45.6bn on advertising during Q4 2024, up 5.0% compared to last year. TV is set to attract 15.9% of this spend, at $6.8bn, with nearing a quarter (23.3%) of this – $1.6bn – spent on ads delivered via connected TVs (CTV) so as to leverage the additional targeting capabilities these devices can afford advertisers.Advertising on retail media platforms is also set to peak during the fourth quarter as brands vie to reach consumers close to the point of purchase. Globally, retail media spend is forecast to rise 16.4% in Q4 2024 to a total of $46.2bn – a new high. Amazon alone is expected to net $16.9bn from advertisers at this time, up 18.0% from the previous year.The technology and electronics sector is expected to spend most in online retail media environments during the fourth quarter, with an anticipated total of $7.2bn up 18.7% from last year. For context, this is over three times more than the sector spends on TV.It’s also a big time of year for fast-moving consumer goods (FMCG) brands, with the alcoholic drinks (+13.5% to $3.9bn), cosmetics (+13.8% to $5.2bn), food (+19.4% to $5.4bn) and soft drinks (+22.0% to $4.5bn) sectors all increasing retail media spend and allocating an increasing share of their ad budgets to online retail platforms this year.Overall, retail media ad spend is forecast to reach $154.8bn this year, with a further rise of 14.8% expected next year and 13.5% in 2026, by when the market would be worth $201.6bn.CANADA CALLS TIME ON TIKTOKThis month, the Canadian government ordered TikTok Technology Canada, Inc. to wind up its Canadian operations under the Investment Canada Act, citing national security concerns. This move forces TikTok to halt sales operations in Canada but does not block Canadians’ access to the app or its content creation capabilities. TikTok has vowed to challenge the order in court.There are few signs that advertisers are reining in their TikTok budgets; WARC believes TikTok’s ad billings grew by 27.1% to $17.8bn over the first nine months of 2024, even as the prospect of tighter regulation comes into sharper focus.Globally, TikTok’s audience is now almost at parity with Instagram, but users spend twice as long with TikTok. A ban is most likely to be to the benefit of Instagram, Snap and, to a lesser extent, YouTube thanks to its analogous Shorts format, mostly due to the migration of content creators.Brian Wieser of Madison & Wall estimates that some C$500m annually will be up for grabs if TikTok were to exit Canada. This scenario has not yet been factored into WARC’s forecasts pending the appeal process; indeed, WARC now expects TikTok to generate $24.6bn in advertising revenue (excl. China) this year, a rise of 25.9% from 2023 but equivalent to just 9.1% of all social advertising spend.A complimentary executive summary by WARC’s James McDonald, author of the report, is available to read here. WARC subscribers can read the article and access additional data here.

Business

African Energy Week (AEW) 2026 Technical Sessions Put Technology Behind Africa’s Next Energy Projects in Focus

Published

on

Day 2 technical sessions at African Energy Week 2026 will examine frontier exploration, major gas developments, project economics and the technologies supporting Africa’s expanding oil, gas and LNG sectors

CAPE TOWN, South Africa, September 22, 2026/APO Group/ –African Energy Week (AEW) 2026’s Day 2 Technical Stages will put the technology and technical expertise behind Africa’s next wave of energy projects in focus, with sessions covering subsurface interpretation, deepwater exploration, gas development, project economics, digitalization, offshore operations and infrastructure.


The program will unfold across two exhibition-hall stages, with the Drill Room focusing on practical applications across exploration, gas development, offshore operations and LNG, while the Innovation Hub will examine frontier exploration, energy markets, digital technologies and infrastructure. Together, the sessions connect project-level technologies with the wider investment and development challenges facing Africa’s energy industry.

The day opens with GeoEnergy Petroleum Director Maged Fahim, who will examine how legacy and newly acquired subsurface datasets can be integrated with modern technologies to identify additional upstream opportunities. TGS Principal Exploration Advisor Felicia Winter will then focus on Angola’s deepwater basins, examining how modern seismic acquisition and imaging can be used to reinterpret existing data and evaluate frontier plays.

The discussions come as Angola seeks to build on renewed offshore activity. TotalEnergies announced in September that it plans to invest $10 billion in Angola over the next five years, including in exploration, while advancing its $6 billion Kaminho deepwater development.

Gas development will take center stage through two presentations by TotalEnergies. Alexandre Depiesse, GPI Venus, will address appraisal strategies and commercial viability for Orange Basin discoveries, while Mozambique LNG Operations and Project Director Nicolas Cambefort will examine development and optimisation of the Rovuma Basin gas resources. Mozambique LNG, a 13.1-million-ton-per-year project in Area 1 led by TotalEnergies, resumed activities in January 2026 following the lifting of force majeure, putting development of Mozambique’s major offshore gas resources back into focus.

AEW 2026 reflects the practical challenges facing Africa’s energy industry as projects move from resource potential toward development and production

The Republic of Congo National Showcase will provide another perspective on Africa’s expanding LNG industry. The country’s Congo LNG project reached a new stage in February 2026 with the start of commercial production from its second phase. The addition of the Nguya FLNG unit brought total liquefaction capacity to 3 million tons per year, expanding Congo’s ability to monetize its offshore gas resources.

The program will then broaden from individual projects to the continent-wide investment outlook with the launch of The State of African Energy 2027. AEC Senior Vice President Verner Ayukegba and S&P Global Energy Executive Director Max Pietzsch will present the outlook, covering upstream oil and gas, LNG, downstream markets, power, renewables and critical minerals against changing demand, trade flows and energy security requirements.

Project decision-making will remain under examination as S&P Global Energy Technical Research Analyst Tasnika Goorhoo presents “From Limited Data to Better Decisions: How Benchmarking Strengthens Upstream Project Outcomes.” The session will examine how comparative project data can help operators assess performance, costs and development outcomes.

NOV Vice President Mats Anderson will address offshore optimization through high-speed downhole connectivity and real-time distributed measurements, examining how faster access to downhole information can improve operational visibility and decision-making.

Infrastructure will also feature prominently, with Kenyon International West Africa CEO Victor Ekpenyong examining asset integrity and pipeline infrastructure through the company’s CACTUS and FlexSteel technologies. Honeywell Technologies Africa will close the technology-focused sessions with its end-to-end LNG offering, while SLB, InSwitch, the Petroleum Directorate of Sierra Leone and PETROSEN will bring additional perspectives on technology, digitalization and energy services.

“AEW 2026 reflects the practical challenges facing Africa’s energy industry as projects move from resource potential toward development and production,” said NJ Ayuk, Executive Chairman of the AEC. “From subsurface interpretation and deepwater exploration to LNG development, project benchmarking, digitalization and infrastructure, these technical sessions highlight the expertise and technologies needed to develop Africa’s resources efficiently and create lasting value across the energy value chain.”

AEW 2026 takes place from October 12–16 in Cape Town, bringing together governments, investors, operators and technology providers to discuss investment, project development and the future of Africa’s energy sector.

Distributed by APO Group on behalf of African Energy Chamber.


Continue Reading

Business

Rising power costs put energy strategy at the centre of industrial competitiveness

Published

on

C&I Energy + Storage Summit Johannesburg to focus on the procurement, cost and investment decisions facing South Africa’s large energy users

JOHANNESBURG, South Africa, September 22, 2026/APO Group/ –The cost of electricity is no longer only an energy issue for South African businesses. It is increasingly a question of competitiveness, investment and long-term operational resilience.

Recent figures show the pressure on large power users. Business Day reported on 7 September that South Africa’s mining and industrial majors paid Eskom R115 billion for electricity in the 2025/26 financial year. According to Eskom’s annual report, industrial electricity demand fell by more than 22% over the same period as high power costs weighed on energy-intensive operations.


At the same time, major businesses are moving to alternative supply. Reuters reported on 26 August that South African mining companies are accelerating investment in renewable energy to cut costs, diversify supply and meet decarbonisation targets.

For commercial and industrial energy users, the question is no longer simply how to secure power. It is how to buy it, what to invest in, and which energy strategy makes the strongest commercial sense.

Energy procurement is becoming more complex

Businesses are now weighing several procurement options at once. Should they sign a long-term PPA? Buy through an electricity trader? Wheel renewable power across the grid? Invest in behind-the-meter generation? Add battery storage? Each option carries different implications for cost, risk, contracting and long-term flexibility.

These decisions will take centre stage at the C&I Energy + Storage Summit Johannesburg, taking place on 28–29 October 2026 at The Maslow Hotel, Sandton. The programme is built around the practical challenges facing energy buyers today, with a focus on real projects, commercial models and implementation rather than technology in isolation.

A programme built around the buyer’s decisions

The summit closes with the C&I Decision Clinic: Ask the Experts, a masterclass where attendees submit real project challenges in advance and receive practical, anonymised responses from experts. Questions on the table include whether to build onsite PV or sign a wheeled PPA, how much battery storage makes commercial sense, what a bankable project preparation pack should contain, and what financiers require before term sheet stage.

It follows The C&I Energy Playbook: Five decisions business leaders need to make now, a closing panel in which the moderators of key summit sessions distil the programme into the priorities C&I businesses should act on.

Other sessions address the questions buyers are asking now:

  • Energy storage beyond backup power: unlocking commercial value examines peak shaving, demand charge management, energy arbitrage and hybrid PV-plus-storage business models, along with the operational realities of dispatch, degradation and warranties.
  • Making public-private engagement work for you unpacks how wheeling agreements are structured in practice, where interface risks arise, and how businesses can engage utilities and municipalities early.
  • Reducing energy costs without building new generation is a case-study-led workshop on energy efficiency, operational optimisation, demand response and digital energy management.
  • Projects Spotlight gives energy users the floor to share the strategies they have implemented, the lessons learned and the outcomes achieved.

The programme opens with the keynote panel Threats and opportunities in South Africa’s industrial future, bringing together policymakers, industrial leaders, financiers, and energy and water experts.

Bringing energy buyers into the conversation

The summit’s Hosted Buyer Programme is designed for qualified end-user energy buyers across sectors including mining, manufacturing, property, agriculture and other energy-intensive industries. Hosted buyers take part in the full programme and receive curated engagement with solution providers across energy procurement, storage deployment and project development.

Four events, one venue

The summit is co-located with the EIUG Conference, Water Security Africa and the Data Centre Summit, bringing the energy, water and digital infrastructure communities together in Sandton. It is brought to you by Enlit Africa, with ESI Africa as host media, and is accredited by the SAIEE.

Qualified commercial and industrial energy users can apply for the Hosted Buyer Programme at https://apo-opa.co/4yPnXOg, and bring their project questions to the Decision Clinic.

Full programme: https://apo-opa.co/4xK2ANv


Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Events

Beyond the carbon credit: Who sets the terms for Africa’s carbon markets?

Published

on

From project ownership and verification to pricing and benefit-sharing, CMAS 2026 will bring African market leaders and global decision-makers together to examine who creates and captures value

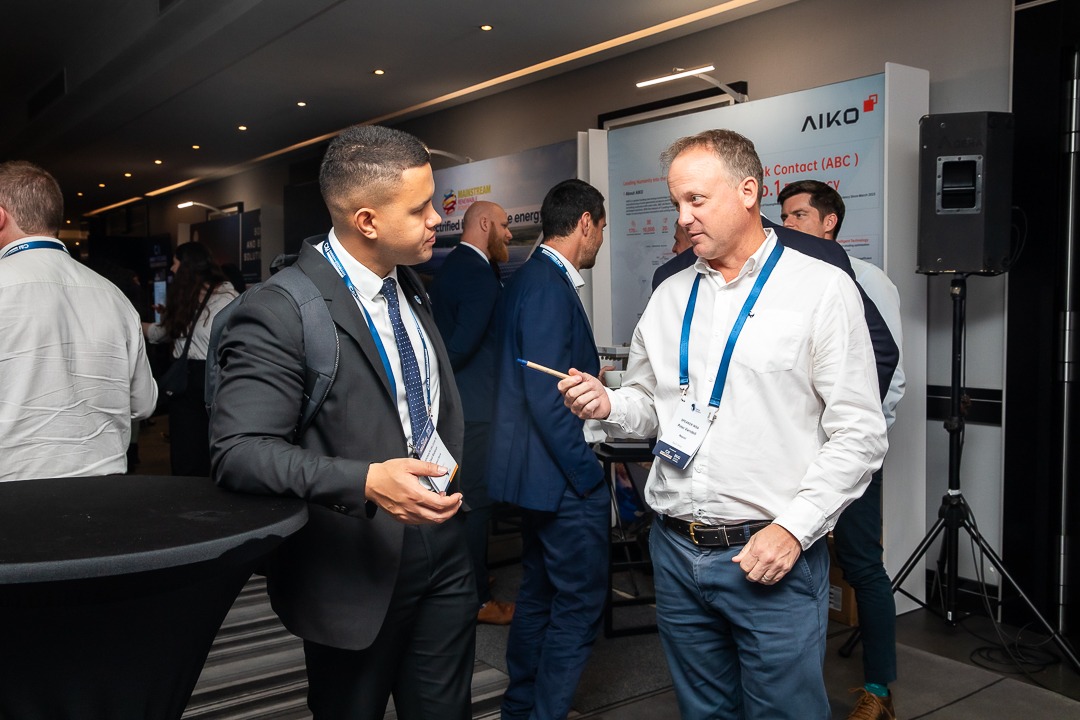
KIGALI, Rwanda, September 22, 2026/APO Group/ –A carbon credit may be traded as a single unit, but its value is shaped long before it reaches a buyer. Decisions about project ownership, finance, data, verification and benefit-sharing determine who participates, who carries the risk and who ultimately benefits. As new regulations and international partnerships expand market access, these questions are becoming increasingly important across Africa.


They will be central to the Carbon Markets Africa Summit (CMAS) 2026, taking place from 13 to 15 October at the Kigali Convention Centre in Rwanda. The summit will convene African governments, project developers, investors, buyers and technical experts involved in decisions across the carbon-market value chain.

Countries are approaching these decisions from different regulatory, economic and environmental positions. While recent developments in East Africa demonstrate growing market activity, questions concerning international requirements, technical capacity, investment and benefit-sharing are relevant across Africa.

Ousmane Fall SARR, Coordinator of the West African Alliance on Carbon Markets and Climate Finance, says:

“African countries are developing carbon markets from different starting points. Stronger African expertise and regional cooperation will be important if the continent is to contribute to the standards and market practices that determine how its projects compete, attract investment and create value.”

Against this continental backdrop, East Africa provides a timely example of how the market is developing. In January 2026, Rwanda and Singapore invited applications for carbon-credit projects under their bilateral Implementation Agreement, aligned with Article 6 of the Paris Agreement. Credits from authorised projects may be used by eligible Singapore-based carbon tax-liable companies to offset up to 5% of their taxable emissions, subject to both governments’ requirements.

African countries are developing carbon markets from different starting points

Across the continent, carbon market frameworks are rapidly taking shape. Kenya and Uganda are strengthening regulatory oversight, regional partnerships are helping governments build market capacity and infrastructure, and South Africa is advancing reforms to modernise its carbon-credit ecosystem and attract investment. Together, these developments are bringing greater focus to questions of authorisation, project ownership, verification, pricing and access to international buyers, while also raising expectations that carbon finance should deliver sustainable economic and development value beyond the credit itself.

Emmanuelle Nicholls, Portfolio Director for CMAS, says:

“A carbon credit may be the final product, but behind it are decisions about ownership, data, risk, pricing and who ultimately benefits. The conversations in Kigali will examine what credible participation looks like across the full carbon-market value chain.”

These decisions have consequences beyond individual transactions. Carbon finance is increasingly connected to conservation, agriculture, soil restoration, food security, clean energy and waste management. Its success will therefore also be judged by whether projects produce credible environmental outcomes and lasting benefits for African economies and communities.

A practical example comes from the Chinko Conservation Area in the Central African Republic, where revenue from the Chinko Carbon Project is channelled through a community fund that supports locally selected initiatives, including the expansion of a medical centre in Agoumar. At CMAS 2026, African Parks and Welthungerhilfe, both Bronze Sponsors, will share perspectives on how carbon finance can support conservation, climate resilience, food systems and community development, while highlighting broader questions around project governance, impact and the distribution of value.

From project-level impact to market-wide structures, these questions will underpin discussions at CMAS 2026. The programme will address government authorisation, buyer requirements, pricing and offtake, investment risk, early-stage finance, registries and African measurement, reporting and verification capacity. It will connect the question of who sets the terms with the practical requirements for building credible, investment-ready projects and transactions.

CMAS 2026 is hosted by the Ministry of Environment of Rwanda, with UNDP and the African Development Bank as host organisations, the Development Bank of Southern Africa as host partner and AUDA-NEPAD as strategic institutional partner.

Taking place ahead of COP31, CMAS will focus attention on the decisions behind every carbon credit and what they mean for African governments, projects, investors and communities.

Distributed by APO Group on behalf of VUKA Group.


Continue Reading

Trending

Exit mobile version